EXCHANGE: COMEX
CONTRACT: OCTOBER 2026 COMEX 100 GOLD FUTURES
SETTLEMENT: 4,147.700000000 USD
INTENT DATE: 09/29/2026 DELIVERY DATE: 10/01/2026
FIRM ORG FIRM NAME ISSUED STOPPED
092 C DEUTSCHE BANK 1461
099 H DEUTSCHE BANK AG 817
118 C MACQUARIE FUTURES US 600 173
323 C HSBC 200
332 H STANDARD CHARTERED B 834
363 H WELLS FARGO SECURITI 834
624 H BOFA SECURITIES 929
657 C MORGAN STANLEY 28
661 C JP MORGAN SECURITIES 6220 7273
686 C STONEX FINANCIAL INC 67
690 C ABN AMRO CLR USA LLC 5
709 C BARCLAYS 75
732 C RBC CAP MARKETS 620 324
737 C ADVANTAGE FUTURES 12
905 C ADM 19 3
TOTAL: 10,247 10,247
MONTH TO DATE: 10,247
GOLD: NUMBER OF NOTICES FILED FOR OCT./2026: 10,247 CONTRACTs NOTICES FOR 1,024,700 OZ or 31.872 TONNES
total notices so far: 10,247 contracts FOR 1,024,700 OZ OR 31.872 TONNES
SILVER NOTICES:1953 NOTICE(S) FILED FOR 9.75 MILLION OZ /
total number of notices filed so far this month : 1957 CONTRACTS (NOTICES) for 9.785 million oz
GLD
SEPT: INITIAL STANDING: 24.172 MILLION OZ//FOLLOWED BY TODAY’S STRONG 70 CONTRACT OR 350,000 OZ QUEUE JUMP//STANDING ADVANCES TO 33.865 MILLION OZ//
OCT: INITIAL STANDING: 16.355 MILLION OZ
SEPT: INITIAL STANDING 8.756 MILLION OZ//FOLLOWED BY TODAY’S 350,000 OZ QUEUE JUMP//STANDING ADVANCES TO 33.865 MILLION OZ
OCT: INITIAL STANDING: 16.355 MILLION OZ
GOLD COMEX OUTLINE;
1.MAY SUMMARY FOR MAY TONNES WHICH STOOD FOR DELIVERY:
4. AUGUST: 60.547 TONNES OF INITIAL GOLD FIRST DAY NOTICE FOLLOWED BY THE NET MONTH’S QUEUE JUMP OF 47.2312 TONNES TO WHICH WE ADD THE FOLLOWING EXCHANGE FOR RISK ISSUANCE RECEIVED FOR THE MONTH: 5.4432 TONNES EX FOR RISK/AUG 7 , AUG 11: 2.413 TONNES EX FOR RISK AND AUG. 12 OF 2.
5.SEPT: INITIAL 8.093 TONNES OF GOLD PLUS TODAY’S QUEUE JUMP OF 0.4883 TONNES PLUS 2.2827 TONNES OF EXCHANGE FOR RISK TODAY//NEW TOTAL EX. FOR RISK/MONTH = 22.923//NEW TOTAL STANDING FOR GOLD SEPT ADVANCES TO = 48.801 TONNES!!
6.OCTOBER: 90.012 TONNES OF INITIAL GOLD STANDING WITH TODAY’S TINY 0.00311 TONNES QUEUE JUMP WHICH FOLLOWS ALL OTHER QUEUE JUMPS DURING OCT OF 76.1656 TONNES
THEN WE MUST ADD OUR 14.553 TONNES OF OUR ISSUANCE OF EXCHANGE FOR RISK/6 OCCASIONS//NEW TOTAL OF GOLD STANDING ADVANCES TO 197.5141 TONNES OF GOLD.
7.NOVEMBER BEGINS WITH 15.651 TONNES INITIALLY STANDING FOR DELIVERY FOLLOWED BY TODAY’S QUEUE JUMP OF 2.323 TONNES FOLLOWED BY ALL PREVIOUS QUEUE JUMPS IN OF OF 21.3775 TONNES TO WHICH WE ADD OUR TWO EXCHANGE FOR RISK ISSUANCE OF 4.5596 TONNES//NEW STANDING ADVANCES TO 43.9716 TONNES OF GOLD.
8. DECEMBER BEGINS WITH INITIAL STANDING OF 83.813 TONNES OF GOLD FOLLOWED BY TODAY’S 0.0TONNE QUEUE JUMP WHICH FOLLOWS ALL OTHER QUEUE JUMPS OF: 37.163 TONNES//NEW STANDING ADVANCES TO 115.390 TONNES TO WHICH WE ADD OUR 4 EXCHANGE FOR RISK FOR DECEMBER OF 6.587 TONNES/NEW STANDING ADVANCES TO 121.977 TONNES
9. JANUARY: INITITAL STANDING: 13.785 TONNES TO WHICH WE ADD OUR FIRST EXCHANGE FOR PHYSICAL TRANSFER OF 0.08709 TONNES WHICH FOLLOWS ALL OTHER QUEUE JUMPS OF 30.7117TONNES //NEW TOTAL QUEUE JUMPS 30.7117//NORMAL DELIVERY OF GOLD ADVANCES TO 36.8958 TONNES TO WHICH WE ADD OUR SIX EXCHANGE FOR RISK OF 22.315 TONNES//NEW STANDING ADVANCES TO 59.2108 TONNES.
FEB; INITIAL AMOUNT OF GOLD STANDING FOR DELIVERY: 93.567 TONNES OF GOLD TO WHICH WE ADD OUR NEXT 0.0248 TONNES 0.1555 TONNES QUEUE JUMP TO 41.2082 TONNES/ NEW NET QUEUE JUMP INCREASES TO 41.233 TONNES// AND THEN WE ADD OUR SIX EXCHANGE FOR RISK: 10,080 CONTRACTS OR 31.251 TONNES//NEW STANDING REDUCES TO 157.878 TONNES
MARCH:: INITIAL AMOUNT OF GOLD STANDING FOR DELIVERY: 8.099 TONNES TO WHICH WE ADD TODAY’S FAIR 4600 OZ QUEUE JUMP (0.2320 TONNES) AND THEN WE ADD OUR THREE EXCHANGE FOR RISK OF 22.3818 TONNES //NEW STANDING ADVANCES TO 67.6648 TONNES/
APRIL: INITIAL AMOUNT OF GOLD STANDING FOR DELIVERY: 52.600 TONNES FOLLOWED BY OUR 345 CONTRACT QUEUE JUMP FOR 34,500 OZ/ (1.073 TONNES)/NEW STANDING ADVANCES TO 70.286 TONNES TO WHICH WE ADD OUR 2ND EXCHANGE FOR RISK OF 1498 CONTRACTS FOR 149800 OZ OR 4.659 TONNES. THE NEW TOTAL EXCHANGE FOR RISK FOR THE MONTH OF APRIL IS 2239 CONTRACTS OR 223900 OZ OR 6.964 TONNES AND THIS WILL BE ADDED TO OUR NORMAL DELIVERY TOTALS (70.762 TONNES) TO GIVE US WHAT WILL STAND IN APRIL (77.726 TONNES)
MAY: INITIAL AMOUNT OF GOLD WILLING TO STAND: 12.24 TONNES OF GOLD TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 345 CONTRACTS OR 34500 OZ (1.073 TONNES) TO WHICH WE ADD OUR FIVE EXCHANGE FOR RISK ISSUANCES FOR 24.635 TONNES/STANDING NOW ADVANCES TO 51.554 TONNES OF GOLD.
JUNE; INITIAL AMOUNT OF GOLD WILLING TO STAND; 64.496 TONNES.(CME CORRECTED) TO WHICH WE ADD OUR NEXT EXCHANGE FOR PHYSICAL TRANSFER OF 0.0186 TONNES/NEW STANDING REDUCES TO 127.03 TONNES
JULY: INITIAL AMOUNT OF GOLD WILLING TO STAND: 23.306 TONNES TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 0.000 TONNES/ TO WHICH WE ADD OUR FIRST EXCHANGE FOR RISK 0F 0.0062 TONNES/NEW STANDING ADVANCES TO 40.824TONNES
AUGUST INITIAL STANDING 48.687 TONNES TO WHICH WE ADD OUR 5TH EXCHANGE FOR RISK OF 5 CONTRACTS FOR 500 OZ OR 0.0155 TONNESS TO OUR 4TH EXCHANGE FOR RISK OF 200 CONTRACTS OR 20,000 OZ OR 6.220 TONNES TO OUR 3RD EXCHANGE FOR RISK OF 1.7045 TONNES TO OUR 2ND EXCHANGE FOR RISK OF 1.552 TONNES TO OUR FIRST 0.0715 TONNES EXCHANGE FOR RISK//NEW TOTAL EXCHANGE FOR RISK: 3.9688 AND THEN ADD OUR NEXT QUEUE JUMP OF 39 CONTRACTS FOR 3,900 OZ OR 0.1213 TONNES//STANDING THUS ADVANCES TO 67.2441 TONNES
SEPT: INITIAL STANDING: 8.756 TONNES OF GOLD FOLLOWED BY TODAY’S 0 CONTRACTS OR 0 OZ QUEUE JUMP (0.0000 TONNES) TO WHICH WE ADD OUR TWO, 2000 CONTRACT EXCHANGE FOR RISK FOR 200,000 OZ OR 6.2208 TONNES//// // NEW STANDING REMAINS AT 19.2308 TONNES..
OCT: INITIAL STANDING: 38.345 TONNES OF GOLD
IN ESSENCE WE HAVE A FAIR GAIN IN TOTAL CONTRACTS IN GOLD ON THE TWO EXCHANGES OF 2485 CONTRACTS WITH 1215 CONTRACTS INCREASED AT THE COMEX// AND A FAIR SIZED 1270 EXCHANGE FOR PHYSICAL OI CONTRACT ISSUANCE WHICH NAVIGATED OVER TO LONDON.
THUS TOTAL OI GAIN ON THE TWO EXCHANGES OF 2485 CONTRACTS.. WE HAD THE FOLLOWING TAS CONTRACTS INITIATED (ISSUED): A SMALL SIZED AND CRIMINAL 962 CONTRACTS AND THESE ISSUANCES ARE GENERALLY USED TO INITIATE A RAID WHEN CALLED UPON .
GOLD PRICE ROSE BY $11.75
STANDING FOR THE LAST 8 MONTHS JANUARY TO AUGUST:
FINAL STANDING FOR GOLD, JANUARY CONTRACT AT 59.08 TONNES OF GOLD
FEBRUARY: INITIAL STANDING FOR GOLD: 157.878 TONNES!! WHICH INCLUDES ALL QUEUE JUMPING, THREE EXCHANGE FOR PHYSICAL TRANSFERS TO LONDON AND OUR SIX ISSUANCES EXCHANGE FOR RISK!!
MARCH: INITIAL STANDING AT 8.099 TONNES TO WHICH WE ADD OUR FINAL DAY: 0.2320 TONNES QUEUE JUMP AND THEN ADD +22.3818 TONNES EXCHANGE FOR RISK//NEW STANDING ADVANCES TO 67.6648 TONNES
APRIL: INITIAL STANDING 52.600 TONNES PLUS 27,800 OZ QUEUE JUMP (0.8648TONNES): NEW STANDING ADVANCES TO 70.286 TONNES PLUS OUR TWO EXCHANGE FOR RISK FOR 223,900 OZ OR 6.964 TONNES/NEW FINAL STANDING: 77.726 TONNES
MAY: INITIAL AMOUNT OF GOLD WILLING TO STAND; 12.24 TONNES TO WHICH WE ADD OUR NEXT QUEUE JUMP FOR 345 CONTRACTS/34,500 OZ// 1.073 TONNES/ THEN WE MUST ADD OUR EXCHANGE FOR RISK ISSUANCE: TOTAL EXCHANGE FOR RISK MAY// 5 OCCASIONS: 24.635 TONNES///NEW FINAL STANDING NOW ADVANCES TO 51.554 TONNES
JUNE: INITIAL AMOUNT OF GOLD WILLING TO STAND: 64.496 TONNES TO WHICH WE ADD OUR NEXT EXCHANGE FOR PHYSICAL TRANSFER JUMP OF 0.0186 TONNES//NEW STANDING 127.03 TONNES//FINAL
JULY: INITIAL AMOUNT OF GOLD WILLING TO STAND: 23.306 TONNES OF GOLD TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 0.0000 TONNES/ PLUS 0.0062 TONNES EX FOR RISK///NEW STANDING FOR GOLD REMAINS AT 40.824TONNES.
AUGUST INITIAL STANDING 48.687 TONNES TO WHICH WE ADD OUR FIRST 0.0715 TONNES EXCHANGE TO OUR 2ND EXCHANGE FOR RISK = 1.552 TONNES TO OUR 3RD EXCHANGE FOR RISK OF: 1.7045//TOTAL FOR EXCHANGE FOR RISK 3.3312 TONNES TO OUR 4TH EXCHANGE FOR RISK OF 200 CONTRACTS FOR 0.6220 TONNES/TO OUR 5TH EXCHANGE FOR RISK OF 0.0155 TONNES//TOTALL EXCHANGE FOR RISK: 3.9688 TONNES TO OUR NEXT QUEUE JUMP OF 0.1213 TONNES//STANDING ADVANCES TO 67.2441 TONNES
SEPT: INITIAL STANDING FOR GOLD: 8.756 TONNES FOLLOWED BY TODAY’S 0 OZ QUEUE JUMP (0.0000TONNES) TO WHICH WE ADD OUR SECOND 1000 CONTRACT EXCHANGE FOR RISK TO OUR FIRST: THUS// NEW EXCHANGE FOR RISK: 6.2208 TONNES// NEW STANDING REMAINS AT 19.2308 TONNES.
OCT: INITIAL STANDING FOR GOLD: 38.345 TONNES
JAN. 2025: 257.919 TONNES (ISSUANCE WILL BE PRETTY GOOD THIS MONTH BUT MUCH LOWER THAN LAST MONTH)
FEB: 207.21 TONNES//EX FOR PHYSICAL ISSUANCE (WILL BE A FAIR SIZED ISSUANCE THIS MONTH)
MARCH 130.84 TONNES//QUITE SMALL THIS MONTH.
APRIL; 208.57 TONNES. STRONG THIS MONTH
MAY: 113.499 TONNES OF GOLD EFP ISSUANCE//QUITE SMALL THIS MONTH
JUNE: 97.79 TONNES OF GOLD EFP ISSUANCE/EXTREMELY SMALL
JULY : 150.877 TONNES// QUITE SMALL
AUGUST: 175.86 TONNES A LOT LARGER THIS MONTH.
SEPT. 116.13 TONNES VERY SMALL
OCT. 252.72 TONNES//CERTAINLY MUCH LARGER THIS MONTH/VERY STRONG
NOV: 124.74 TONNES
DEC: 190.04 TONNES//GOOD SIZED THIS MONTH FINAL.
TOTAL EXCHANGE FOR PHYSICAL ISSUED FOR YEAR 2025: 2,026.20 TONNES (LOWER THAN LAST YR 2,569.00 TONNES
YEAR 2026:
JANUARY: 209.08 TONNES ( (WILL BE A STRONG MONTH FOR EXCHANGE FOR PHYSICAL)
FEB. 176.35 TONNES (WHICH IS A FAIR ISSUANCE)
MARCH: 214.67 TONNES//WILL BE STRONG ISSUANCE THIS MONTH
APRIL; 88.00 TONNES// WILL BE VERY SMALL THIS MONTH
MAY 118.430 TONNES
JUNE: 142.053 TONNES
JULY: 163.82 TONNES
AUGUST: 151.107 TONNES
SEPT: 99.458 TONNES
OCT: 103.409 TONNES
XXXXXXXXXXXXXXXXXXXXXXXXXX
SHANGHAI CLOSED UP 11.74 PTS OR 0.31%
HANG SENG CLOSED UP 89.70 PTS OR 0.37%
Nikkei CLOSED UP 1414.73 PTS OR 2.16%
//Australia’s all ordinaries CLOSED UP 0.60%
//Chinese yuan (ONSHORE) CLOSED DOWN TO 6.7046
/ OFFSHORE CLOSED DOWN AT 6.7068 Oil DOWN TO 90.20 dollars per barrel for WTI and BRENT DOWN TO 97.09 Stocks in Europe OPENED ALL MIXED
ONSHORE USA/ YUAN// WITH YUAN TRADING DOWN (6.7046 OFFSHORE YUAN TRADING DOWN TO 6.7068 ONSHORE YUAN TRADING ABOVE LEVEL // OFF SHORE AND UP ON THE DOLLAR)// / AND THUS WEAKER/OFF SHORE YUAN TRADING DOWN AGAINST US DOLLAR/ AND THUS WEAKER
HERE IS A BRIEF SYNOPSIS OF HOW THE CROOKS FLEECE UNSUSPECTING LONGS
YOU WILL ALSO NOTICE THAT THE COMEX OPEN INTEREST STARTS TO RISE BUT SO IS THE OPEN INTEREST OF SPREADERS. THE OPEN INTEREST IN WILL CONTINUE TO RISE UNTIL ONE WEEK BEFORE FIRST DAY NOTICE OF AN UPCOMING ACTIVE DELIVERY MONTH (OCT), AND THAT IS WHEN THE CROOKS SELL THEIR SPREAD POSITIONS BUT NOT AT THE SAME TIME OF THE DAY. THEY WILL USE THE SELL SIDE OF THE EQUATION TO CREATE THE CASCADE (ALONG WITH THEIR COLLUSIVE FRIENDS) AND THEN COVER ON THE BUY SIDE OF THE SPREAD SITUATION AT THE END OF THE DAY. THEY DO THIS TO AVOID POSITION LIMITS
WHAT IS ALARMING TO ME, ACCORDING TO OUR LONDON EXPERT ANDREW MAGUIRE IS THAT THESE EFP’S ARE BEING TRANSFERRED TO WHAT ARE CALLED SERIAL FORWARD CONTRACT OBLIGATIONS AND THESE CONTRACTS ARE LESS THAN 14 DAYS. ANYTHING GREATER THAN 14 DAYS, THESE MUST BE RECORDED AND SENT TO THE COMPTROLLER, GREAT BRITAIN TO MONITOR RISK TO THE BANKING SYSTEM. IF THIS IS INDEED TRUE, THEN THIS IS A MASSIVE CONSPIRACY TO DEFRAUD AS WE NOW WITNESS A MONSTROUS TOTAL EFP’S ISSUANCE AS IT HEADS INTO THE STRATOSPHERE.
The crooks also use the spread in the TAS account (trade at settlement). They buy the spot TAS (e.g. June) and sell the future TAS two months out (e.g. August). Then they unload the front month (i.e. unload the buy side first so the price of gold/silver falls. This occurs in the middle of the front delivery month cycle. They unload the sell side of the equation, two months down the road. The crooks violate position limits as the OCC refuse to hear our complaints.
First, here is an outline of what will be discussed tonight:
SILVER:
1.TODAY WE HAD THE OPEN INTEREST AT THE COMEX IN SILVER ROSE BY A TINY 63 CONTRACTS TO AN OI OF 107,047
EFP ISSUANCE 360 CONTRACTS
OUR CUSTOMARY MIGRATION OF COMEX LONGS CONTINUE TO MORPH INTO LONDON FORWARDS AS OUR BANKERS USED THEIR EMERGENCY PROCEDURE TO ISSUE:
DEC 360 CONTRACTS and 0 ALL OTHER MONTHS: ZERO. TOTAL EFP ISSUANCE: 0 CONTRACTS. EFP’S GIVE OUR COMEX LONGS A FIAT BONUS PLUS A DELIVERABLE PRODUCT OVER IN LONDON. IF WE TAKE THE COMEX OI GAIN OF 63 CONTRACTSAND ADD TO THE 360 E.FP. ISSUED
WE OBTAIN A STRONG GAIN OF 423 OI OPEN INTEREST CONTRACTS FROM OUR TWO EXCHANGES DESPITE OUR LOSS OF $0.58
THUS IN OUNCES, THE GAIN ON THE TWO EXCHANGES TOTAL 2.115 MILLION PAPER OZ
STANDING OCT AT 16.355 MILLION OZ
SILVER PRICE LOSS OF $0.58
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
LET US BEGIN:
THE TOTAL COMEX GOLD OPEN INTEREST ROSE BY A FAIR 1215 CONTRACTS TO 406,456 STILL WELL ABOVE ITS NEW LOW OF 326,052 OI SET JUNE 3, CLOSE TO THE PREVIOUS ALL TIME LOW OF 345,705 SET (MAY 28) AND CLOSE TO THE PREVIOUS ALL TIME LOW IN OI OF 353,490 SET MAY 27.. PREVIOUS TO THAT THE ALL TIME LOW IN OI WAS 390,000 SET IN THE YEAR 2001 WHEN GOLD WAS TRADING $260.00. THE CME SHOULD BE PROUD OF THEMSELVES AS MANY HAVE ABANDONED THIS CROOKED ARENA!!THUS OUR NEW ALL TIME LOW OF COMEX OI HAS NOW BEEN SET AT 326,052 //JUNE 3 2026 WITH GOLD AT AN EXTREMELY HIGH $4,450.00 WHICH MAKES ABSOLUTELY NO SENSE!!!
WE HAD LITTLE T.A.S. LIQUIDATION DURING TUESDAY’S COMEX TRADING HOURS// . IT SEEMS THAT MANY OF THE SPECULATORS THAT HAVE NOW CONTINUED AGAIN TO BE ON THE SHORT SIDE WITH BANKERS ON THE LONG SIDE AND THESE GUYS WERE AGAIN OBLITERATED YESTERDAY WHEN THE LONGS TENDERED FOR DELIVERY:
CENTRAL BANKS TENDERED THEIR NEW LONG CONTRACTS AT THE END OF THE DAY FOR PHYSICAL GOLD. YOU CAN VISUALIZE THIS WITH THE STRONG AMOUNT OF GOLD STANDING AT THE COMEX FOR THIS JULY CONTRACT MONTH!!
WE HAD A FAIR SIZED GAIN ON OUR TWO EXCHANGES (2485 CONTRACTS) OCCURRED DESPITE OUR GAIN IN PRICE IN GOLD (UP $11.75)
WE THUS HAD A FAIR GAIN IN OI ON BOTH OF OUR EXCHANGES (2485 CONTRACTS), WITH OUR GAIN IN PRICE, AS WE WERE INFORMED OF A FAIR CONTRACT EXCHANGE FOR PHYSICAL ISSUANCE EQUATING TO 1270 CONTRACTS.
THEN WE WERE NOTIFIED TODAY OF A 0 CONTRACT FOR RISK ISSUANCE IN GOLD CONTRACTS FOR 0 OZ OR 0 TONNES OF GOLD. TOTAL THUS SO FAR THIS MONTH: 2000 CONTRACTS//200,000 OZ OR 6.2208 TONNES (2 OCCASIONS)
MONTH OF MAY RECORD ISSUANCE OF EXCHANGE FOR RISK: THE HIGHEST EVER ISSUANCE!!
MAY 22 RECORDS THE HIGHEST EVER EXCHANGE FOR RISK AT 12.4416 TONNES. WE HAD OUR FIRST ISSUANCE FOR EXCHANGE FOR RISK IN THE MONTH OF MAY ON MAY 7, THEN OUR 2ND ISSUANCE FOR OUR MAY GOLD MONTH ON MAY 12. THE THIRD ON MAY 18 , THEN MAY 21 OUR 4TH ISSUANCE AND THEN FINALLY FRIDAY, OUR 5TH ISSUANCE. THIS GOLD WILL BE ADDED TO OUR NORMAL MAY DELIVERIES TO GIVE US OUR FINAL AMOUNT OF GOLD WILLING TO STAND AT THE COMEX..
HISTORY OF EXCHANGE FOR RISK ISSUANCE THIS YEAR: FEBRUARY THROUGH JULY AND AUGUST
FEBRUARY:
DURING THE MIDDLE OF THE FEBRUARY CONTRACT MONTH, WE HAD TWO IDENTICAL MONSTER 3,000 CONTRACT ISSUED FOR THE SAME 9.33 TONNES OF GOLD, AND THESE WERE THE HIGHEST EVER IN TONNAGE EVER ISSUED BY THE COMEX. ALTOGETHER THE TOTAL ISSUANCE FOR FEB TOTALLED SIX.(31.251 TONNES).
MARCH:
THURSDAY MARCH 17 WE RECEIVED ITS INITIAL 2000 CONTRACT EXCHANGE FOR RISK ISSUANCE FOR 6.22 TONNES. LAST FRIDAY: 0 ISSUANCE OF EXCHANGE FOR RISK. BUT ON MONDAY MARCH 23 WE RECEIVED NOTICE OF OUR SECOND EXCHANGE FOR RISK ISSUANCE FOR 2,200 CONTRACTS (220,000 OZ OR 6.843 TONNES) AND NOW FRIDAY WITH A MONSTER 2996 CONTRACTS FOR 9.3138 TONNES. THESE THREE ISSUANCES WILL NOW BE ADDED TO THE REGULAR AMOUNT OF GOLD STANDING, I.E. 22.3818 TONNES TO OUR NORMAL GOLD STANDING TO GIVE US WHAT WILL STAND FOR PHYSICAL GOLD FOR MARCH!
APRIL;: 2 EXCHANGE FOR RISK SO FAR, I.E. 2239 CONTRACTS FOR 223,900 OZ OR 6.964 TONNES AND THIS TOTAL TONNES WILL BE ADDED TO OUR NORMAL DELIVERY TO GIVE US WHAT WILL STAND IN APRIL
MAY: FIVE ISSUANCES SO FAR FOR 7920 CONTRACTS OR 792,000 OZ OR 24.635 TONNES.
JUNE: 0 IN GOLD. THUS FOR THE ENTIRE MONTH IN GOLD ZERO NOTICES WERE FILED.
JULY: 2 FOR 200 OZ OR 0.00622 TONNES
AUGUST: 1276 CONTRACTS FOR 127,600 OZ OR 3.9688 TONNES (5 OCCASIONS THIS MONTH)
SEPT: SO FAR: 2000 CONTRACTS FOR 200,000 OZ OR 6.2208 TONNESS (TWO OCCASIONS)
OCT: 0 SO FAR!
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
A LITTLE HISTORY OF EXCHANGE FOR RISK DECEMBER THROUGH TO OCT:
IN DECEMBER WE HAVE RECORDED 5 ISSUANCES OF EXCHANGE FOR RISK/4 FOR DEC AND THE LAST ONE ON DEC 31 FOR JANUARY. WE NOW HAVE 3 CHOICES FOR THE RECIPIENT OF THIS ISSUANCE AND IT MUST BE A CENTRAL BANK. YOU WILL RECALL THAT THE BUYER ASSUMES THE RISK OF THAT DELIVERY. (THUS TOTAL EXCHANGE FOR RISK FOR THE MONTH OF DECEMBER IS 6.56 TONNES/4 OCCASIONS.
MONTH OF JANUARY/EXCHANGE FOR RISK
IN JANUARY THEY HAVE 6 TOTAL ISSUANCE : 3.446 TONNES EARLY, THEN JAN 9 ISSUANCE OF 9,331 TONNES AND THEN JAN 16: 0.1996 TONNES JAN 26: 1.499 TONNES, JAN 27: 3.160 AND FINALLY JAN 29: 4.659 TONNES TONNES//TOTAL EXCHANGE FOR RISK JANUARY 22.315 TONNES WHICH WAS ADDED TO OUR NORMAL DELVERIES.
AND FEBRUARY:
FEB EXCHANGE FOR RISK: NOW 6 ISSUANCES: 10,080 CONTRACTS FOR 1,008,000 OZ OR 31.251 TONNES!
HERE ARE THE CHOICES FOR THE RECIPIENT OF THOSE ISSUANCES:
1 THE CENTRAL BANK OF ENGLAND. BUT THEY RECEIVED CLEARANCE THAT THEIR GOLD IS BACK SO IT IS NOT LIKELY THAT THEY WOULD LIKE TO ADD TO THEIR RESERVES.
2. THE CENTRAL BANK OF THE USA: THE FED. LOGICAL CHOICE AS THEY CLAMOUR TRYING TO REDUCE THEIR 131+ TONNES OF SHORTAGE. HOWEVER THEY SEEM NOT TO BE IN A HURRY TO COVER THEIR HUGE SHORTFALL
3. THE CENTRAL BANK OF CHINA AS THEY BATTLE WITS WITH THE USA.
TOTAL EXCHANGE FOR RISK FOR DECEMBER IS 6.56 TONNES AND THIS WAS ADDED TO OUR NORMAL DELIVERY TOTALS..
THE JANUARY ISSUANCE OF 17.656 TONNES WAS ADDED TO OUR DAILY DELIVERY TOTALS!!
FEBRUARY ISSUANCES 6 FOR; 31.251 TONNES !! AND THIS WAS ADDED TO OUR DELIVERY TOTALS FOR THIS MONTH.
MARCH: CME ANNOUNCES ITS FIRST EXCHANGE FOR RISK FOR 2000 CONTRACTS FOR 200,000 OZ OR 6.22 TONNES OF GOLD DURING THE FIRST WEEK OF MARCH, AND THEN MONDAY, MARCH 22, WE RECEIVED ITS SECOND NOTICE ISSUANCE OF 2200 CONTRACTS OR 220000 OZ (6.843 TONNES). THEN FINALLY WE RECEIVED NOTICE OF OUR THIRD EXCHANGE FOR RISK OF 2996 CONTRACTS OR 9.3188 TONNES. TOGETHER ALL 3 ISSUANCES TOTAL 22.3818 TONNES WHICH WILL BE ADDED TO OUR NORMAL DELIVERY SCHEDULE.
APRIL: 2 EXCHANGE FOR RISK SO FAR FOR 223,900 OZ OR 6.964 TONNES. AND THIS TOTAL WILL BE ADDED TO OUR NORMAL DELIVERY TO GIVE US WHAT WILL STAND FOR APRIL!!
MAY: FIVE ISSUANCES SO FAR FOR 7920 CONTRACTS, 792,000 OZ OR 24.635 TONNES OF GOLD. THIS TOTAL WILL BE ADDED TO OUR NORMAL DELIVERIES IN MAY TO GIVE US WHAT WILL STAND IN MAY.
JUNE: ZERO
JULY 2 FOR 200 OZ OR 0.00622 TONNES. I DOUBT VERY MUCH THAT THIS IS A CENTRAL BANK
AUGUST: 1276 CONTRACTS FOR 127,600 OZ OR 3.9688 TONNES//5 OCCASIONS
SEPT: SO FAR: 2000 CONTRACTS FOR 200,000 OZ OR 6.2208 TONNES/TWO OCCASIONS
OCT: 0 SO FAR
DETAILS ON OUR NEW SEPT COMEX CONTRACT MONTH//
IN TOTAL WE HAD A FAIR GAIN ON OUR TWO EXCHANGES OF 2485 CONTRACTS WITH OUR GAIN IN PRICE (UP $11.75). HOWEVER, OUR FRIENDLY PHYSICAL LONDON BOYS HAD ANOTHER FIELD DAY AGAIN THROUGHOUT THIS WEEK AS THEY WERE READY FOR THE FRBNY.S CONTINUED ORCHESTRATED ATTACKS VERY EARLY IN THE COMEX SESSIONS AS THEY TRIED TO ABSORB EVERYTHING IN SIGHT FROM THEIR DAILY ATTACKS. LONDONERS EXERCISED THEIR BOUGHT CONTRACTS FOR PHYSICAL GOLD VIA THE EXCHANGE FOR PHYSICAL ROUTE AND THANKED THE FRBNY AND OUR SHORT SPECULATORS FOR THEIR THOUGHTFULNESS.
LONDON ANNOUNCED EARLY IN THE YEAR (AND SCARCITY CONTINUES TO THIS DAY) THAT THEY WERE OUT OF GOLD. WRONGLY IT WAS ATTRIBUTED TO THEIR SHIPPING PHYSICAL GOLD TO COMEX FOR STORAGE DUE TO TRUMP’S INITIATION OF TARIFFS. THE TRUTH OF THE MATTER IS THAT THIS GOLD LEFT LONDON TO OTHER CENTRAL BANKS, AND COMEX BANKS HAVE BEEN PAPERING THEIR LOSSES (DERIVATIVE) WITH KILOBAR ENTRIES. BOTH COMEX AND LBMA ARE WITNESSING MASSIVE AMOUNTS OF GOLD LEAVING THEIR VAULTS.
THE LIQUIDATION OF T.A.S. CONTRACTS THROUGHOUT THE MONTHS OF JUNE/JULY/AUG CONTINUES TO DISTORT OPEN INTEREST NUMBERS GREATLY ALTHOUGH THE T.A.S. ISSUANCES IN GOLD HAVE GENERALLY BEEN ON THE LOW SIDE COMPARED TO SILVER WHICH HAVE BEEN HUGE. TODAY’S NUMBER HOWEVER IS A SMALL SIZED T.A.S ISSUANCE CONTRACTS .THE CME NOTIFIES US THAT THEY HAVE ISSUED 962 T.A.S CONTRACTS. THESE ARE GENERALLY USED FOR RAID PURPOSES TO STOP GOLD’S RISE AND TO TEMPER HUGE LOSSES IN OTC DERIVATIVE BETS.
IT SURE LOOKS LIKE THE BIS HAS SOMEHOW LOOKED THE OTHER WAY WITH ITS GOLD SWAPS WITH THE FRBNY AS THIS ENTITY FOR THE FED REFUSES THE BIS MARCHING ORDERS TO COVER AND THAT MAY EXPLAIN THE STRONG NUMBER OF T.A.S. ISSUANCES IN DECEMBER , JANUARY AND THROUGHOUT FEBRUARY TO GO ALONG WITH OUR HUGE NUMBER OF EXCHANGE FOR RISK ISSUED DURING THESE MONTHS INCLUDING FEBRUARY’S 6 EXCHANGE FOR RISK WHICH ALSO INCLUDED TWO MONSTER 9.3312 TONNE ISSUANCE (FEB 10 AND FEB 12). TOTAL EXCHANGE FOR RISK/FEB EQUALS 31.251 TONNES!! AND MARCH’S THREE ISSUANCES FOR 22.3818 TONNES! OTHER CENTRAL BANKS ARE PAYING ATTENTION AS THEY TAKE DELIVERY OF HUGE AMOUNTS OF PHYSICAL GOLD. APRIL HAD 2 EXCHANGE FOR RISK ISSUANCES FOR 6.694 TONNES. AND MAY WITH ITS 5TH ISSUANCE FOR 12.4436 TONNES///TOTAL EXCHANGE FOR RISK FOR MAY: 24.635 TONNES ISSUED MAY 6 ,MAY 12, MAY 18 MAY 21 AND NOW MAY 22..
THEN IT SLOWS DOWN!
JUNE: ZERO FOR THE MONTH
JULY: 2 SO FAR FOR 200 IZ IR 0.00622 TONNES
AUGUST: 1276 CONTRACTS FOR 127,600 OZ OR 3.9688 TONNES
SEPT: 2000 CONTRACTS SO FAR FOR 200,000 OZ OR 6.2208 TONNES (TWO OCCASIONS)
OCT: 0 SO FAR
WE MUST ALSO REMEMBER THAT THE FRBNY IS SHORT 141+ TONNES OF GOLD, THIS COMMENCED ON JAN 2 2023 AS THEY REFUSE TO COVER DESPITE THE BIS’S PLEA TO DO SO.
HERE IS A SUMMARY OF GOLD STANDING FOR DELIVERY ON OUR LAST 16 MONTHS:
1.APRIL AT 209 TONNES
2. AND THIS CONTINUED INTO MAY WITH FINAL STANDING AT 90.23 TONNES.
3. JUNE WHICH IS A HUGE DELIVERY MONTH , FINAL STANDING WAS RECORDED AT A STRONG 93.085 TONNES. //(TOTAL NET QUEUE JUMPING FOR THE JUNE MONTH: 31.027 TONNES.)
4. IN JULY WE HAD HUGE DELIVERY NOTICES ESPECIALLY FOR A NON ACTIVE DELIVERY MONTH WITH INITIAL STANDING AT 17.947 TONNES PLUS MANY QUEUE JUMPS + 3.75 TONNES EX FOR RISK = 41.106 TONNES OF GOLD // FINAL TOTAL TONNES STANDING JULY: 41.106 TONNES
5. FOR THE MONTH OF AUGUST 2025
INITIAL AMOUNT OF GOLD STANDING FOR AUGUST: 60.547 TONNES PLUS THE MONTHS HUGE QUEUE JUMPS OF 47.2312 TONNES +44.696 TONNES EX FOR RISK (7 ISSUANCES) //NEW STANDING 152.208 TONNES WHICH IS MONSTROUS!!!
6. FINAL AMOUNT OF GOLD STANDING FOR SEPT; INITIAL STANDING; 2,602 CONTRACTS OR 260,200 OZ FOR 8.093 TONNES OF GOLD FOLLOWED BY TODAY’S 0.4883 TONNES QUEUE JUMP TO GO ALONG WITH TODAY’S 1.244 TONNES OF EXCHANGE FOR RISK ISSUANCE TODAY AND // TOTAL EXCHANGE FOR RISK ISSUANCE SEPT: 22.923 TONNES//NEW TOTALS STANDING ADVANCES TO 48.801 TONNES OF GOLD!!!
7. OCTOBER:
OCTOBER: INITIAL STANDING FOR GOLD: 90.164 TONNES TO WHICH WE ADD OUR LATEST OCT 30 QUEUE JUMP OF 0.00311 TONNES WHICH FOLLOWS OCT 29 QUEUE JUMP OF .4096 WHICH FOLLOWS; OCT 28 QUEUE JUMP OF .5069 TONNES WHICH FOLLOWS OCT 27 OF 0.3048 TONNES WHICH FOLLOWS: OCT 24 OF 0.8615 TONNES, FOLLOWING OCT 23 QUEUE JUMP OF 1.695 TONNES OCT 22 JUMP OF 8.622 TONNES WHICH FOLLOWS OCT 21: 3.8600 TONNES TO OCT 20 QUEUE JUMP OF 7.695 TONNE
SUMMARY FOR OCTOBER STANDING:
NOVEMBER WHERE INITIAL AMOUNT OF GOLD STANDING IS REGISTERED AT 15.651 TONNES OF GOLD FOLLOWED BY TODAY’S QUEUE JUMP OF 2 TONNES AND FOLLOWED BY ALL OTHER NOV QUEUE JUMPS OF 21.3775 TONNES TO WHICH WE ADD OUR TWO EXCHANGE FOR RISK ISSUANCE FOR 4.5596 TONNES.
/STANDING ADVANCES TO 43.9716 TONNES OF GOLD.
DECEMBER: INITIAL AMOUNT OF GOLD STANDING FOR DELIVERY IN THIS ACTIVE MONTH IS 83.813 TONNES FOLLOWED BY TODAY’S 0.05 TONNES QUEUE JUMP. THIS FOLLOWS ALL OTHER QUEUE JUMPING: 37.163 TONNES//NEW STANDING ADVANCES TO 115.390 TONNES TO WHICH WE ADD OUR FOUR EXCHANGE FOR RISK ISSUANCE OF 6.559 TONNES//NEW STANDING THUS INCREASES TO 121.977 TONNES
JANUARY: INITITAL STANDING: 13.785 TONNES TO WHICH WE ADD OUR QUEUE JUMP OF 0.000 TONNES WHICH FOLLOWS ALL OTHER QUEUE JUMPS OF 30.7117TONNES //NEW TOTAL QUEUE JUMPS 30.7117//NORMAL DELIVERY OF GOLD ADVANCES TO 36.8958 TONNES TO WHICH WE ADD OUR SIX EXCHANGE FOR RISK OF 22.315 TONNES//NEW STANDING ADVANCES TO 59.2108 TONNES.
FEBRUARY: . FEBRUARY: INITIAL STANDING: 93.566 TONNES TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 0.0248 TONNES WHICH MUST BE ADDED ALL OTHER QUEUE JUMPS OF 41.2087 TONNES QUEUE JUMP//TOTAL QUEUE JUMP FOR FEB::ADVANCES TO 41.233 TONNES///STANDING ADVANCES TO 126.628 TONNES TO WHICH WE ADD OUR SIX EXCHANGE FOR RISK OF 31.251 TONNES/NEW STANDING FINALIZES AT 157.879 TONNES, ITS HIGHEST STANDING RECORDED IN OVER 4 YEARS.
MARCH: INITIAL STANDING FOR GOLD: 8.099 TONNES TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 0.2320 TONNES AND THEN WE ADD OUR THREE EXCHANGE FOR RISK OF 22.3818 TONNES////NEW STANDING FOR GOLD ADVANCES TO: 67.6648TONNES WHICH IS ABSOLUTELY HUGE FOR A NON ACTIVE DELIVERY MONTH!!
APRIL 2026: INITIAL STANDING FOR GOLD: 52.20 TONNES FOLLOWED BY TODAY’S SMALL 500 OZ QUEUE JUMP/ TO WHICH WE ADD OUR TWO EXCHANGE FOR RISK ISSUANCES TOTALLING 223,900 OZ OR 6.964 TONNES//STANDING ADVANCES TO 77.726 TONNES WHICH IS ABSOLUTELY HUGE
MAY: INITIAL AMOUNT OF GOLD WILLING TO STAND: 12.24 TONNES OF GOLD TO WHICH WE ADD OUR NEXT HUGE QUEUE JUMP OF 34,500 OZ (1.073 TONNES) TO WHICH WE ADD OUR FIVE EXCHANGE FOR RISK ISSUANCE FOR 792,000 OZ OR 24.635 TONNES////NEW TOTALS STANDING FOR GOLD ADVANCES TO 51.554 TONNESS
JUNE: INITIAL AMOUNT OF GOLD WILLING TO STAND: 64.496 TONNES TO WHICH WE SUBTRACT AN EXCHANGE FOR PHYSICAL TRANSFER TO LONDON OF 0.0186 TONNES//NEW STANDING REDUCES TO 127.03 TONNES// TOTAL QUEUE JUMPING FOR THE MONTH FINALIZES AT 62.4217 TONNES OR AVERAGING 3.285 TONNES PER DAY IN JUNE.
JULY: INITIAL AMOUNT OF GOLD WILLING TO STAND: 749,300 OZ OR 23.306 TONNES OF GOLD TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 0.000TONNES//NEW STANDING REMAINS AT 40.818TONNES PLUS 0.00622 TONNES EXHANGE FOR RISK// NEW TOTAL 40.824 TONNES . TOTAL QUEUE JUMPING SO FAR: 17.5802 TONNES OR 0.8790 TONNES ON EACH TRADING DAY LEAVING COMEX FOR EASTERN SHORES.
AUGUST INITIAL; INITIAL AMOUNT OF GOLD WILLING TO STANDS: 48.687 TONNES TO WHICH WE ADD OUR 5TH EXCHANGE FOR RISK OF 5 CONTRACTS FOR 500 OZ OR 0.0155 TONNES TO OUR 4TH EXCHANGE FOR RISK OF 220 CONTRACTS FOR 20,000 OZ OR 0.6220 TONNES TO OUR 3RD EXCHANGE FOR RISK AT 1.7045 TONNES TO OUR 2ND EXCHANGE FOR RISK AT 1.552 TONNES TO OUR FIRST: 0.0715 NEW TOTAL EXCHANGE FOR RISK = 3.9688 TONNES AND THEN ADD OUR NEXT QUEUE JUMP OF 39 CONTRACTS OR 3900 OZ (0.1213 TONNES)//STANDING, IN TOTAL, THUS ADVANCES HUGELY TO 67.2441 TONNES.
SEPT/2026. INITIAL STANDING : 8.756 TONNES//FOLLOWED BY TODAYS QUEUE JUMP OF 0 OZ OR 0.0000 TONNES TO WHICH WE ADD THIS TO OUR TWO EXCHANGE FOR RISK OF 2,000 CONTRACTS/200,000 OZ OR 6.2208 TONNES: /NEW STANDING ADVANCES TO 19.2316 TONNES
OCT: INITIAL AMOUNT OF GOLD STANDING: 38.345 TONNES!
HERE ARE THE AMOUNTS THAT STOOD FOR DELIVERY IN THE 4 YEARS 2021-2024
DEC 2021: 112.217 TONNES
NOV. 8.074 TONNES
OCT. 57.707 TONNES
SEPT: 11.9160 TONNES
AUGUST: 80.489 TONNES
JULY 7.2814 TONNES
JUNE: 72.289 TONNES
MAY 5.77 TONNES
APRIL 95.331 TONNES
MARCH 30.205 TONNES
FEB ’21. 113.424 TONNES
JAN ’21: 6.500 TONNES.
TOTAL YEAR 2021 (JAN- DEC): 601.213 TONNES
YEAR 2022: STANDING FOR GOLD/COMEX
JANUARY 2022 17.79 TONNES
FEB 2022: 59.023 TONNES
MARCH: 36.678 TONNES
APRIL: 85.340 TONNES FINAL.
MAY: 20.11 TONNES FINAL
JUNE: 74.933 TONNES FINAL
JULY 29.987 TONNES FINAL
AUGUST:104.979 TONNES//FINAL
SEPT. 38.1158 TONNES
OCT: 77.390 TONNES/ FINAL
NOV 27.110 TONNES/FINAL
Dec. 64.000 tonnes
(TOTAL YEAR 656.076 TONNES)
JAN/2023: 20.559 tonnes
FEB 2023: 47.744 tonnes
MAR: 19.0637 TONNES
APRIL: 75.676 tonnes
MAY: 19.094 TONNES + 1.244 tonnes of exchange for risk = 20.338
JUNE: 64.354 TONNES
JULY: 10.2861 TONNES
AUGUST: 38.855 TONNES(INCLUDING .6842 EXCHANGE FOR RISK)
SEPT: 15.281 TONNES FINAL
OCT. 35.869 TONNES + 1.665 EXCHANGE FOR RISK =37.0355 tonnes
NOV: 18.7122 TONNES + 16.2505 EX. FOR RISK = 34.9627 TONNES
DEC. 47.073 + 4.634 TONNES OF EXCHANGE FOR RISK = 51.707 TONNES
TOTAL 2023 YEAR : 436.546 TONNES
2024/STANDING FOR GOLD/COMEX
JAN ’24. 22.706 TONNES
FEB. ’24: 66.276 TONNES (INCLUDES 1.723 TONNES EX. FOR RISK)
MARCH: 18.8398 TONNES + 1.1695 EX FOR RISK = 20.093 TONNES
APRIL: 2024: 53.673TONNES FINAL
MAY/ 2024 8.5536 TONNES + 3.3716 TONNES EX FOR RISK/= 11.9325
JUNE; 95.578 TONNES. + 1.045 TONNES EXCHANGE FOR RISK =96.623 THIS IS THE HIGHEST RECORDED GOLD STANDING SINCE AUGUST 2022
JULY: 11.692 TONNES
AUGUST 69.602 TONNES//FINAL STANDING
SEPT. 13.164 TONNES.
OCT 39.474 TONNES + + 20.917 TONNES EXCHANGE FOR RISK =60.391 TONNES
NOV . 11.265 TONNES +4.665 TONNES EXCHANGE FOR RISK/TUESDAY + 3.11 TONNES OF EX. FOR RISK/PRIOR = 19.0425 TONNES
DEC: 80.4230 TONNES PLUS DEC MONTH EXCHANGE FOR RISK TOTAL 14.6836 TONNES EQUALS 95.1066 TONNES
total year 2024: 540.30 tonnes
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
COMEX GOLD TRADING BEGINNING OCT. CONTRACT;
THE SPECS/HFT WERE UNSUCCESSFUL IN LOWERING GOLD’S PRICE ( IT ROSE BY $11.75).
WE HAD LITTLE T.A.S. SPREADER LIQUIDATION TUESDAY // COMEX SESSION// WITH OUR GAIN IN PRICE.
OTHER EASTERN CENTRAL BANKS TENDERED FOR PHYSICAL EVERY NIGHT WHICH ALSO EXPLAINS THE HUGE NUMBER OF TONNES OF GOLD THAT STOOD FOR GOLD DURING THESE PAST SEVERAL MONTHS
THE CROOKS COULD NOT STOP OTHER CENTRAL BANK LONGS, SEIZING THE MOMENT, THEY EXERCISED AGAIN FOR PHYSICAL IN A BIG WAY TENDERING FOR PHYSICAL TUESDAY EVENING //WEDNESDAY MORNING AND THUS OUR HUGE NUMBER OF GOLD CONTRACTS STANDING FOR DELIVERY AT THE COMEX. CENTRAL BANKERS WAIT PATIENTLY FOR THE GOLD
ALL OF THIS WAS ACCOMPLISHED WITH OUR GAIN IN PRICE AT COMEX OF $11.75
WE HAD 520 CONTRACTS REMOVED // PRELIMINARY NUMBERS TO FINAL COMEX NUMBERS.
NET GAIN ON THE TWO EXCHANGES: 2485 CONTRACTS OR 248,500 OZ 7.72 TONNES
SEPT DELIVERY MONTH
SEPT 30.2026
| Gold | Ounces |
| Withdrawals from Dealers Inventory in oz | nil |
| Withdrawals from Customer Inventory in oz | 1 ENTRIES i) Out of Manfra: 32.151 oz (1 kilobar) total withdrawal: 32.151 oz |
| Deposit to theDealerInventory in oz | 0 ENTRIES |
| Deposits to the Customer Inventory, in oz | DEPOSITS/CUSTOMER//gold 1 ENTRIES I) INTO ASAHI: 32,011.272 OZ TOTAL DEPOSIT; 32,011.272 oz xxxxxxxxxxxxxxxx |
| No of oz served (contracts) today | 10,247 CONTRACTS 1,024,700 OZ 31.872 TONNES OF GOLD |
| No of oz to be served (notices) | 2081 Contracts 208,100 OZ 6.472 TONNES |
| Total monthly oz gold served (contracts) so far this month | 10,247 notices 1,024M700 OZ 31.872 TONNES |
| Total accumulative withdrawals of gold from the Dealers inventory this month | NIL oz |
| Total accumulative withdrawal of gold from the Customer inventory this month |
dealer deposits: 0
xxxxxxxxxxxxxxxxxxx
DEPOSITS:
ENTRIES: 1
I) INTO ASAHI: 32,011.272 OZ
TOTAL DEPOSIT; 32,011.272 oz
xxxxxxxxxxxxxxxxxx
comex withdrawal
1 ENTRIES
i) Out of Manfra: 32.151 oz (1 kilobar)
total withdrawal: 32.151 oz
adjustments: 2
customer account to dealer acct
a) Manfra: 10,290.600 oz
b) JPMorgan 15,092.859 oz
COMEX IS DRAINING GOLD
chaos inside the comex
THE FRONT MONTH OF SEPT OI STANDS AT 12,328 CONTRACTS HAVING A LOSS OF 3347 CONTRACTS.
THUS BY DEFINITION, THE INITIAL AMOUNT OF GOLD WILLING TO STAND AT THE COMEX IS AS FOLLOWS:
12,328 CONTRACTS X 100 OZ PER CONTRACT
EQUALS
1,232800 OZ OR 38.345 TONNES OF GOLD WHICH IS HUGE FOR AN OCTOBER.
NOVEMBER GAINED 2108 CONTRACTS RISING TO 3954
DECEMBER, THE LARGEST DELIVERY MONTH IN THE CALENDAR RISES BY 1272 CONTRACTS UP TO 325,931.
.
We had 10,247 contracts filed for today representing 1,024,700 oz
Today, 0 notice(s) were issued from J.P.Morgan dealer and 6220 notices issued from their client or customer account. The total of all issuance by all participants equate to 10,247 contract(s) of which 0 notices were stopped (received) by j.P. Morgan dealer and 7273 notice(s) was (were) stopped (received) by J.P.Morgan//customer account
To calculate the INITIAL total number of gold ounces standing for OCT /2026. contract month, we take the total number of notices filed so far for the month (10,247) to which we add the difference between the open interest for the front month of OCT (12,328 CONTRACTS) minus the number of notices served upon today 10,247 x 100 oz per contract) equals 1,232,800 OZ OR(38.345 Tonnes of gold)
THUS: INITIAL total number of gold ounces standing for OCT. /2026. contract month,we take the total number of notices filed so far for the month (10,247) to which we add the difference between the open interest for the front month of SEPT(12,328) contracts minus the number of notices served upon today 10,247 x 100 oz per contract) equals 1,232,800 OZ OR(38.345 Tonnes of gold)
new total of gold standing in OCT becomes 38.345 TONNES//
TOTAL COMEX GOLD STANDING FOR SEPT.: 38.345 TONNES WHICH IS NOW VERY STRONG FOR THIS NON ACTIVE DELIVERY MONTH OF OCT
confirmed volume TUESDAY confirmed 171,622/ poor/
COMEX GOLD INVENTORIES/CLASSIFICATION
NEW PLEDGED GOLD:
241,794.285 oz NOW PLEDGED /HSBC 5.94 TONNES
204,937.290 OZ PLEDGED MANFRA 3.08 TONNES
83,657.582 PLEDGED JPMorgan no 1 1.690 tonnes
265,999.054, oz JPM No 2
1,152,376.639 oz pledged Brinks/
Manfra: 33,758.550 oz
Delaware: 193.721 oz
International Delaware:: 11,188.542 oz
total pledged gold: 1,721,684.952 oz 53.55 tonnes pledged gold lowers
total inventories in gold declining rapidly
total pledged gold: 1,721,684.952 tonnes oz 53.55 tonnes
TOTAL OF ALL GOLD ELIGIBLE AND REGISTERED GOLD 23,439,258.332 oz//
TOTAL REGISTERED GOLD 15,138,204.297 tonnes (470.86 tonnes)
TOTAL OF ALL ELIGIBLE GOLD 8,301,054.035 oz.
REGISTERED GOLD THAT CAN BE SERVED UPON 13,416,520 oz ((REG GOLD- PLEDGED GOLD)=
417.310 Tonnes //
total inventories in gold declining rapidly
SILVER COMEX
SEPT DELIVERY MONTH
SEPT 30
| Silver | Ounces |
| Withdrawals from Dealers Inventory | NIL oz |
| Withdrawals from Customer Inventory | 3 entries i) Out of Brinks: 1,199,915.02 oz ii) Out of CNT; 600,111.985 oz iii) Out of Delaware 1002.000 oz total withdrawal 1,800,929.005 OZ |
| Deposits to the Dealer Inventory | 1 ENTRY i) Into Asahi: 599,439.410 oz total deposit to dealer; 599,439.410 oz |
| Deposits to the Customer Inventory | ENTRIES: 2 i) Into Asahi: 600,828.04 oz ii) Into Delaware: 2027.00 oz total deposit: 602,855.040 oz |
| No of oz served today (contracts) | 1957 CONTRACT(S) ( 9.785 MILLION OZ) |
| No of oz to be served (notices) | 1314 Contracts (6.570 MILLION oz) |
| Total monthly oz silver served (contracts) | 1957 contracts 9.785 MILLIONoz |
| Total accumulative withdrawal of silver from the Dealers inventory this month | NIL oz |
| Total accumulative withdrawal of silver from the Customer inventory this month |
DEPOSITS INTO DEALER ACCOUNTS
ENTRY:1
i) Into Asahi: 599,439.410 oz
total deposit to dealer; 599,439.410 oz
DEPOSIT ENTRIES/CUSTOMER ACCOUNT
2 ENTRIES:
i) Into Asahi: 600,828.04 oz
ii) Into Delaware: 2027.00 oz
total deposit: 602,855.040 oz
xxxxxxxxxxxxxxxxxxxxxxxxx
withdrawals:
3 entries
i) Out of Brinks: 1,199,915.02 oz
ii) Out of CNT; 600,111.985 oz
iii) Out of Delaware 1002.000 oz
total withdrawal 1,800,929.005 OZ
adjustments : 3 all customer to dealer:
a) Asahi: 2,963.085.250
b) : CNT: 604,294.615 oz
c) JPMORGAN : 601,368.500 oz
xxxxxxxxxxxxxx
TOTAL REGISTERED SILVER: 101.560 MILLION OZ//.TOTAL REG + ELIGIBLE. 335.307 Million oz
registered silver dropping in numbers
CALCULATIONS FOR THE NEW STANDING FOR SILVER FOR SEPT
FRONT MONTH: SILVER OPEN INTEREST CONTRACTS: 3271 FOR A LOSS OF 8 CONTRACTS.
THUS BE DEFINITION THE INITIAL AMOUNT OF SILVER WILLING TO STAND AT THE COMEX IS AS FOLLOWS:
3271 CONTRACTS X 5000 OZ PER CONTRACT
EQUALS
16,355 MILLION OZ WHICH IS HUGE FOR A NON ACTIVE DELIVERY MONTH!!
NOVEMBER LOST 6 CONTRACTS UP TO AN OI OF 984
DECEMBER LOST 179 CONTRACTS DOWN TO AN OI OF 85,471
TOTAL NUMBER OF NOTICES FILED FOR TODAY: 1957 or 9.785 MILLION oz
CONFIRMED volume TUESDAY;44,392 // poor/
AND NOW OCT. DELIVERIES:
To calculate the number of silver ounces that will stand for delivery in OCT. we take the total number of notices filed for the month so far at 1957 X5,000 oz = 9.785 MILLION oz.
Then we take the difference between the front month of OCT. and the number of notices filed for today x 5000 to give us our standing
Thus the standings for silver for the OCT 2026 contract month: (1957 )Notices served so far) x 5000 oz + OI for the front month of OCT (3271) minus number of notices served upon today ( 1957 x 5000 oz) equals silver standing for the SEPT .contract month equating to 16.355 MILLION OZ. ( a very strong delivery month)
We must also keep in mind that there is considerable silver standing in London coming from our longs
There are ONLY 101.560 million oz of registered silver
JPMorgan as a percentage of total silver: 132.672/335.307million: 39.56%
The record level of silver open interest is 234,787 contracts set on April 21./2017 with the price on that day at $18.42.
The previous record was 224,540 contracts with the price at that time of $20.44.
BOTH GLD AND SLV ARE MASSIVE FRAUD
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
SEPT 30//2026/WITH GOLD UP $7.80 /HUGE CHANGES IN GOLD AT THE GLD:: A EPOSIT OF 2.847 TONNES OF GOLD INTO THE GLD// //:/INVENTORY RESTS AT 1057.407 TONNES
SEPT 29//2026/WITH GOLD UP $11.75 /NO CHANGES IN GOLD AT THE GLD //:/INVENTORY RESTS AT 1054.56 TONNES
SEPT 28//2026/WITH GOLD DOWN $150.20 /NO CHANGES IN GOLD AT THE GLD //:/INVENTORY RESTS AT 1054.56 TONNES
SEPT 25//2026/WITH GOLD DOWN $150.20 /NO CHANGES IN GOLD AT THE GLD //:/INVENTORY RESTS AT 1054.56 TONNES
SEPT 24//2026/WITH GOLD DOWN $18.70 /HUGE CHANGES IN GOLD AT THE GLD A DEPOSIT OF 1.43 TONNES OF GOLD INTO THE GLD://:/INVENTORY RESTS AT 1056.84 TONNES
SEPT 23//2026/WITH GOLD DOWN $58.00 /HUGE CHANGES IN GOLD AT THE GLD://:/INVENTORY RESTS AT 1055.41 TONNES
SEPT 22//2026/WITH GOLD DOWN $6.30 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 0.31 TONNES OF GOLD INTO THE GLD/:/INVENTORY RESTS AT 1055.41 TONNES
SEPT 21//2026/WITH GOLD DOWN $41.20 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 2.26 TONNES OF GOLD INTO THE GLD/:/INVENTORY RESTS AT 1055.10 TONNES
SEPT 18//2026/WITH GOLD UP $26.45 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 0.85 TONNES OF GOLD INTO THE GLD/:/INVENTORY RESTS AT 1052.84 TONNES
SEPT 17//2026/WITH GOLD UP $14.05 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 1.71 TONNES OF GOLD INOT THE GLD/:/INVENTORY RESTS AT 1051.99 TONNES
SEPT 16//2026/WITH GOLD UP $53.40 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 2.86 TONNES OF GOLD INOT THE GLD/:/INVENTORY RESTS AT 1050.28 TONNES
SEPT 15//2026/WITH GOLD DOWN $19.45 /NO CHANGES IN GOLD AT THE GLD://A WITHDRAWAL OF 0.353 TONNES OF GOLD FROM THE GLD/:/INVENTORY RESTS AT 1047.420 TONNES
SEPT 14//2026/WITH GOLD DOWN $54.50 /SMALL CHANGES IN GOLD AT THE GLD://A WITHDRAWAL OF 0.353 TONNES OF GOLD FROM THE GLD/:/INVENTORY RESTS AT 1047.420 TONNES
SEPT 11//2026/WITH GOLD UP $1.05 /SMALL CHANGES IN GOLD AT THE GLD://A WITHDRAWAL OF 0.353 TONNES OF GOLD FROM THE GLD/:/INVENTORY RESTS AT 1050.277 TONNES
/SEPT 10//2026/WITH GOLD UP $50.60 /NO CHANGES IN GOLD AT THE GLD://:/INVENTORY RESTS AT 1050.63 TONNES
SEPT 9//2026/WITH GOLD UP $20.40 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 1.43 TONNES OF GOLD OUT OF THE GLD/ ////:/INVENTORY RESTS AT 1050.63 TONNES
SEPT 8//2026/WITH GOLD DOWN $34.20 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 1.42 TONNES OF GOLD OUT OF THE GLD/ ////:/INVENTORY RESTS AT 1052.06 TONNES
SEPT 4//2026/WITH GOLD DOWN $63.50 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 3.14 TONNES OF GOLD OUT OF THE GLD/ ////:/INVENTORY RESTS AT 1053.48 TONNES
SEPT 3//2026/WITH GOLD UP $141.55 /HUGE CHANGES IN GOLD AT THE GLD:A DEPOSIT OF 9.98 TONNES OF GOLD INTO THE GLD/ ////:/INVENTORY RESTS AT 1056.62 TONNES
SEPT 2//2026/WITH GOLD UP $19.25 /HUGE CHANGES IN GOLD AT THE GLD:A DEPOSIT OF 4.28 TONNES OF GOLD INTO THE GLD/ ////:/INVENTORY RESTS AT 1046.64 TONNES
SEPT 1//2026/WITH GOLD DOWN $80.25 /NO CHANGES IN GOLD AT THE GLD:// ////:/INVENTORY RESTS AT 1042.36 TONNES
AUGUST 31//2026/WITH GOLD DOWN $48.20 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 4.25 TONNES OF GOLD FROM THE GLD// ////:/INVENTORY RESTS AT 1042.36 TONNES
AUGUST 28//2026/WITH GOLD DOWN $119.00 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 1.71 TONNES OF GOLD FROM THE GLD// ////:/INVENTORY RESTS AT 1046.64 TONNES
AUGUST 27//2026/WITH GOLD UP $11.35 /NO CHANGES IN GOLD AT THE GLD: ////:/INVENTORY RESTS AT 1048.950 TONNES
AUGUST 26//2026/WITH GOLD DOWN $75.35 /HUGE CHANGES IN GOLD AT THE GLD: // A STRONG WITHDRAWAL OF 1/138 TONNES OF GOLD OUT OF THE GLD//:/INVENTORY RESTS AT 1048.950 TONNES
AUGUST 25//2026/WITH GOLD FLAT /HUGE CHANGES IN GOLD AT THE GLD: // A STRONG DEPOSIT OF 2.279 TONNES OF GOLD INTO THE GLD//:/INVENTORY RESTS AT 1049.489 TONNES
AUGUST 24//2026/WITH GOLD UP $15.30 /HUGE CHANGES IN GOLD AT THE GLD: // A MASSIVE DEPOSIT OF 12.50 TONNES OF GOLD INTO THE GLD//:/INVENTORY RESTS AT 1047.21 TONNES
AUGUST 21//2026/WITH GOLD UP $103.98 /NO CHANGES IN GOLD AT THE GLD: //:/INVENTORY RESTS AT 1034.65 TONNES
AUGUST 20//2026/WITH GOLD UP $29.30 /HUGE CHANGES IN GOLD AT THE GLD: A MASSIVE DEPOSIT OF 9.41 TONNES OF GOLD INTO THE GLD: //:/INVENTORY RESTS AT 1034.65 TONNES
AUGUST 19//2026/WITH GOLD UP $123.70 /HUGE CHANGES IN GOLD AT THE GLD: A MASSIVE WITHDRAWAL OF 5.42 TONNES OF GOLD OUT OF THE GLD: //:/INVENTORY RESTS AT 1025.24 TONNES
AUGUST 18//2026/WITH GOLD DOWN $51.50 /HUGE CHANGES IN GOLD AT THE GLD: A MASSIVE DEPOSIT OF 7.13 TONNES OF GOLD INTO THE GLD: //:/INVENTORY RESTS AT 1030.66 TONNES
AUGUST 17//2026/WITH GOLD UP $36.70 /HUGE CHANGES IN GOLD AT THE GLD: A WITHDRAWAL OF 2.28 TONNES OF GOLD FORM THE GLD: //:/INVENTORY RESTS AT 1023.53 TONNES
AUGUST 14//2026/WITH GOLD UP $16.55 /NO CHANGES IN GOLD AT THE GLD: : //:/INVENTORY RESTS AT 1025.80 TONNES
AUGUST 13//2026/WITH GOLD DOWN $43.05 /HUGE CHANGES IN GOLD AT THE GLD: A DEPOSIT OF 3,139 TONNES OF GOLD INTO THE GLD. : //:/INVENTORY RESTS AT 1025,80TONNES
AUGUST 12//2026/WITH GOLD UP $24.55 /HUGE CHANGES IN GOLD AT THE GLD: A DEPOSIT OF 2.562 TONNES OF GOLD INTO THE GLD. : //:/INVENTORY RESTS AT 1022.672TONNES
AUGUST 11//2026/WITH GOLD UP $20.25 /HUGE CHANGES IN GOLD AT THE GLD: A DEPOSIT OF 2.52 TONNES OF GOLD INTO THE GLD. : //:/INVENTORY RESTS AT 1020.06TONNES
AUGUST 10//2026/WITH GOLD UP $22.00 /HUGE CHANGES IN GOLD AT THE GLD: A DEPOSIT OF 2.82 TONNES OF GOLD INTO THE GLD. : //:/INVENTORY RESTS AT 1017. 540TONNES
/AUGUST 7//2026/WITH GOLD UP $98.00 /HUGE CHANGES IN GOLD AT THE GLD: A DEPOSIT OF 0.57 TONNES OF GOLD INTO THE GLD. : //:/INVENTORY RESTS AT 1014.720TONNES
AUGUST 6//2026/WITH GOLD DOWN $2.45 /HUGE CHANGES IN GOLD AT THE GLD: A DEPOSIT OF 4.851 TONNES OF GOLD FROM THE GLD. : //:/INVENTORY RESTS AT 1014.143TONNES
GLD INVENTORY: 1057.407 TONNES, TONIGHTS TOTAL GOLD INVENTORY
SILVER
SEPT 30 WITH SILVER DOWN $0.55 : :HUGE CHANGES IN INVENTORY AT THE SLV: A DEPOSIT OF 994,000 OZ INTO THE SLV// :INVENTORY RESTS AT 494.978 MILLION OZ
SEPT 29 WITH SILVER DOWN $0.58 : :SMALL CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 566,000 OZ FROM THE SLV// :INVENTORY RESTS AT 493.984 MILLION OZ
SEPT 28 WITH SILVER DOWN $2.91 : :SMALL CHANGES IN INVENTORY AT THE SLV: A DEPOSIT OF 0.542 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 494.436 MILLION OZ
SEPT 25 WITH SILVER DOWN $2.91 : :SMALL CHANGES IN INVENTORY AT THE SLV: A DEPOSIT OF 0.542 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 494.436 MILLION OZ
SEPT 24 WITH SILVER DOWN $0.96 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 0.813 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 493.533 MILLION OZ
SEPT 23 WITH SILVER UP $1.58 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 1.716 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 494.346 MILLION OZ
SEPT 22 WITH SILVER UP $0.10 : :NO CHANGES IN INVENTORY AT THE SLV: :INVENTORY RESTS AT 496.062 MILLION OZ
SEPT 21 WITH SILVER UP $1.04 : :HUGE CHANGES IN INVENTORY AT THE SLV: :INVENTORY RESTS AT 489.558 MILLION OZ
SEPT 18 WITH SILVER UP $1.04 : :NO CHANGES IN INVENTORY AT THE SLV: :INVENTORY RESTS AT 489.558 MILLION OZ
SEPT 17 WITH SILVER UP $1.10 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 1.265 MILLION OZ FROM THE SLV/ :INVENTORY RESTS AT 489.558 MILLION OZ
SEPT 16 WITH SILVER UP $0.95 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 813,000 OZ FROM THE SLV/ :INVENTORY RESTS AT 490.823 MILLION OZ
SEPT 15 WITH SILVER DOWN $0.16 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 813,000 OZ FROM THE SLV/ :INVENTORY RESTS AT 491.636 MILLION OZ
SEPT 14 WITH SILVER DOWN $0.91 : :NO CHANGES IN INVENTORY AT THE SLV:/ :INVENTORY RESTS AT 492.449 MILLION OZ
SEPT 11 WITH SILVER DOWN $3.50 : :NO CHANGES IN INVENTORY AT THE SLV:/ :INVENTORY RESTS AT 492.449 MILLION OZ
SEPT 10 WITH SILVER DOWN $3.50 : :NO CHANGES IN INVENTORY AT THE SLV:// / :INVENTORY RESTS AT 493.171 MILLION OZ
SEPT 9 WITH SILVER UP $0.56 : :NO CHANGES IN INVENTORY AT THE SLV:// / :INVENTORY RESTS AT 493.171 MILLION OZ
SEPT 8 WITH SILVER UP $0.31 : :HUGE CHANGES IN INVENTORY AT THE SLV:/ A DEPOSIT OF 0.632 MILLION OZ INTO THE SLV// / :INVENTORY RESTS AT 493.171 MILLION OZ
SEPT 4 WITH SILVER UP $2.20 : :NO CHANGES IN INVENTORY AT THE SLV:/// / :INVENTORY RESTS AT 492.539 MILLION OZ
SEPT 3 WITH SILVER UP $2.20 : :HUGE CHANGES IN INVENTORY AT THE SLV:A WITHDRAWAL OF 1.293 MILLION OZ FROM THE SLV//// / :INVENTORY RESTS AT 492.539 MILLION OZ
SEPT2 WITH SILVER UP $0.15 : :NO CHANGES IN INVENTORY AT THE SLV:// / :INVENTORY RESTS AT 493.832 MILLION OZ
SEPT1 WITH SILVER DOWN $1.43 : :NO CHANGES IN INVENTORY AT THE SLV:// / :INVENTORY RESTS AT 493.832 MILLION OZ
AUGUST 31 WITH SILVER DOWN $0.97 : :SMALL CHANGES IN INVENTORY AT THE SLV:A DEPOSIT OF 0.452 MILLION OZ INTO THE SLV// / :INVENTORY RESTS AT 493.832 MILLION OZ
AUGUST 28 WITH SILVER DOWN $2.44 : :SMALL CHANGES IN INVENTORY AT THE SLV:A WITHDRAWAL OF 0.543,000 MILLION OZ FROM THE SLV// / :INVENTORY RESTS AT 493.380 MILLION OZ
AUGUST 27 WITH SILVER UP $1.33 : :NO CHANGES IN INVENTORY AT THE SLV: / :INVENTORY RESTS AT 493.923 MILLION OZ
AUGUST 26 WITH SILVER DOWN $0.60 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 1.174 MILLION OZ OUT OF THE SLV / :INVENTORY RESTS AT 493.923 MILLION OZ
AUGUST 25 WITH SILVER UP $0.43 : :HUGE CHANGES IN INVENTORY AT THE SLV: A DEPOSIT OF 3.9786 MILLION OZ INTO THE SLV / :INVENTORY RESTS AT 495.097 MILLION OZ
AUGUST 24 WITH SILVER DOWN $1.08 : :HUGE CHANGES IN INVENTORY AT THE SLV: A DEPOSIT OF 0.633 MILLION OZ INTO THE SLV / :INVENTORY RESTS AT 491.754 MILLION OZ
AUGUST 21 WITH SILVER UP $1.48 : :NO CHANGES IN INVENTORY AT THE SLV. / :INVENTORY RESTS AT 491.121 MILLION OZ
AUGUST 20 WITH SILVER UP $2.92 : :HUGE CHANGES IN INVENTORY AT THE SLV A WITHDRAWAL OF 2.169 MILLION OZ OZ OUT OF THE SLV. / :INVENTORY RESTS AT 491.121 MILLION OZ
AUGUST 19 WITH SILVER UP $1.72 : :HUGE CHANGES IN INVENTORY AT THE SLV A DEPOSIT OF 2.259 MILLION OZ OZ INTO THE SLV. / :INVENTORY RESTS AT 493.290 MILLION OZ
AUGUST 18 WITH SILVER DOWN $2.02 : :SMALL CHANGES IN INVENTORY AT THE SLV A WITHDRAWAL OF 768,000 OZ OUT OF THE SLV. / :INVENTORY RESTS AT 492.296 MILLION OZ
AUGUST 17 WITH SILVER UP $1.11 : :SMALL CHANGES IN INVENTORY AT THE SLV A WITHDRAWAL OF 768,000 OZ OUT OF THE SLV. / :INVENTORY RESTS AT 492.296 MILLION OZ
AUGUST 14 WITH SILVER UP $0.19 : :SMALL CHANGES IN INVENTORY AT THE SLV A DEPOSIT OF 720,000 OZ INTO THE SLV. / :INVENTORY RESTS AT 493.064 MILLION OZ
AUGUST 13 WITH SILVER DOWN $0.92 : :NO CHANGES IN INVENTORY AT THE SLV / :INVENTORY RESTS AT 492.341 MILLION OZ
AUGUST 12 WITH SILVER UP $0.75 : :HUGE CHANGES IN INVENTORY AT THE SLV;A DEPOSIT OF 3.434 MILLION OZ INTO THE SLV / :INVENTORY RESTS AT 492.341 MILLION OZ
AUGUST 11 WITH SILVER DOWN $0.39 : :HUGE CHANGES IN INVENTORY AT THE SLV;A DEPOSIT OF 1.085 MILLION OZ INTO THE SLV / :INVENTORY RESTS AT 488.907 MILLION OZ
AUGUST 10 WITH SILVER UP $1.83 : :NO CHANGES IN INVENTORY AT THE SLV; / :INVENTORY RESTS AT 487.822 MILLION OZ
AUGUST 7 WITH SILVER UP $2.00 : :HUGE CHANGES IN INVENTORY AT THE SLV; A DEPOSIT OF 1.355 MILLION OZ INTO THE SLV : / :INVENTORY RESTS AT 487.822 MILLION OZ
AUGUST 6 WITH SILVER DOWN $0.75 : :NO CHANGES IN INVENTORY AT THE SLV : / :INVENTORY RESTS AT 486.467 MILLION OZ
CLOSING INVENTORY 494.978 MILLION OZ OF SILVER
GOLD COMMENTARIES:
1.PETER SCHIFF//JOHN RUBINO//RAVEN
Fwd: Comex Update: 400oz Gold Contract Cancelled; Silver Demand Strengthens
THE RAVEN…
Comex Update: 400oz Gold Contract Cancelled; Silver Demand Strengthens
The Comex data is where the run on physical metals has been occurring over the last few years.
| Quoth the RavenSep 30 |  |
The CME Comex is the Exchange where futures are traded for gold, silver, and other commodities. The CME also allows futures buyers to turn their contracts into physical metal through delivery. You can find more detail on the CME here (e.g., vault types, major/minor months, delivery explanation, historical data, etc.).
The data below looks at contract delivery where the ownership of physical metal changes hands within CME vaults. It also shows data that details the movement of metal in and out of CME vaults. It is very possible that if there is a run on the dollar, and a flight into gold, this is the data that will show early warning signs.
Gold
We have been tracking this data for years now. Since January of 2025, the market has seen elevated delivery volume far surpassing what had been seen in years past. Then, suddenly activity just stopped. This was the case last month too (which is a major month in gold). Delivery volume this month was half what we had seen in the quietest month since 2024.
It wasn’t a gradual slowdown, it was sudden. As if all of a sudden demand just vanished.

Figure: 1 Recent like-month delivery volume
When looked at from a dollar amount perspective (rather than raw ounces), you can see that this September is larger than 2023 and 2024, but that is mostly attributable to the price gain. Otherwise, the amounts would be the same. Compared to 2022 it is way less in terms of ounces.

Figure: 2 Notional Deliveries
Net new contracts (contracts that open and settle for immediate delivery) are at the lowest level in two years.

Figure: 3 Cumulative Net New Contracts
Here is the more interesting chart of the group. During the gold delivery surge that occurred in 2020, the Comex needed to add metal fast. To accomplish this, they opened up a 400-ounce contract and brought on vaults holding 400-ounce bars which are the London LBMA standard. This was done to give confidence to the market in a period of stress.

Figure: 4 Inventory Data
Looking ahead to the October delivery period (a mid-level month for gold), we see a contract that is well below average, near the bottom of the range as the roll date approaches.

Figure: 5 Open Interest Countdown
Even on a relative basis, the demand is looking rather weak.

Figure: 6 Open Interest Countdown Percent
Bottom line, delivery volumes have fallen and the exodus of gold from Comex vaults has paused. The massive outflow seen this month is a simple change to the Comex inventory process and not an actual drop in physical metal inventories.
Silver
Silver price spreads have inverted again, albeit only for a short period so far.

Figure: 7 Spot vs Futures
Silver delivery volumes have also dropped, but not as severely as gold.

Figure: 8 Recent like-month delivery volume
Notional delivery volume is still very high in silver but this is mostly due to the price increase in silver.

Figure: 9 Notional Deliveries
Silver net new contracts were middle of the pack this month after they were non-existent last month.

Figure: 10 Cumulative Net New Contracts
Silver inventory has been on a bit of a roller coaster. After a big drawdown in 2025 and early 2026, the exodus stopped on a dime. Then there was metal added back in but the most recent move has been another exit.

Figure: 11 Inventory Data
Registered metal shows the same thing as Eligible, an increase over several weeks followed by a recent down move.

Figure: 12 Inventory Data
As we approach October delivery (minor silver month), the silver contract is actually quite strong.

Figure: 13 Open Interest Countdown
On a relative basis, it’s the highest in recent periods.

Figure: 14 Open Interest Countdown Percent
Conclusion
The Comex data is where the run on physical metals has been occurring over the last few years. Right now, data shows that demand for gold has evaporated where demand for silver has firmed. The removal of the 400-ounce bars from the inventory tells you something else though. When the market was stretched, the Comex did whatever they could to give the appearance of calm. With the 400 ounce now cancelled, if inventory were to come under pressure again, the Comex may find their vaults getting drained quite quickly.
The immediate and sudden collapse in physical demand for gold is something worth watching, especially since the same thing is not playing out in silver. It will be interesting to see how this plays out. It might be that the new Asian markets are attracting all the action. If this is the case, it would break the control Comex has over the gold market and likely lead to much higher prices sooner rather than later.

1 B // JAMES RICKARDS
2. ALASDAIR MACLEOD
The paper market swindle
We are led to believe that price reflects supply and demand. What if the relationship between paper and physical is just a delusion?
The origin of today’s paper markets
In the mid-1980s a regulatory event occurred in London that was termed Big-Bang. Banks moved into securities markets buying brokers and jobbers: Brokers advised investors and managed their portfolios, while jobbers are known today as market makers. The reason that London was the epicentre of this change and not New York is that US banks were still constrained by the Glass Stegall Act which separated commercial from investment banking. This restricted investment banking and stock market trading activities in New York, but the big US commercial banks were free to do so in London.
Futures and options activities boomed both in regulated exchanges and unregulated over-the-counter markets. This did two things: It introduced limitless capital into securities trading, and bank credit creation provided the necessary capital. The very thing that Glass Stegall banned in the 1930s, which was the expansion of credit for securities trading putting depositors’ funds at risk, returned in London and gradually gained ground in New York until Glass Stegall was finally repealed.
It radically changed the way securities markets operated. Instead of expanding bank credit out of thin air to lend to businesses, bank credit was created for securities trading. And it brought a paper culture into trading that was fundamentally different from the physical securities and commodity markets that operated before.
It was embraced by the US authorities, who saw it as the means to suppress commodity prices through paper expansion. That would reduce producer and consumer price inflation while the dollar bedded in as gold’s replacement. And with respect to gold, the expansion of paper supply would ensure that the horrors of the 1970s — for the dollar, that is — would not be repeated and gold would be relegated to non-monetary roles.
The current market
Paper markets are just another form of credit. After all, the definition of a bank is that it is a dealer in credit. The last thing a banker wants is to encumber his balance sheet with a physical commodity, because it is an inefficient use of his balance sheet. Consequently, banks run neutral positions by matching paper longs with paper shorts, typically between the LBMA and Comex futures.
When speculator demand enters the paper markets, it is normally crushed by the simple expedient of expanding credit until it runs out of steam, as illustrated by fluctuations in open interest in the Comex futures gold contract:

Normally, letting the speculators run up their long positions to between 600,000 and 650,000 contracts has been enough to neutralise any bullishness. Because the banks control the market, they are assured of substantial profits irrespective of the gold price.
The speculators live in hope that one day they will break the banks. But it will not be them that do so. Gold is the antithesis of dollar credit, and the paper game will stop only when either there’s a wider banking crisis or the dollar’s value as a fiat currency disintegrates. We must therefore assess outside events to determine the prospects for paper markets rather than factors specific to capital markets.
It’s the economy, stupid!
The political catchphrase of the Clinton era seems appropriate to our topic. It has been demonstrated above that to assume the trillions of paper obligations in over-the-counter and regulated markets will be the system’s undoing is not what we should be looking at. Instead, we should focus on the consequences of fiat currencies running out of road.
Fiat currency debasement is the medium governments use to both fund themselves in addition to tax revenues and to manage the private sector. The key to this policy has been to maintain control over expectations, which is the point behind targeting annual consumer price inflation at 2% — a figure achieved with the help of statistical manipulation. But there is always an end to monetary policies of this sort, as a gradual currency debasement is exposed as ultimately unmanageable.
Usually, it is foreign actors who become sceptical at first, demanding higher bond yields and interest rates to maintain their exposure, joined by savvier domestic investors. This is where the US government’s finances and the dollar stand today. International investors are increasingly aware of the outlook for energy, food, and other commodity prices and how they will require higher interest rates and bond yields to maintain the fiat dollar’s value.
This is where economics comes in. Higher bond yields will burst the equity bubble, which is floating on a sea of bank credit taking the S&P 500 index to its most overvalued relative to bonds since London’s big-bang of the mid-1980s:

We’ve shown this chart before. Suffice to say that the double-headed arrow shows equity valuations three times more expensive relative to the long bond than during the dotcom bubble, also arrowed. As to the direction of bond yields, our next chart should cause investors acute alarm:

Taken together, these two charts graphically expose the Fed’s policy problem — it has lost control and credibility with it. The consequence is that the current and further increases in bond yields will lead to a business slump and a collapse in equity markets. As the equity bubble bursts, foreign investors, with over $24 trillion invested, will run for the exit and at the same time banks will be rapidly liquidating leveraged customer positions by selling collateral to protect their balance sheets. It will be a replay of the Wall Street Crash of 1929-32.
This outcome is increasingly inevitable, as will be the joint efforts between the Fed and the US Treasury to stop the economy and state finances from imploding. Their very survival depends on it.
As much as possible, bad debts will be concealed by the expansion of central bank credit. Whether it will be sufficient to protect the entire banking system is an open question. But there can be little doubt that commercial bank credit will contract substantially as risks mount, and that will call time on the paper market swindle.
END
3. CHRIS POWELL AND HIS GATA DISPATCHES
4. ANDREW MAGUIRE//KINESIS LIVE FROM THE VAULT/291
END
5. COMMODITY REPORT: GOLD/USA TREASURIES:
LUKE GROMEN TO US ALL (EMAIL FROM ROBERT LAMBOURNE TO US ALL)
Luke Gromen on X: “Cut rates to zero, cut interest on bank reserves to zero, buy back some of the debt with 0% T-Bills, let gold moon, instruct Warsh to revalue official gold to the new much higher price, depositing multiple trillions into the TGA, use the TGA to buy back to rest of the debt, voila” / X
Inbox
Summarize this email

| Robert Lambourne | 5:15 AM (28 minutes ago) | ||
to Chris, me | |||
Chris and Harvey,
I got this link overnight.
It looks like a form of gold price reset to me. If I’ve understood him properly zero interest T bills are to be issued – presumably somebody has to be forced to buy them – and gold revalued upwards so that all of the Federal government debt is repaid by these two measures.
Depending on how many zero rate T bills can be forced onto savers, this looks like gold going to over $100,000 per Troy ounce. Possibly going to c$150,000 if there are no takers for zero rate T bills.
As an aside, I believe that in his published output Luke Gromen has never accepted that gold price suppression really happens.
Interesting times!
Bob
| Cut rates to zero, cut interest on bank reserves to zero, buy back some of the debt with 0% T-Bills, let gold moon, instruct Warsh to revalue official gold to the new much higher price, depositing multiple trillions into the TGA, use the TGA to buy back to rest of the debt, voila |
LUKE GROMEN; PROFILE AI:
Luke Gromen is an American macroeconomic analyst, investor, and founder/president of Forest for the Trees (FFTT, LLC), an independent research firm focused on global monetary systems, sovereign debt, geopolitics, gold, energy, and investment strategy.
tftc.io
He is best known for arguing that the post-1971 U.S. dollar system is ending, that gold has (or is) replacing U.S. Treasuries as the world’s primary reserve asset, and for analyzing fiscal dominance, debt sustainability (e.g., high U.S. debt-to-GDP levels historically leading to inflation), liquidity dynamics, and related themes. He frequently discusses implications for gold, bonds, equities, commodities, and assets like Bitcoin, and has appeared often on podcasts and YouTube channels (including MacroVoices, TFTC, Thoughtful Money, and others).
tradersunion.com
Background and Career
- Gromen spent about 18 years in institutional equity research and sales before launching FFTT in 2014. He was a partner at Midwest Research (roughly 1996–2006; involved in equity research/sales and editing thematic summaries like “Heard in the Midwest”) and a founding partner at Cleveland Research Company (2006–2014; research sales and editing the firm’s flagship weekly “Straight from the Source”). tftc.io
- He founded FFTT to “connect the dots” across siloed Wall Street and corporate perspectives, aggregating macroeconomic, thematic, and sector trends to identify investable bottlenecks for institutional clients and sophisticated individual investors. FFTT’s offerings include institutional research and the subscription product Tree Rings (with a weekly letter often called “View from the Treetops”). macrovoices.com
- He is the author of The Mr. X Interviews (Volumes I and II).
Education and Personal DetailsHe holds a BBA in Finance and Accounting from the University of Cincinnati, an MBA from Case Western Reserve University, and the CFA designation (earned in 2003). He is based in the U.S. (associated with the Cleveland area), married to Tracy Gromen, and has three children.
tradersunion.comOnline Presence
- Website: fftt-llc.com (and related Tree Rings site)
- X/Twitter: @LukeGromen
- He is active in media discussions on topics like U.S. fiscal challenges, potential shifts in the global reserve system, gold’s role, AI’s impact on bonds/tax bases, energy, and investment positioning (often emphasizing gold allocation, reduced leverage, and select infrastructure/industrial opportunities).
In short, he is a respected independent macro voice whose research emphasizes structural, long-term shifts in the dollar-centric system and related investment implications.
END
this is big if this continues: South Korea has over 400 billion in USA reserves
(zerohedge)
Bank of Korea To Buy 1 Ton Of Gold In First Purchase Since 2013
Wednesday, Sep 30, 2026 – 11:40 AM
Add South Korea to the list of countries taking tentative steps to hedge their exposure to the US dollar, and fiat in general.
The Bank of Korea will buy approximately one ton of domestically produced gold in December, worth 200 billion won, according to the office of Rep. Chung Tae-ho of the Democratic Party of Korea, a member of the National Assembly’s Strategy and Finance Committee, on the 30th.
The move, which follows indirect investment through ETFs in the second quarter, signals a more active push into gold and marks the central bank’s first physical gold purchase in 13 years. The first transaction is scheduled for December 14, after the bank establishes the system needed for domestic gold trading, Seoul Daily reported.
In materials submitted to Chung’s office, the BOK said the necessary systems are expected to be in place around Dec. 14, allowing the first transaction to take place at that time. The central bank estimated the planned volume at around one ton. One ton of gold is valued at roughly 200 billion won ($140 million).
The Bank of Korea held 104.4 tons of physical gold as of the end of August, valued at $14.88 billion and representing 3.4% of foreign exchange reserves. One ton adds less than 1% to that position.
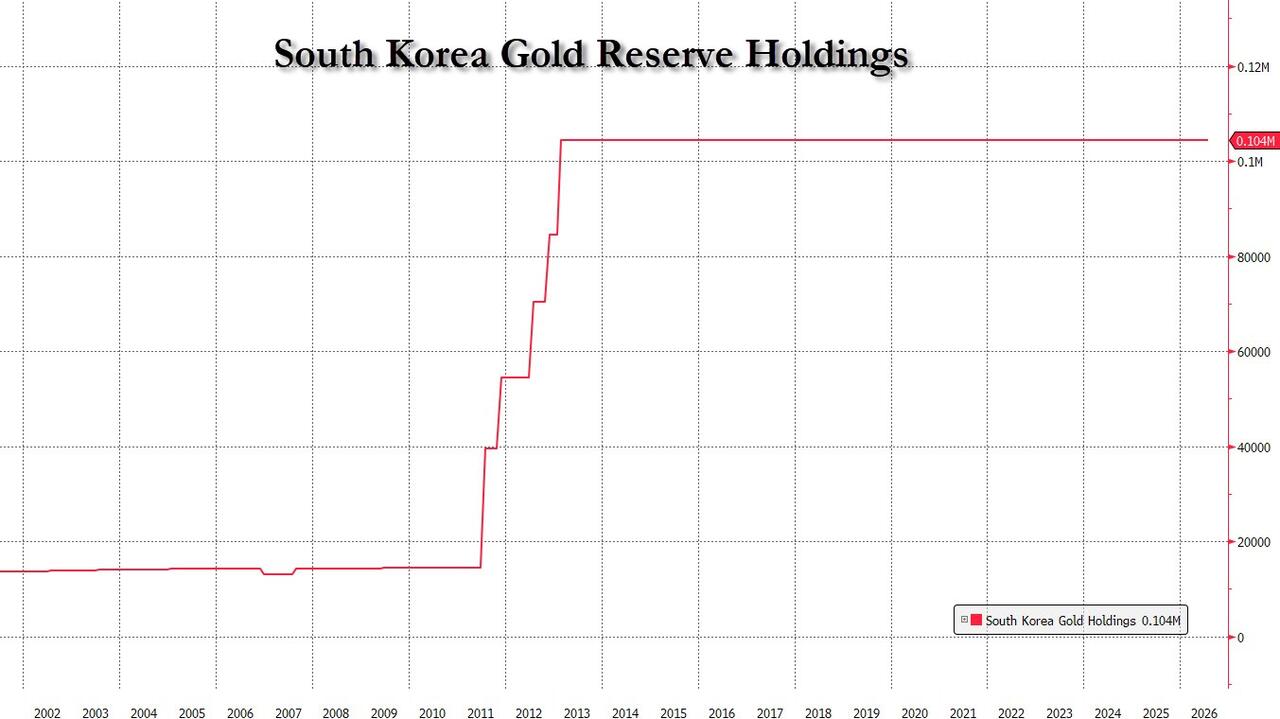
The BOK halted gold purchases in February 2013. It had ramped up gold investment until then, only to face fierce criticism from politicians when prices fell. But with geopolitical risks mounting and interest in gold as a safe-haven asset growing, and amid criticism that the BOK’s gold holdings were smaller than those of other central banks, the bank decided this year to expand its reserves. It officially announced in August that it would resume buying physical gold. In the second quarter, it had already purchased $250 million worth of gold ETFs, which are classified as securities.
The most likely approach for the physical purchases is to buy volumes that domestic gold producers had planned to export. The arrangement is significant because it secures a channel for buying gold in won rather than foreign currency. That allows the BOK to build up safe-haven assets without dollar outflows, minimizing volatility in the domestic foreign exchange market. The Korea Exchange recently overhauled the trading, custody and settlement systems of its KRX gold market to support the BOK’s purchases.
Chung said the BOK’s decision to resume physical gold purchases after 13 years is a meaningful first step toward diversifying the country’s foreign exchange reserve portfolio.
What makes the purchase notable is the resumption itself. As Binance notes, a central bank that has not bought physical gold since 2013 building the infrastructure to do so signals an intent to continue, and the report describes establishing a system rather than executing a one-off trade.
Confirming an August report from Reuters, the purchase is expected to cover gold that domestic producers had originally planned to export. That will allow the central bank to pay in Korean won without drawing on foreign exchange reserves.
The distinction matters for how the transaction affects Korea’s external position. A conventional gold purchase converts foreign currency into bullion, changing the composition of reserves without altering their total. Buying domestic production with won adds to reserves without spending any.
It also keeps gold inside Korea that would otherwise have left, which has a marginal effect on the country’s trade flows.
The Bank of Korea began indirect gold investment in the second quarter of this year, purchasing $250 million worth of gold ETFs.
That sequence is informative. ETF exposure gives price participation without custody, storage or the operational work of handling physical metal. Moving from ETFs to bullion after two quarters suggests the earlier position was a preliminary step rather than the intended endpoint.
The BOK’s gold holdings fall far short of those in major economies. As of the end of August, the central bank held 104.4 tons of physical gold, worth $4.79 billion on a book value basis. That accounts for just 1.1% of total foreign exchange reserves, or about 3.4% at market prices. The BOK ranks 39th in the world in gold holdings, according to the latest data from the World Gold Council.
China’s central bank has been the more visible buyer, adding 650,000 ounces in a recent month – its largest since 2023 – across 22 consecutive months of purchases.
Central bank gold demand has been a persistent bid through a period when the metal has fallen sharply on rate expectations. Gold traded near $4,144 on September 28, roughly 25% below January’s record of $5,600, and posted three consecutive weekly declines through mid-September.
That divergence is the thing to watch. Official sector buying has continued while investor flows moved the other way, and a central bank starting a programme at these levels is buying into weakness rather than strength.
Fiscal Concerns Are the Stated Driver Elsewhere
The broader argument for central bank gold accumulation has shifted toward sovereign risk.
Chicago-based Strategic Analytics put it directly: “Since 2022, gold has increasingly tracked fiscal-risk perceptions – term premium, deficits, debt sustainability – rather than the Fed’s policy path.”
That framing sits alongside a bond market setting extremes. The 30-year Treasury yield crossed 5.6% on Tuesday, its highest since June 2002, and the 10-year reached a fresh 2007 high near 5.3%, with analysts including 10x Research’s Markus Thielen forecasting 6%.
END
YOUR EARLY CURRENCY VALUES/GOLD AND SILVER PRICING/ASIAN AND EUROPEAN BOURSE MOVEMENTS/AND INTEREST RATE SETTINGS WEDNESDAY MORNING.7:30 AM
SHANGHAI CLOSED UP 11.74 PTS OR 0.31%
HANG SENG CLOSED UP 89.70 PTS OR 0.37%
Nikkei CLOSED UP 1414.73 PTS OR 2.16%
//Australia’s all ordinaries CLOSED UP 0.60%
//Chinese yuan (ONSHORE) CLOSED DOWN TO 6.7046
/ OFFSHORE CLOSED DOWN AT 6.7068 Oil DOWN TO 90.20 dollars per barrel for WTI and BRENT DOWN TO 97.09 Stocks in Europe OPENED ALL MIXED
ONSHORE USA/ YUAN// WITH YUAN TRADING DOWN (6.7046 OFFSHORE YUAN TRADING DOWN TO 6.7068 ONSHORE YUAN TRADING ABOVE LEVEL // OFF SHORE AND UP ON THE DOLLAR)// / AND THUS WEAKER/OFF SHORE YUAN TRADING DOWN AGAINST US DOLLAR/ AND THUS WEAKER
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
ONSHORE YUAN: CLOSED DOWN AT 6.7046
OFFSHORE YUAN: DOWN TO 6.7068
1A.HANG SANG CLOSED UP 89.70 PTS OR 0.37%
1 B. SHANGHAI CLOSED UP 11.74 OR 0.31%
2. Nikkei closed UP 1414.78 PTS OR 2.16%
WEST TEXAS INTERMEDIATE OIL DOWN TO 90.20
BRENT; 97.09
3. Europe stocks SO FAR: ALL MIXED
USA dollar INDEX DOWN 17 BASIS PTS TO 100.94// EURO RISES TO 1.1358 UP 18 BASIS PTS
3b Japan 10 YR bond yield:FALLS TO. +3.062 DOWN 2 FULL BASIS PTS/ VERY TROUBLESOME//Japan buying 100% of bond issuance)/Japanese YEN vs USA CROSS NOW AT 157.36… JAPANESE YEN NOW FALLING AS WE HAVE NOW REACHED THE ENDING OF THE YEN CARRY TRADE AGAIN AND THE REPATRIATION OF YEN DENOMINATED BONDS TRADING IN THE USA/EUROPE. JAPAN 30 YR BOND YIELD: 4.134 DOWN 3 FULL BASIS PTS
3c Nikkei now ABOVE 17,000
3d USA/Yen rate now well ABOVE the important 120 barrier this morning
3e Gold UP /JAPANESE Yen UP CHINESE ONSHORE YUAN: DOWN (6.7046) AND OFFSHORE: DOWN AT 6.7068
3f Japan is to buy INFINITE TRILLION YEN worth of BONDS. Japan’s GDP equals 5 trillion USA. CENTRAL BANK OF JAPAN WILL NO LONGER DO QE.
Japan to buy 100% of all new Japanese debt and NOW they will have OVER 50% of all Japanese debt. GOVERMENT ASKED JAPAN PENSION FUNDS AND INSURANCE FUNDS TO BUY MORE JAPANESE BONDS AND REPATRIATE ALL FOREIGN BONDS.
3g Oil DOWN for WTI and DOWN for Brent this morning
3h European bond buying continues to push yields LOWER on all fronts in the EU German 10yr bund YIELD DOWN TO +3.5776/ Italian 10 Yr bond yield DOWN AT 4.569/ SPAIN 10 YR BOND YIELD DOWN TO 4.096%
3i Greek 10 year bond yield DOWN TO 4.4350%
3j Gold at $4188.80 /Silver at: 60.85 1 am est) SILVER NEXT RESISTANCE LEVEL AT $100.00
3k USA vs Russian rouble;// Russian rouble UP 0 AND 6/ 100 roubles/83.94
3m oil (WTI) into the 90 dollar handle for WTI and 97 handle for Brent/
3n Higher foreign deposits moving out of China// huge risk of outflows and a currency depreciation. This can spell financial disaster for the rest of the world/
JAPAN ON JAN 29.2016 CONTINUES NIRP. THIS MORNING RAISES AMOUNT OF BONDS THAT THEY WILL PURCHASE UP TO .5% ON THE 10 YR BOND///YEN TRADES TO 157.03 // 10 YEAR YIELD AFTER FIRST BREAKING .54% LAST YEAR NOW EXCEEDS THAT LEVEL TO 3.062% DOWN 2 BASIS PTS STILL ON CENTRAL BANK (JAPAN) INTERVENTION//YEN CARRY TRADE NOW UNWINDING//YEN BOND TRADING OVERSEAS TO BE REPATRIATED.//JAPAN 30 YR: 4.134 DOWN 2 PTS..: USA/SF this 0.8335 as the Swiss Franc . Euro vs SF: 0.9468
USA 10 YR BOND YIELD: 5.224 DOWN 4 BASIS PTS…NOW BELOW 5.00%
USA 30 YR BOND YIELD: 5.560 DOWN 3 BASIS PTS/REFUSES TO GO DOWN WITH BESSENT’S QE TWIST
USA 2 YR BOND YIELD: 4.8721 DOWN 2 BASIS PTS
USA DOLLAR VS TURKISH LIRA: 49.02 UP 2 BASIS PTS/LIRA GETTING KILLED//IDIOTS FOR SELLING GOLD AND USA DOLLAR RESERVES.
10 YR UK BOND YIELD: 5.3934 DOWN 3 PTS
30 YR UK BOND YIELD: 5.903 DOWN 2 BASIS PTS
10 YR CANADA BOND YIELD: 3.999 UP 3 BASIS PTS
5 YR CANADA BOND YIELD: 3.703 UP 2 BASIS PTS.
1a New York Opening report
US Futures, Treasuries Flat Ahead Of Core PCE, Micron Earnings
Wednesday, Sep 30, 2026 – 08:23 AM
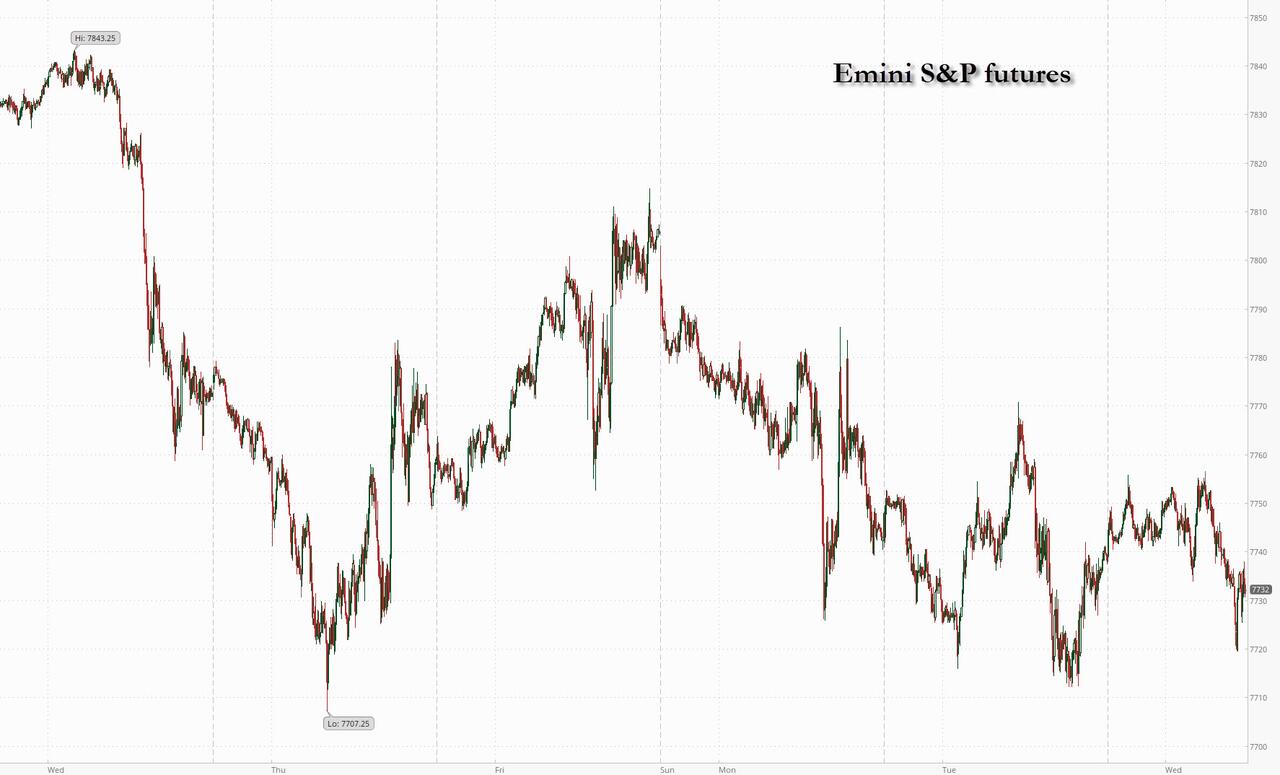
Futures are higher with S&P leading both tech and small caps ahead of today’s core PCE data and Micron earnings after the close, as yields remain sticky, unchanged from yesterday’s multi-decade highs, and the USD fractionally lower. As of 8:00am ET, S&P futures are flat, with Nasdaq futures down fractionally as semis dip -20bp lagging the broader Tech tape but leading Software (-54bp) and Memory (-80bp) after Korea’s Kospi closed lower erasing an early bounce. In premarket trading, Mag7s are the leaders (+28bp) ahead of Micron later. Ex-Tech, the other major sectors are indicated higher pointing to an ‘Everything Rally’ / broadening, albeit on low volume and conviction. With US/Iran deal optimism supporting markets, JPM’s market intel desk, which this week reverted back to being tactically bullish, says that an actual deal likely triggers a tactical squeeze / broadening. Treasuries were little changed a day after 30-year yields hit their highest since 2002. The dollar held near its highest level since July. Commodities are rebounding led by energy: Brent rose modestly to above $103 a barrel, up about 14% for the month despite signs that crude flows from the Middle East are returning to pre-war levels; WTI is above $90/bbl, base metals are leading precious (gold flat; silver down), and ags seeing a broad-based bid. Today’s macro focus is on PCE and 4x Fed speakers with yesterday’s highlight being Williams whose comments pointing to 1x more hike in 2026, not 2x. If PCE prints cooler, we may see a material repricing in bond yields lower.
In premarket trading, Mag 7 stocks are mixed: Alphabet +1%, Nvidia +0.1%, Amazon -0.2%, Apple little changed, Tesla -0.8%, Microsoft -0.1%, Meta Platforms -1%
- Achieve Life Sciences (ACHV) gains 3% after Stifel initiated coverage with a buy recommendation, citing a “potential blockbuster opportunity” for the biotech firm’s smoking-cessation drug candidate.
- Boeing (BA) rises 2% after the company beat Northrop Grumman Corp to produce the Navy’s next Top Gun fighter jet. Northrop (NOC) falls 4.3%.
- Cal-Maine (CALM) falls 6% after the egg producer reported net sales for the first quarter that missed the average analyst estimate, and said it won’t pay a cash dividend in the first quarter.
- Concentrix (CNXC) is down 9% after the call-center operator forecast fourth quarter revenue below expectations amid investor concerns that the business could come under pressure from AI-assisted automation tools.
- FactSet (FDS) falls 2% after the financial-data provider gave a 2027 earnings per share forecast that missed the average analyst estimate.
- GameStop (GME) gains 1% after a filing showed that Chairman and CEO Ryan Cohen purchased $10.6 million worth of shares.
- Moderna (MRNA) declines 6% after Citi downgraded the vaccinemaker to sell, saying optimism from its recent oncology success is more than priced in the stock’s outsized rally.
- Robinhood (HOOD) rises 2% after the brokerage launches new products that help users utilize AI agents to build and execute trading strategies. It’s also allowing customers to trade perpetual futures on some cryptocurrencies.
- Vanda Pharmaceuticals (VNDA) rises 4% after the drugmaker said its drug Hetlioz met its primary endpoint in a late-stage trial for adults with Delayed Sleep-Wake Phase Disorder — a circadian rhythm sleep disorder
In other corporate news, Boeing beat Northrop Grumman to produce the Navy’s next fighter jet, the F/A-XX, with the award valued at more than $20 billion. Concentrix cut its revenue forecast for the year, which Bloomberg Intelligence says highlights “stronger near-term headwinds for customer-experience outsourcing.” Paramount’s delays in financing debt to fund the Warner Bros. Discovery deal could cost the company up to half a billion dollars a year more in interest payments.
Stock futures are edging higher on the last day of a tricky month dominated by surging bond yields – fueled by a sharp repricing of expectations for US interest rate hikes to contain energy-driven inflation – stubbornly high oil prices and alarming AI headlines. Equity volatility has been remarkably subdued, given the backdrop, but hedge funds now seem to be positioning for more volatility. The S&P 500 limited its losses in part thanks to a narrow rally in AI-linked stocks on optimism over the sector’s prospects, a view that will face a test when Micron reports after the close. Treasuries pared gains to leave US 10-year yields only down 1 bp at 5.22%.
“The bar is so, so high that they’ll likely be very good numbers, but it all feeds through into the demand story that we need to keep seeing,” said Rory McPherson at Magnus Financial Discretionary Management. “So long as that holds, I would expect the tech trade to keep moving.”
With a report on US private payrolls and the latest gross domestic product update due alongside the PCE release, Ipek Ozkardeskaya at Swissquote noted that different combinations of readings could have a range of outcomes for markets. “A combination of robust growth and a recovery in the jobs market would allow the Fed to hike rates to fight rising inflationary pressures, provided that price pressures look concerning,” she said. “That would keep upward pressure on short-term yields and the US dollar, while weighing on equities.”
But it is the core PCE that will be key for direction today. Bloomberg Economics expects the report to show an acceleration in monthly inflation. For PCE price indexes, Bureau of Economic Analysis updated methodology for calculating inflation in three components is expected to trim August year-on-year change by a few tenths of a percentage point.
Growth and jobs data below expectations and elevated inflation could see the gap between two- and 10-year US yields narrow, threatening risk appetite and weighing on the dollar. Strong GDP and jobs figures coupled with a softer-than-expected PCE reading would be the best possible scenario, easing pressure on yields and supporting equities, though also the furthest from her base case.
While equities are ending September little changed from the start of the month, market breadth is weak, with S&P 500 equal-weight lagging the cap-weighted set for the largest monthly underperformance on a down month since 2020. Stocks have been held up by tech and AI gains, putting Goldman Sachs’ High Beta Momo Index on track for its best month since June 2000.
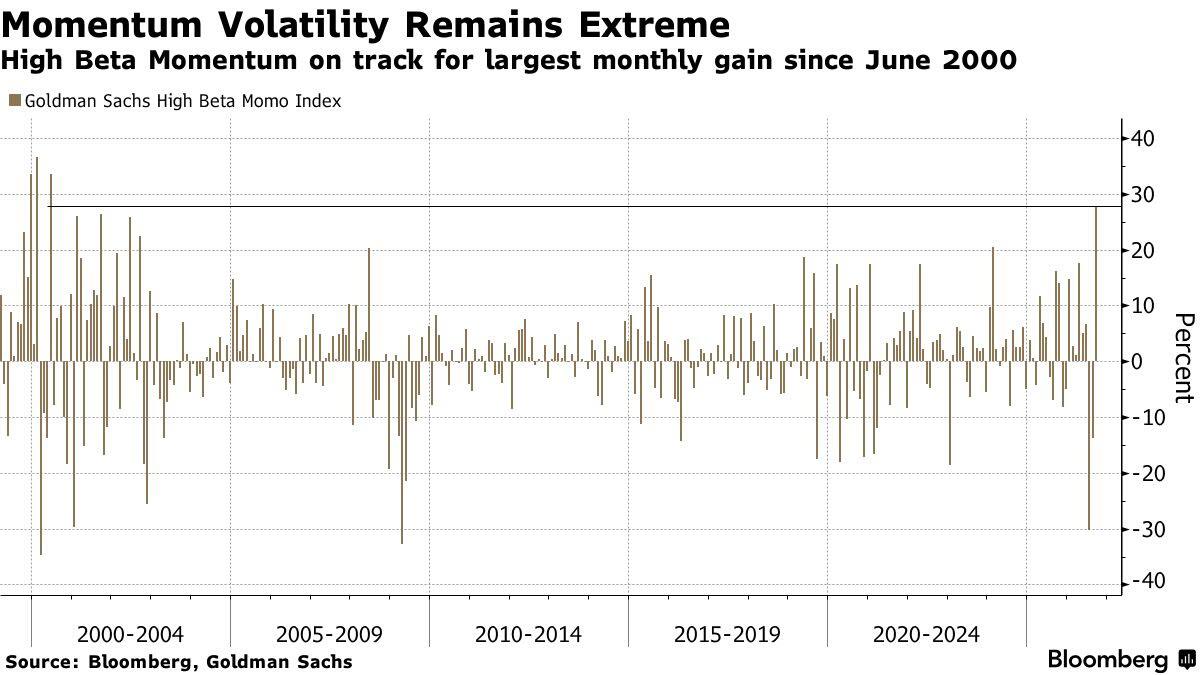
Besides the PCE data, Micron’s latest results will be keenly watched – more for the chipmaker’s commentary and outlook than headline results (consensus expects 355% year-on-year sales growth). We will have a full preview shortly. Elsewhere in tech, there were a flurry of headlines from OpenAI’s DevDay – from fundraising plans to the unveiling of personal AI agent Dots.
On the AI safety narrative, Trump endorsed using independent audits to assess the safety of AI systems through an accord with Silicon Valley leaders that seeks to sidestep new government rules in addressing rising concerns about AI risks. Not every one is convinced. We don’t know whether AI represents an existential threat, but “the policy response is a superficial rebranding attempt,” says Jonestrading’s Mike O’Rourke.
Apollo Chief Economist Torsten Slok, meanwhile, asks if AI customers will generate a lot more cash than analysts expect, or if tech firms’ cash flow forecasts are too optimistic, as both outlooks can’t be correct at the same time. It “raises the question of who exactly will be writing all those checks to buy AI services,” notes Slok.
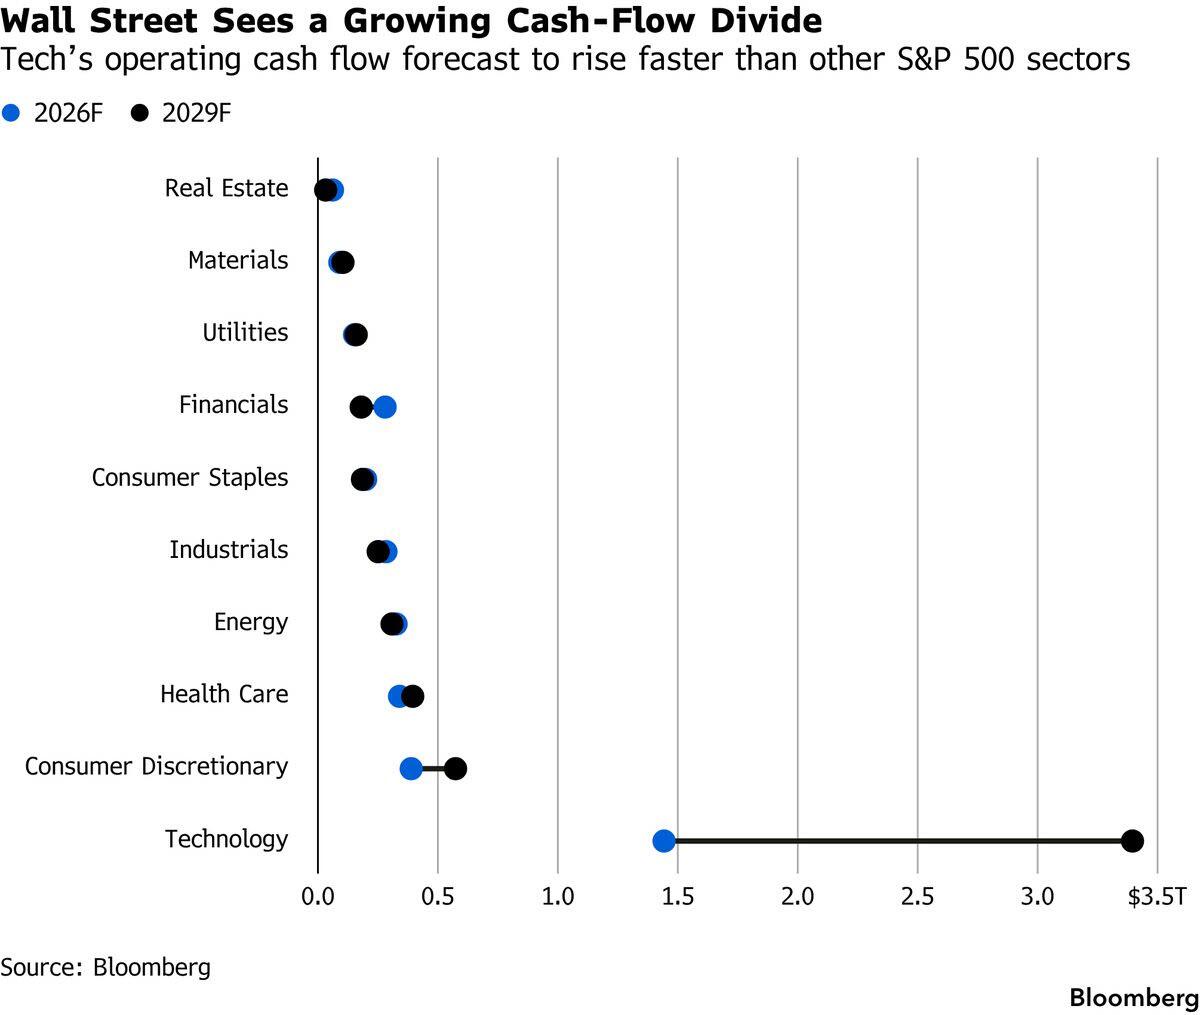
As reported previously, hedge funds net sold global stocks for the first time in five weeks through Sept. 24, while buying US tech more than any other sector for a fourth straight week, according to Goldman Sachs’s Prime desk. Barclays strategists, meanwhile, note that equities continued to see inflows in September but they say momentum is fading as higher rates diminish the appeal of the so-called TINA trade.
European stocks were set for their first monthly decline since March. Inflation overshot estimates in France and Italy, increasing pressure on the European Central Bank to continue raising interest rates. The 10-year French yield premium over safer German peers widened one basis point to 120 basis points, the highest since 2012. Here are the biggest movers Wednesday:
- Kongsberg shares rise as much as 5.6% after the defense company signed contracts worth billions of Norwegian kroner and DNB Carnegie upgraded its recommendation to buy from hold
- Saga shares soar as much as 15%, the most since January, after the company reported underlying pretax profit well ahead of expectations for the first-half and raised its guidance for the full year
- Zegona Communications gains 4.4% after Goldman Sachs analysts initiated the investment firm with a buy rating, citing structural growth in the Spanish telecom market and opportunities to improve margins and cash generation
- Avanza gains as much as 3.1% and Nordnet as much as 4.3% after Deutsche Bank initiated coverage of the Swedish savings and investment platforms with buy and hold ratings, respectively. The bank says both are “two winners”
- UK water firms rise after Prime Minister Andy Burnham’s comments on the country’s water sector at the Labour Party conference on Tuesday are seen as a “first step in reassurance” in regards to concerns over nationalization, according to Morgan Stanley
- International Workplace Group shares rise as much as 6.2%, the most in five months, after the flexible-office provider increased its 2026 share buyback program by up to $50 million
- Intercontinental Hotels Group rises as much as 2.6% to a five-week high after Goldman Sachs increased its revenue estimate on US outperformance and Middle East resilience
- Everplay shares rise 9.5% to a new high three-year high after the video game developer boosted its revenue guidance thanks to strong performance from new titles
- Sinch shares drop as much as 7.5% after the cloud communications provider was initiated with a sell rating at Pareto Securities, which said it will struggle to achieve its growth targets
- Tullow Oil shares fall as much as 52% after the UK exploration & production firm lost its arbitration case with Ghana related to a $196.5m tax assessment
- Future falls as much as 12% in London after the media company said FY2026 results will meet market expectations, but paused its share buyback to prioritize deleveraging
- Juventus shares fall as much as 15% after the Turin-based football club reported an increased annual loss, warned of another in the year ahead and said it plans to raise €250 million through an issue of ordinary shares
Asian stocks rose for the first time in three days, as oil prices steadied. The MSCI Asia Pacific Index was up 0.8% in late afternoon trading, and is on track to close the quarter nearly 1% higher. Japan led the gains Wednesday while Thailand and South Korea fell. While crude prices have since steadied, its earlier retreat on signs of easing supply disruption helped alleviate investor concerns about energy-induced inflationary pressures. The rebound in equities also came after a brutal selloff in global bonds took a breather.
In FX, the BBG dollar index is modestly lower while the pound sits atop the G-10 FX pile, rising 0.3% against the dollar after UK GDP was unexpectedly revised higher for the second quarter. Sterling also seemed to derive support from UK PM Andy Burnham suggesting he could campaign to take Britain back into the European Union at the next general election. The Aussie dollar is at the other end of the table, underperforming peers after Australian CPI rose less than expected. The euro adds a few pips after hot French and German state CPI data. Elsewhere, Chinese property stocks reversed losses as investors looked past a mortgage subsidy program that fell short of expectations and focused on the possibility of further support measures.
In commodities, WTI crude oil futures advance, reversing some of yesterday’s drop while Brent crude futures for December rise 1% to around $97 a barrel, sapping some of the earlier upside in bonds. Bitcoin is fractionally higher, trading just under $84K.
In rates, treasuries pared earlier gains and are narrowly mixed in early US session, keeping yields within a basis points of Tuesday’s close. US 10-year yields near 5.24%, reversing an earlier drop, and lagging German counterpart by about 4bp, UK’s by about 1bp. Following comments by Fed’s Williams on Tuesday, tightening priced into front-end swaps has ebbed to around 12bp for the October decision and a combined 32bp over the October and December meetings. European bonds outperform following data including French and German CPI readings and UK GDP. IG dollar issuance slate includes a couple of names so far. Paramount Skydance Corp.’s eight-tranche, $30 billion offering is expected to be priced, with terms ranging from two to 40 years. Initial price talk for the 2066 maturity is a spread of about 3.65 percentage points vs the Treasury benchmark. The US session includes a raft of economic releases headed by August personal income and spending and its PCE price indexes, and comments by four Fed officials.
“We’re remain sellers of OATs against the Bund,” said Kevin Thozet at Carmignac in Paris. “The economy in France is deteriorating while improving at the same time within its neighbors. We think the direction of travel is toward 150 basis points, at which point we’d have to reassess.”
US economic data slate includes September ADP employment change (8:15 a.m.), August personal income and spending, 2Q GDP revision, and August wholesale inventories (8:30am) and September MNI Chicago PMI (9:45 a.m., several minutes earlier for subscribers).Fed speaker slate includes Richmond’s Barkin (1:30 p.m.), Governor Cook (3:25 p.m.), Chicago’s Goolsbee (5:10 p.m.) and Minneapolis’s Kashkari (6 p.m.)
Market Snapshot
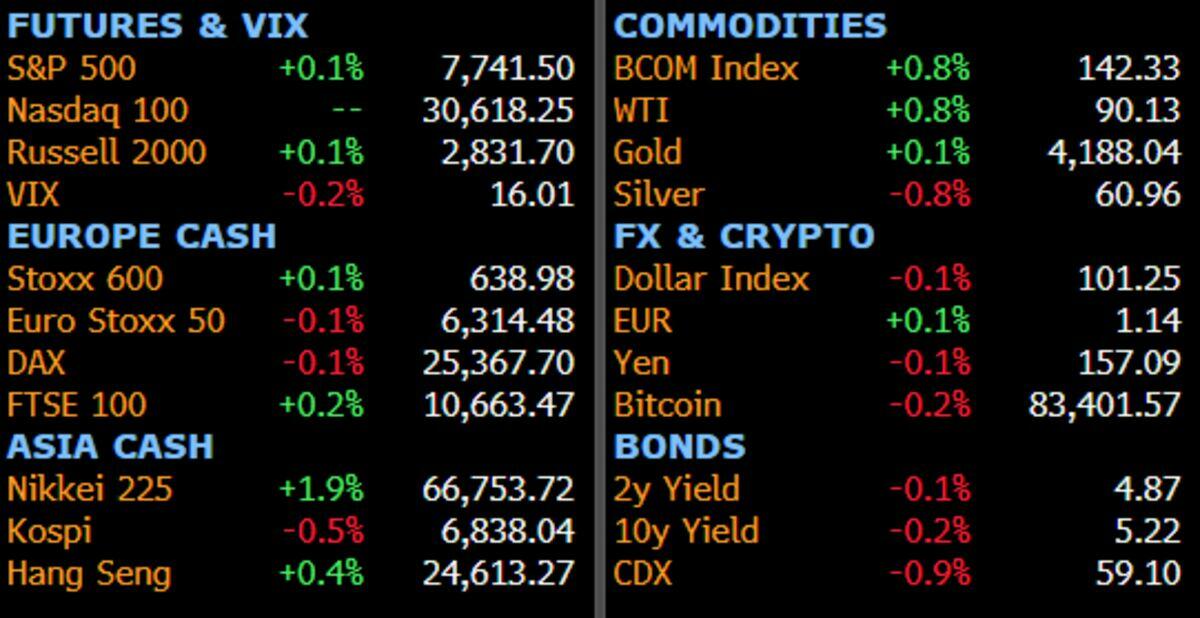
Top Overnight News
- Efforts this week by Qatari mediators to broker a diplomatic breakthrough between the U.S. and Iran have made little progress, with neither side willing to budge, according to three sources familiar with the talks. The stalemate bolsters the belief on both sides that a renewed military conflict is becoming more likely. U.S. officials think President Trump could order a return to major combat operations after the midterms. Axios
- Donald Trump has held crisis talks with advisers over whether to impose a diesel export ban or take other steps to contain a fuel crisis that threatens to derail his Republican Party’s midterm election campaign. RTRS
- Donald Trump endorsed using outside auditors to assess the safety of AI systems in a pact with Silicon Valley leaders that sidesteps new government rules. BBG
- Abu Dhabi is pursuing a $300 billion infrastructure push to reduce reliance on the Strait of Hormuz and curb Iran’s leverage. BBG
- Trump released the White House Accord on Super Intelligence following the meeting with AI executives on Tuesday, while the document noted that every company is responsible for developing its own technology safely and each should apply four layers of controls and audits, including implementing strong internal controls to oversee model capabilities and alignment.
- Democratic Lawmaker Raskin has reportedly sent letters to Amazon, Google, Meta and Oracle, requesting information regarding NDAs signed with government officials in relation to AI data center projects: WSJ.
- China’s economy showed signs of improvement at the end of the third quarter, with official and private gauges of factory, services and construction activity all picking up. WSJ
- China’s latest economic stimulus package appears designed to keep economic growth on target rather than deliver a broad revival, leaving investors waiting for more aid to address the country’s underlying demand weakness. BBG
- DeepSeek released software developed with Huawei to program AI chips, highlighting their push to challenge Nvidia. BBG
- Inflation overshot estimates in France and Italy with energy remaining the main driver. Prices jumped 3.4% in France, the fastest in more than two years, while in Italy they advanced by 4.1%, the most since 2023. BBG
- President Donald Trump could unveil plans as soon as Wednesday to tap South Korea’s pledged strategic investment package for about $54 billion to build a liquefied natural gas facility in Alaska and several other major US projects. RTRS
- Trump told Axios that Jay Clayton would be a good AI czar.
A more detailed look at global markets courtesy of Newsquawk
APAC stocks were ultimately mixed following the recent drop in oil prices and upside in long-term US yields, while participants digested a slew of data at month- and quarter-end. ASX 200 rallied with nearly all sectors in the green and real estate leading the advances as softer-than-expected headline monthly CPI data and a wider contraction in building approvals lessened the odds for an RBA November rate hike. Nikkei 225 gapped above the 66,000 level and continued to advance with the index shrugging off disappointing Industrial Production and Retail Sales data, in which the former showed a surprise contraction. KOSPI traded indecisively amid weak data and tensions with North Korea after a DMZ landmine explosion injured South Korean officers, while South Korea’s military stated that North Korea’s fortification works increased tensions in the Korean peninsula and that it should apologise for its fortification works.
Hang Seng and Shanghai Comp were mixed, with the Hang Seng indecisive and the mainland mildly underpinned following the encouraging Chinese PMI data, in which headline official Manufacturing PMI matched estimates at 50.1, and Non-Manufacturing topped forecasts and returned to expansion territory at 50.2 (exp. 49.3), while RatingDog Manufacturing and Services PMIs were both stronger-than-expected. In addition, the PBoC recently announced support measures including a 25bps cut to the Pledged Supplementary Lending facility rate to 1.50% from 1.75%, while participants look ahead to the National Day holidays and the week-long closure in the mainland beginning tomorrow.
Top Asian News
- Japanese PM Takaichi said that the administration will boost supply side of the economy and that the government will clarify the direction of economic and fiscal policy management.
- Japan’s Finance Minister said that they has been in close communication with the BoJ at all levels and sees no big difference in views on the economy and prices.
- South Korea’s Finance Ministry said it is watching bond market developments closely and plans to use excess tax revenue to lower bond issuance if required, while it will conduct other stabilising measures including treasury bond buybacks if bond yields rise excessively.
European bourses (STOXX 600 +0.1%) were initially posting gains across the board, but have since waned off best levels as energy benchmarks move higher. Sectors highlight the positive bias. Retail tops the sector pile, with Utilities and Optimised Personal Care rounding out the sector gainers. To the downside is Media, Energy and Construction. Key movers include: Greggs (+7.5%), guides a modestly improved outcome for 2026; Gerresheimer (+3.1%), Q2 metrics rises Q/Q and points to a stronger H2’26; TomTom (+1.7%), expands its Microsoft (MSFT) collaboration; Commerzbank (-2.7%), downgraded to hold from Buy at Deutsche Bank.
Top European News
- UK PM Burnham has suggested that a move to rejoin the EU is among the options for the UK, talking to BBC Radio 4. The current settlement has caused more harm than good.
- Germany’s SEFE said the German Economy Ministry has ordered the procurement and storage of 8 TWh of natural gas by December 15th.
- The German government plans to introduce a sugar tax on July 1, 2027, according to Welt citing a draft. The report added that the government expects it will generate an additional EUR 945mln for the federal budget next year.
- Swedish NIER raised its 2026 CPIF inflation forecast to 1.6% (prev. 1.3%) and 2027 to 2.6% (prev. 2.1%). NIER raised its 2026 GDP forecast to 3.09% (prev. 2.4%) and cut 2027 to 2.4% (prev. 2.8%).
FX
- Snapshot: G10s are mostly firmer against the USD this morning, which has been hampered following dovish comments from the Fed’s Williams on Tuesday. GBP leads post-GDP, whilst the Aussie lags post-CPI.
- DXY is a touch lower this morning, and trades within a 101.19 to 101.46 range; ultimately holding within the prior day’s confines. Some of the mild pressure today is facilitated by Fed’s Williams, who suggested that there was less of a need for a hike in October given the recent move in September. The downside in USD is nonetheless capped given he clarified that one more rate hike “late this year” may be appropriate.
- On the data front, PCE is due today. Analysts expect the PCE headline to rise by 0.4% M/M (prev. 0.2%), and the annual rate is seen ticking up to 3.8% Y/Y (prev. 3.7%); core PCE is expected to rise by 0.3% M/M (prev. 0.2%), with the annual rate of core PCE seen rising to 3.4% Y/Y (prev. 3.3%). Another factor to note, the Bureau of Economic Analysis will release updated PCE deflator methodology, applied retroactively through Q1 2021. RBC estimates that core PCE’s annual pace is expected to fall 18bps, which would revise July’s reading to 3.1% from 3.3%.
- GBP currently holds towards the top of the G10 list, with Cable holding at the upper end of a 1.3223 to 1.3278 range. The strength comes after mild revisions higher in Q2 GDP, though will likely have little impact on the BoE in the near term. Elsewhere, the JPY also performs well, continuing the strength seen overnight. This comes despite poor Japanese Industrial Production data overnight. In the European morning, Nikkei reported that PM Takaichi will vow a nimble response to unexpected market moves.
- EUR is a little firmer this morning, digesting inflation reports out of France and German states so far. French inflation topped expectations amidst rising energy costs, whilst German state metrics held a slight hawkish skew. Overall, nothing all too surprising for the region, given that ECB members have continued to voice concerns about the inflation outlook; however, a sustained rise in prices, evidence of second-round effects and/or lack of US-Iran progress will likely bring an October rate hike into view.
- AUD is the laggard this morning, following a weaker-than-expected CPI report; odds of a November hike are priced in at 24%, with a number of key metrics due until then. Westpac analysts reiterated their call for a hold at the November meeting following the inflation figures.
Fixed Income
- Fixed is firmer across the board, despite the modest upside in energy and hotter-than-expected inflation out of France and Germany, with Gilts leading as the space gets respite from its recent trajectory, benefitting from UK PM Burnham’s comments and strong GDP data.
- Specifically, Burnham said he was open to numerous outcomes with regards to UK-EU relations as the current post-Brexit situation is causing more harm than good. Among the options to consider, he stated they could “go all the way”, i.e. rejoin. A remark which, alongside the upwardly revised Q2 GDP series, has led to outperformance across UK assets this morning, with Gilts, GBP and the FTSE 100 the best performer or among the best in their respective market area.
- However, while welcome, the upside was only c. 50 ticks at best in Gilts and leaves the benchmark only a point at best above the 83.72 contract low, with yields across the curve off highs, but also still in close proximity to such levels.
- Across the Channel, OATs trade broadly in-line with their German counterpart, with gains of around 40 ticks at the time of writing. However, the OAT-Bund 10yr yield spread has widened further, to over 120bps and the widest since 2012. A move that comes after Tuesday’s debt update and the associated implications of the current plan for the debt-to-GDP ratio vs the EU’s EDP threshold.
- Bunds themselves experienced a modest pullback off best levels on the German state CPIs, which printed broadly as expected but with a slight hawkish skew vs the mainland consensus at 13:00BST today. Albeit, the move was modest in nature, with Bunds holding just above 120.00, firmer by over 40 ticks, vs a 120.17 peak.
- USTs bid, but the relative underperformers thus far, into a busy afternoon of data and potentially geopolitics. On the latter, we know that Iranian President Pezeshkian has now received the proposal via Araghchi from New York. We now await the leader’s assessment of the matter. Elsewhere, PCE is due today and is perhaps more pertinent given the methodology changes included.
- Germany sells EUR 4.177bln vs Exp. 5.5bln 3.00% 2036 Bund: b/c 1.16x (prev. 1.47x), average yield 3.58% (prev. 3.39%), retention 24.1% (prev. 23.62%).
- Japan sells JPY 2.15tln 2-year JGB: b/c 3.89X (prev. 2.97X), average yield 1.964% (prev. 1.708%), Tail in price 0.014 (prev. 0.034).
Commodities
- WTI Nov and Brent Dec futures remain subdued after yesterday’s pronounced downside, with conflicting US-Iran developments providing little impetus for a sustained recovery. Crude also remains pressured by yesterday’s bearish supply headline which suggested the US offering up to 40mln bbls from the SPR, while private inventories showed a surprise 1mln bbl build (vs exp. 1.1mln draw). Modest upside was seen in the complex this morning after reports of a potential hijacking involving a Dubai-Tel Aviv flight, but was later seen as not a security-incident. However, recent reporting has suggested that the incident may be a “terrorist incident”. Separately, UKMTO reported that a crude oil tanker was struck on the port side by an unknown projectile in the Strait of Hormuz on September 30.
- WTI currently trades towards the upper end of a USD 88.58-90.77/bbl range, while Brent sits around the middle of a USD 95.12-97.61/bbl range. Dutch TTF is choppy, with Germany ordering the procurement and storage of 8 TWh of natural gas by 15th December as Europe continues efforts to bolster inventories ahead of winter. TTF now trades towards the middle of a EUR 67.88-70.78/MWh range.
- Precious metals are mixed, with gold firmer as global yields ease following yesterday’s sharp steepening, while participants await US PCE later today. Spot gold eclipsed USD 4,200/oz to notch a current range between USD 4,166-4,201/oz, recovering further from Monday’s sharp sell-off. Spot silver is slightly softer and trades around the middle of a USD 60.84-61.72/oz range.
- Base metals are firmer following Chinese PMI data, with the official Manufacturing PMI returning to expansion at 50.1 and Non-Manufacturing rising to 50.2, while RatingDog Manufacturing and Services also topped expectations. Note, China heads for a week-long National Day holiday from tomorrow. 3M LME copper trades towards the top end of a USD 14,458.70-14,550.88/t range.
- In terms of notable geopolitics, Iran received Washington’s response to its seven-point proposal via Qatari mediators, with reports suggesting the main disagreement centres on the sequencing of the proposed seven-day framework rather than its components. However, Axios reported that talks and mediation efforts this week have yielded little progress, raising the risk of renewed hostilities, while Iran maintains that the Hormuz issue and US blockade must be resolved before nuclear negotiations.
- US Private Inventory Data (bbls): Crude +1.0mln (exp. -1.1mln), Gasoline +3.0mln (exp. -0.5mln), Distillate -0.3mln (exp. +0.0mln), Cushing +0.2mln.
- OPEC+ oil producers are reportedly set to keep output targets unchanged at this Sunday’s meeting, according to sources.
- US White House held crunch talks on a diesel export ban as midterms near, according to FT.
- US President Trump will unveil a USD 54bln Alaska LNG plan amid midterm woes.
- The Russian government has extended the ban on diesel fuel exports until end-October, IFX reported.
- Oman OSP for Nov’ Crude set at USD 114.07/bbl (prev. USD 87.84/bbl).
- Iraq’s oil exports averaged 2.65mln BPD in September, including 250k BPD shipped via Turkey’s Ceyhan port, according to the Oil Ministry spokesperson.
Trade/Tariffs
- USTR Greer said tariff caps will be considered when setting tariffs in the Section 301 excess‑capacity probe.
- China’s MOFCOM warned that if the European side persists in introducing discriminatory restrictions on Chinese enterprises or products, China will resolutely respond in the interests of Chinese industry. It also said regarding reports of some EU member states mulling more forceful trade measures on China, that the tools mentioned are typical protectionist and unilateralist measures and will disrupt the stability of China-EU trade.
- The EU is open to providing single-market access to those looking to join the bloc, on the condition they stand with the EU against industrial competition and hostile nations, according to Politico citing sources.
- EU trade chief Sefcovic said they are pushing for reforms to tackle excess industrial capacity in G20 and WTO frameworks, while they are working for greater cooperation with the US and other allies to secure supply chains and prevent weaponisation of critical minerals.
Central Banks
- Fed’s Williams said rising bond yields show tighter financial conditions at the margin. On AI, Williams said that it is not causing big changes in job levels while highlighting that strong AI investment is important to boost future productivity. On the recent rise in yields, Williams doesn’t believe it is signalling a shift in longer-run inflation views.
- BoE Financial Policy Committee (Sep): The re-escalation of the conflict in the Middle East has renewed uncertainty around growth and the path of interest rates in a number of advanced economies.
Geopolitics: Iran
- The Iranian government spokesperson said Foreign Minister Araghchi presented President Pezeshkian with a US proposal following his New York trip, which included discussions on Iran’s conditions for reopening the Strait of Hormuz, IRNA reported. This followed a Reuters report, which also highlighted that the main dispute between the US and Iran does not concern the components of the plan itself, but rather the order of operations and the stages of implementation of the seven-day framework.
- US White House is reportedly tempering expectations of an imminent breakthrough between US-Iran, Semafor reported, with a source suggesting that “the bar is being raised very high.”
- A senior source said mediators are working to return negotiations to a broader track that includes the nuclear issue, Al Hadath reported.
- US-Iran talks and efforts by mediators this week yielded little progress, raising the odds of renewed combat, while Qatar will continue efforts despite growing frustrations with both sides, according to Axios.
- IRGC aerospace advisor said Iran can sustain current missile firing rates for years and the era of attacks without response is over.
- UKMTO said that a crude oil tanker was struck on the port side by an unknown projectile in the Strait of Hormuz on September 29th. Following this, UKMTO separately reported that an LNG tanker was struck by an unknown projectile on September 29th within the Strait of Hormuz.
- An incident was reported on a plane flying from Dubai to Tel Aviv, with recent reporting suggesting that the incident was a terrorist attack, Al Jazeera reported. The report suggested that the co-pilot who stabbed the other pilot was of Omani origin.
Geopolitics: Other
- Russian Defence Ministry said energy system facilities in Kyiv region were hit in a massive strike, according to IFX.
- Loud explosions have been heard in Kyiv, Ukraine.
- South Korean military said North Korea fortification works increased tensions on the Korean peninsula and that North Korea should stop fortification works immediately, while it added that North Korea should apologise for its fortification work and that South Korea military personnel were seriously wounded by North Korean mines.
- North Korea said South Korea is fabricating baseless findings regarding a mine blast in the demilitarised zone that injured troops, while it warned that South Korea could encounter a miserable and catastrophic situation.
US Event Calendar
- 7:00 am: Sep 25 MBA Mortgage Applications, prior -1.5%
- 8:15 am: Sep ADP Employment Change, est. 74.5k, prior 38k
- 8:30 am: Aug Personal Income, est. 0.5%, prior 0.43%
- 8:30 am: Aug Personal Spending, est. 0.85%, prior 0.16%
- 8:30 am: Aug PCE Price Index YoY, est. 3.7%, prior 3.7%
- 8:30 am: Aug Core PCE Price Index MoM, est. 0.3%, prior 0.2%
- 8:30 am: Aug Core PCE Price Index YoY, est. 3.3%, prior 3.34%
- 8:30 am: 2Q T GDP Annualized QoQ, est. 1.5%, prior 1.5%
- 8:30 am: 2Q T Personal Consumption, est. 3.4%, prior 3.4%
- 8:30 am: 2Q T GDP Price Index, est. 6.4%, prior 6.4%
- 8:30 am: 2Q T Core PCE Price Index QoQ, est. 3.6%, prior 3.6%
- 8:30 am: Aug P Wholesale Inventories MoM, est. 0.45%, prior 1.3%
- 9:45 am: Sep MNI Chicago PMI, est. 51, prior 47.1
Central Banks
- 1:30 pm: Fed’s Barkin Gives Welcome Remarks at Rural America Conference
- 3:25 pm: Fed’s Cook Speaks at Investing in Rural America Conference
- 5:10 pm: Fed’s Goolsbee Gives Keynote Address
- 6:00 pm: Fed’s Kashkari Speaks in Fireside Chat
DB’s Jim Reid concludes the overnight wrap
Good evening from Phoenix where I’m just about to go to bed after I press send here. I’m the keynote lunchtime speaker at our huge long standing annual LevFin conference which attracts over a 1,000 investors and issuers. I’m literally hemmed in by golf courses here which is a bit tortuous not having clubs with me and having to work.
While I’m away, we’re running our end-Q3 market survey. There are several highly topical questions this month. One asks respondents to rank the key drivers behind the recent rise in yields, while another explores how the US is ultimately likely to address its fiscal challenges. We also have a couple of timely questions on oil and on how the Iran conflict may evolve ahead of the US midterm elections. I would be grateful if as many of you could fill in as possible. It should take 2-3 minutes and can be accessed here.
As we await today’s latest US core PCE, and arrive at quarter-end, markets have put in a pretty mixed performance over the last 24 hours, with divergent signals across the major asset classes. On one level there was relief, as oil and gas prices fell back again thanks to some positive supply headlines, with Brent crude down -2.56% to $102.59/bbl. And together with NY Fed’s Williams suggesting there is no “urgency” for the next hike, that helped to dial back expectations of Fed tightening. However, it wasn’t all good news, as the 30yr Treasury yield (+1.9bps) rose for a sixth consecutive session, reaching a post-2002 high of 5.67%. And despite the energy pullback there were still other signs of stress, as US and European HY spreads reached their widest since April, whilst the Franco-German 10yr spread rose to its widest level since 2012.
We’ll start with the energy news, as the turnaround in oil and gas prices was one of the big stories yesterday. At the European open, it looked like we were set for another day of gains, with Brent crude initially rising to $107/bbl. However, several headlines contributed to the pullback, including a Reuters report that Saudi Arabia had resumed oil loadings from the port of Yanbu. And that follows on from Bloomberg’s report the previous day that Saudi Arabia had now restored around half the flows through the East-West pipeline.
Meanwhile, the US announced that it will offer up to 40m barrels from its Strategic Petroleum Reserve, in what would be its last drawdown in the coordinated global release of oil announced earlier in the year. So that helped oil prices stage a decent intraday turnaround. Brent settled -2.59% lower while WTI crude (-3.48%) saw a larger decline to a 4-week low of $89.48/bbl, with the gap between the two benchmarks widening as the current front-month Brent future expires today. Meanwhile, European natural gas (-4.95%) saw an even bigger decline.
Yet even with the pullback in oil and gas prices, investors struggled to get too excited. There are still no obvious signs of progress towards a deal, and we actually saw longer-dated Brent futures move up once again, with the December 2027 future up another +0.65% yesterday, reaching a new high of $80.81/bbl. So for investors, they’re still pricing in a lengthier period of disruption, even as increased oil flows out of the Gulf have eased the near-term pressure.
That backdrop led to a mixed session for US Treasuries. Initially, yields hit fresh highs across most of the curve before paring back those gains, with the 10yr yield ending the day unchanged at its post-2007 high of 5.24%. Despite the eventual pullback, there was still a fresh milestone for 30yr yields (+1.9bps), which reached a post-2002 high of 5.57%. However, at the front end the 2yr yield fell -5.4bps, and therefore we saw a decent sized steepening on the day.
In addition to the decline in energy prices, the front-end rally was helped by comments from NY Fed President Williams, who said that he saw one more rate hike “late this year” as appropriate and that “there is no need for urgency” following the September hike. So that suggested a high bar to hike as soon as the next meeting in October, and money markets cut back the pricing of an October rate hike from 70% to 47% in response. In other Fedspeak, Governor Barr signaled that further hikes are likely without offering any colour on their likely pace, while St Louis Fed President Musalem suggested that “policy remains somewhat accommodative” after the September hike.
Meanwhile, we also got a slightly weaker set of second-tier US data. The somewhat backward-looking job openings for August showed an unexpectedly big slowing to 7.079m (vs. 7.228m expected), which is their lowest level in 5 months. In addition, the Conference Board’s consumer confidence measure also saw an unexpectedly big fall to 81.9 in September (vs. 89.0 expected), marking its lowest level since 2014. We did get some more upbeat house price data, with the S&P Case Schiller (+0.32% vs +0.20% expected) and FHFA (+0.3% vs +0.1% expected) series both seeing larger monthly increases. Next up, we have today’s core PCE and the jobs report on Friday, which are likely to get far more attention.
Given all that, US equities struggled to gain traction as well yesterday, with the S&P 500 (-0.17%) slipping back for a second day running. That retreat was fairly broad, with energy (-0.89%) and materials (-0.55%) sectors leading the decline in the S&P 500, while the small-cap Russell 2000 fell -0.35%. The decline would have been worse were it not for a jump among chip stocks, as the Philly semiconductor index rose +1.32%. That move came as Trump pushed back against the idea of new federal AI regulations in a meeting with top AI and tech executives, which agreed on a framework for voluntary audits.
European equities were mixed, with the CAC (-0.53%) and FTSE 100 (-0.45%) leading the Stoxx 600 (-0.09%) lower, though the DAX (+0.10%) eked out at advance.
European bonds mostly struggled to gain traction, despite the boost from lower energy prices. To be fair, there were some that advanced, and the 10yr bund yield (-1.7bps) fell back from its post-2009 high of 3.64%. However, there was a worse performance elsewhere, with the 10yr OAT yield (+4.2bps) at a post-2008 high of 4.81%, whilst the 10yr BTP yield (+2.2bps) hit a post-2023 high of 4.61%. And in turn, that meant the Franco-German 10yr spread continued to widen, up to another post-2012 high of 118bps by the close. This widening came as France’s debt agency unveiled a plan to borrow a record €340bn in 2027 and amid protests by public-service staff and students ahead of the formal presentation of France’s 2027 budget tomorrow.
Fiscal issues also got some attention in the UK yesterday as Prime Minister Burnham spoke at the Labour Party’s annual conference. His proposed plans included dropping the current pension triple lock after 2030, opening the door to public ownership of water companies and suggesting that the UK will seek a closer relationship with the EU. The 10yr gilt yield ended the day -1.0bps lower.
Asian equity markets are mostly higher this morning, with the Nikkei (+1.28%) leading the gains, while the S&P/ASX 200 (+0.79%), Shanghai Composite (+0.30%), and CSI 300 (+0.18%) are also trading higher. In contrast, the KOSPI (-0.27%) has surrendered its early gains, while the Hang Seng (+0.03%) is flat. S&P (+0.23%) and Nasdaq (+0.23%) futures are higher with Stoxx (+0.69%) contracts even more so.
Early morning data showed that China’s manufacturing sector gained momentum in September, with both private and official surveys pointing to an improvement in economic activity. The private-sector RatingDog Manufacturing PMI rose to 52.1 from 51.5 in August, surpassing expectations of 51.7 and marking its strongest reading since April. The services PMI also improved to 51.6 from 51.4, ahead of forecasts for 51.3. Separately, China’s official manufacturing PMI increased to 50.1 in September from 49.8 in August, in line with expectations and returning to expansionary territory after two months of contraction. The official non-manufacturing PMI climbed to 50.2 from 49.0, comfortably beating forecasts of 49.2, while the composite PMI rose to 50.7 from 49.5.
Elsewhere, Australia’s inflation accelerated in August, although the increase was marginally softer than expected. Headline CPI rose +4.0% y/y, up from +3.5% in July but slightly below consensus expectations of +4.1%. The trimmed mean, closely watched by the RBA as a gauge of underlying price pressures, held steady at +3.6% y/y and rose +0.2% m/m in August, suggesting core inflation remains sticky despite some moderation in the broader inflation outlook.
Looking at the day ahead now, and European data releases include the September flash CPI prints for Germany, France and Italy, along with German unemployment for September. In the US, we’ll also get the PCE inflation print for August, the third estimate of Q2 GDP, and the ADP’s report of private payrolls for September. From central banks, we’ll hear from the Fed’s Barkin, Cook, Goolsbee and Kashkari, along with the ECB’s Schnabel.
1b) European opening report
Iran receives US feedback on the seven-point proposal; AUD lags post-CPI while DXY eyes PCE – Newsquawk US Market Open
Wednesday, Sep 30, 2026 – 05:48 AM
- US White House is reportedly tempering expectations of an imminent breakthrough between US-Iran, Semafor reported, with a source suggesting that “the bar is being raised very high.”
- The Iranian government spokesperson said Foreign Minister Araghchi presented President Pezeshkian with a US proposal following his New York trip, which included discussions on Iran’s conditions for reopening the Strait of Hormuz, IRNA reported.
- UKMTO said that a crude oil tanker was struck on the port side by an unknown projectile in the Strait of Hormuz on September 29th.
- US equity futures pare back earlier gains with Micron earnings on the docket after-hours.
- DXY continues to fall following dovish comments by Fed’s Williams; AUD underperforms following cooler-than-expected inflation.
- Fixed income benchmarks climb; Gilts weighed on by the upside GDP revision.
- Energy benchmarks rebound slightly from Tuesday’s losses (Brent +1.1%).
- Looking ahead, highlights include German CPI (Sep), US PCE Price Index (Aug/Q2), GDP Final (Q2), Atlanta Fed GDP. Speakers include ECB’s Elderson & Schnabel, Fed’s Barkin, Cook, Goolsbee & Kashkari. The US Treasury buyback announcement (10-20yr; liquidity support). Earnings from Micron, Accenture & McCormick.
SNAPSHOT

Newsquawk in 3 steps:
1. Subscribe to the free premarket movers reports
2. Listen to this report in the market open podcast (available on Apple and Spotify)
3. Trial Newsquawk’s premium real-time audio news squawk box for 7 days
EUROPEAN TRADE
EQUITIES
- European bourses (STOXX 600 +0.1%) were initially posting gains across the board, but have since waned off best levels as energy benchmarks move higher.
- Sectors highlight the positive bias. Retail tops the sector pile, with Utilities and Optimised Personal Care rounding out the sector gainers. To the downside is Media, Energy and Construction.
- Key movers include: Greggs (+7.5%), guides a modestly improved outcome for 2026; Gerresheimer (+3.1%), Q2 metrics rises Q/Q and points to a stronger H2’26; TomTom (+1.7%), expands its Microsoft (MSFT) collaboration; Commerzbank (-2.7%), downgraded to hold from Buy at Deutsche Bank.
- US equity futures follow their European counterparts, with focus being on PCE and final Q2 GDP, while Micron is to report earnings after-hours. Analysts are expecting Q4 revenue to grow 354% from a year prior. Focus will be on guidance, with Morgan Stanley analysts shifting the debate from ‘how good it can get?’ to ‘how long can it stay this good?’.
- Click for the sessions European pre-market equity newsflow
- Click for the additional news
FX
- Snapshot: G10s are mostly firmer against the USD this morning, which has been hampered following dovish comments from the Fed’s Williams on Tuesday. GBP leads post-GDP, whilst the Aussie lags post-CPI.
- DXY is a touch lower this morning, and trades within a 101.19 to 101.46 range; ultimately holding within the prior day’s confines. Some of the mild pressure today is facilitated by Fed’s Williams, who suggested that there was less of a need for a hike in October given the recent move in September. The downside in USD is nonetheless capped given he clarified that one more rate hike “late this year” may be appropriate.
- On the data front, PCE is due today. Analysts expect the PCE headline to rise by 0.4% M/M (prev. 0.2%), and the annual rate is seen ticking up to 3.8% Y/Y (prev. 3.7%); core PCE is expected to rise by 0.3% M/M (prev. 0.2%), with the annual rate of core PCE seen rising to 3.4% Y/Y (prev. 3.3%). Another factor to note, the Bureau of Economic Analysis will release updated PCE deflator methodology, applied retroactively through Q1 2021. RBC estimates that core PCE’s annual pace is expected to fall 18bps, which would revise July’s reading to 3.1% from 3.3%.
- GBP currently holds towards the top of the G10 list, with Cable holding at the upper end of a 1.3223 to 1.3278 range. The strength comes after mild revisions higher in Q2 GDP, though will likely have little impact on the BoE in the near term. Elsewhere, the JPY also performs well, continuing the strength seen overnight. This comes despite poor Japanese Industrial Production data overnight. In the European morning, Nikkei reported that PM Takaichi will vow a nimble response to unexpected market moves.
- EUR is a little firmer this morning, digesting inflation reports out of France and German states so far. French inflation topped expectations amidst rising energy costs, whilst German state metrics held a slight hawkish skew. Overall, nothing all too surprising for the region, given that ECB members have continued to voice concerns about the inflation outlook; however, a sustained rise in prices, evidence of second-round effects and/or lack of US-Iran progress will likely bring an October rate hike into view.
- AUD is the laggard this morning, following a weaker-than-expected CPI report; odds of a November hike are priced in at 24%, with a number of key metrics due until then. Westpac analysts reiterated their call for a hold at the November meeting following the inflation figures.
FIXED INCOME
- Fixed is firmer across the board, despite the modest upside in energy and hotter-than-expected inflation out of France and Germany, with Gilts leading as the space gets respite from its recent trajectory, benefitting from UK PM Burnham’s comments and strong GDP data.
- Specifically, Burnham said he was open to numerous outcomes with regards to UK-EU relations as the current post-Brexit situation is causing more harm than good. Among the options to consider, he stated they could “go all the way”, i.e. rejoin. A remark which, alongside the upwardly revised Q2 GDP series, has led to outperformance across UK assets this morning, with Gilts, GBP and the FTSE 100 the best performer or among the best in their respective market area.
- However, while welcome, the upside was only c. 50 ticks at best in Gilts and leaves the benchmark only a point at best above the 83.72 contract low, with yields across the curve off highs, but also still in close proximity to such levels.
- Across the Channel, OATs trade broadly in-line with their German counterpart, with gains of around 40 ticks at the time of writing. However, the OAT-Bund 10yr yield spread has widened further, to over 120bps and the widest since 2012. A move that comes after Tuesday’s debt update and the associated implications of the current plan for the debt-to-GDP ratio vs the EU’s EDP threshold.
- Bunds themselves experienced a modest pullback off best levels on the German state CPIs, which printed broadly as expected but with a slight hawkish skew vs the mainland consensus at 13:00BST today. Albeit, the move was modest in nature, with Bunds holding just above 120.00, firmer by over 40 ticks, vs a 120.17 peak.
- USTs bid, but the relative underperformers thus far, into a busy afternoon of data and potentially geopolitics. On the latter, we know that Iranian President Pezeshkian has now received the proposal via Araghchi from New York. We now await the leader’s assessment of the matter. Elsewhere, PCE is due today and is perhaps more pertinent given the methodology changes included.
- Germany sells EUR 4.177bln vs Exp. 5.5bln 3.00% 2036 Bund: b/c 1.16x (prev. 1.47x), average yield 3.58% (prev. 3.39%), retention 24.1% (prev. 23.62%).
- Japan sells JPY 2.15tln 2-year JGB: b/c 3.89X (prev. 2.97X), average yield 1.964% (prev. 1.708%), Tail in price 0.014 (prev. 0.034).
COMMODITIES
- WTI Nov and Brent Dec futures remain subdued after yesterday’s pronounced downside, with conflicting US-Iran developments providing little impetus for a sustained recovery. Crude also remains pressured by yesterday’s bearish supply headline which suggested the US offering up to 40mln bbls from the SPR, while private inventories showed a surprise 1mln bbl build (vs exp. 1.1mln draw). Modest upside was seen in the complex this morning after reports of a potential hijacking involving a Dubai-Tel Aviv flight, but was later seen as not a security-incident. However, recent reporting has suggested that the incident may be a “terrorist incident”. Separately, UKMTO reported that a crude oil tanker was struck on the port side by an unknown projectile in the Strait of Hormuz on September 30.
- WTI currently trades towards the upper end of a USD 88.58-90.77/bbl range, while Brent sits around the middle of a USD 95.12-97.61/bbl range. Dutch TTF is choppy, with Germany ordering the procurement and storage of 8 TWh of natural gas by 15th December as Europe continues efforts to bolster inventories ahead of winter. TTF now trades towards the middle of a EUR 67.88-70.78/MWh range.
- Precious metals are mixed, with gold firmer as global yields ease following yesterday’s sharp steepening, while participants await US PCE later today. Spot gold eclipsed USD 4,200/oz to notch a current range between USD 4,166-4,201/oz, recovering further from Monday’s sharp sell-off. Spot silver is slightly softer and trades around the middle of a USD 60.84-61.72/oz range.
- Base metals are firmer following Chinese PMI data, with the official Manufacturing PMI returning to expansion at 50.1 and Non-Manufacturing rising to 50.2, while RatingDog Manufacturing and Services also topped expectations. Note, China heads for a week-long National Day holiday from tomorrow. 3M LME copper trades towards the top end of a USD 14,458.70-14,550.88/t range.
- In terms of notable geopolitics, Iran received Washington’s response to its seven-point proposal via Qatari mediators, with reports suggesting the main disagreement centres on the sequencing of the proposed seven-day framework rather than its components. However, Axios reported that talks and mediation efforts this week have yielded little progress, raising the risk of renewed hostilities, while Iran maintains that the Hormuz issue and US blockade must be resolved before nuclear negotiations.
- US Private Inventory Data (bbls): Crude +1.0mln (exp. -1.1mln), Gasoline +3.0mln (exp. -0.5mln), Distillate -0.3mln (exp. +0.0mln), Cushing +0.2mln.
- OPEC+ oil producers are reportedly set to keep output targets unchanged at this Sunday’s meeting, according to sources.
- US White House held crunch talks on a diesel export ban as midterms near, according to FT.
- US President Trump will unveil a USD 54bln Alaska LNG plan amid midterm woes.
- The Russian government has extended the ban on diesel fuel exports until end-October, IFX reported.
- Oman OSP for Nov’ Crude set at USD 114.07/bbl (prev. USD 87.84/bbl).
- Iraq’s oil exports averaged 2.65mln BPD in September, including 250k BPD shipped via Turkey’s Ceyhan port, according to the Oil Ministry spokesperson.
TRADE/TARIFFS
- USTR Greer said tariff caps will be considered when setting tariffs in the Section 301 excess‑capacity probe.
- China’s MOFCOM warned that if the European side persists in introducing discriminatory restrictions on Chinese enterprises or products, China will resolutely respond in the interests of Chinese industry. It also said regarding reports of some EU member states mulling more forceful trade measures on China, that the tools mentioned are typical protectionist and unilateralist measures and will disrupt the stability of China-EU trade.
- The EU is open to providing single-market access to those looking to join the bloc, on the condition they stand with the EU against industrial competition and hostile nations, according to Politico citing sources.
- EU trade chief Sefcovic said they are pushing for reforms to tackle excess industrial capacity in G20 and WTO frameworks, while they are working for greater cooperation with the US and other allies to secure supply chains and prevent weaponisation of critical minerals.
NOTABLE EUROPEAN HEADLINES
- UK PM Burnham has suggested that a move to rejoin the EU is among the options for the UK, talking to BBC Radio 4. The current settlement has caused more harm than good.
- Germany’s SEFE said the German Economy Ministry has ordered the procurement and storage of 8 TWh of natural gas by December 15th.
- The German government plans to introduce a sugar tax on July 1, 2027, according to Welt citing a draft. The report added that the government expects it will generate an additional EUR 945mln for the federal budget next year.
- Swedish NIER raised its 2026 CPIF inflation forecast to 1.6% (prev. 1.3%) and 2027 to 2.6% (prev. 2.1%). NIER raised its 2026 GDP forecast to 3.09% (prev. 2.4%) and cut 2027 to 2.4% (prev. 2.8%).
NOTABLE EUROPEAN DATA RECAP
- UK GDP Growth Rate Final (Q2 QQ) 0.5% vs. Exp. 0.4% (Prev. 0.6%).
- UK GDP Growth Rate Final (Q2 YY) 1.4% vs. Exp. 1.2% (Prev. 0.9%).
- UK Lloyds Business Barometer (Sep) +41% (Prev. +53%).
- French HICP Preliminary (Sep YY) 3.4% vs. Exp. 3.1% (Prev. 2.6%).
- French HICP Preliminary (Sep MM) -0.4% vs. Exp. -0.5% (Prev. 0.7%).
- German North Rhine Westphalia CPI (Sep YY) 3.3% (Prev. 2.9%).
- German North Rhine Westphalia CPI (Sep MM) 0.6% (Prev. 0.2%).
- German Import Prices (Aug MM) 1.0% vs. Exp. 0.7% (Prev. 0.2%).
- German Import Prices (Aug YY) 8.3% vs. Exp. 8% (Prev. 6.8%).
- German Retail Sales (Aug MM) 1.3% vs. Exp. 1.5% (Prev. -3.4%).
- German Retail Sales (Aug YY) -0.4% vs. Exp. 0.1% (Prev. -2.5%).
- Italian HICP Preliminary (Sep YY) 4.1% vs. Exp. 3.8% (Prev. 3.2%).
- Italian HICP Preliminary (Sep MM) 2.0% vs. Exp. 1.8% (Prev. 0.1%).
CENTRAL BANKS
- Fed’s Williams said rising bond yields show tighter financial conditions at the margin. On AI, Williams said that it is not causing big changes in job levels while highlighting that strong AI investment is important to boost future productivity. On the recent rise in yields, Williams doesn’t believe it is signalling a shift in longer-run inflation views.
- BoE Financial Policy Committee (Sep): The re-escalation of the conflict in the Middle East has renewed uncertainty around growth and the path of interest rates in a number of advanced economies.
NOTABLE US HEADLINES
- US President Trump told Axios that Jay Clayton would be a good AI czar.
- US President Trump released the White House Accord on Super Intelligence following the meeting with AI executives on Tuesday, while the document noted that every company is responsible for developing its own technology safely and each should apply four layers of controls and audits, including implementing strong internal controls to oversee model capabilities and alignment.
- US Democratic Lawmaker Raskin has reportedly sent letters Amazon (AMZN), Google (GOOGL), Meta (META) and Oracle (ORCL), requesting information regarding NDAs signed with government officials in relation to AI data center projects, according to the WSJ.
GEOPOLITICS
MIDDLE EAST
- The Iranian government spokesperson said Foreign Minister Araghchi presented President Pezeshkian with a US proposal following his New York trip, which included discussions on Iran’s conditions for reopening the Strait of Hormuz, IRNA reported. This followed a Reuters report, which also highlighted that the main dispute between the US and Iran does not concern the components of the plan itself, but rather the order of operations and the stages of implementation of the seven-day framework.
- US White House is reportedly tempering expectations of an imminent breakthrough between US-Iran, Semafor reported, with a source suggesting that “the bar is being raised very high.”
- A senior source said mediators are working to return negotiations to a broader track that includes the nuclear issue, Al Hadath reported.
- US-Iran talks and efforts by mediators this week yielded little progress, raising the odds of renewed combat, while Qatar will continue efforts despite growing frustrations with both sides, according to Axios.
- IRGC aerospace advisor said Iran can sustain current missile firing rates for years and the era of attacks without response is over.
- UKMTO said that a crude oil tanker was struck on the port side by an unknown projectile in the Strait of Hormuz on September 29th. Following this, UKMTO separately reported that an LNG tanker was struck by an unknown projectile on September 29th within the Strait of Hormuz.
- An incident was reported on a plane flying from Dubai to Tel Aviv, with recent reporting suggesting that the incident was a terrorist attack, Al Jazeera reported. The report suggested that the co-pilot who stabbed the other pilot was of Omani origin.
RUSSIA-UKRAINE
- Russian Defence Ministry said energy system facilities in Kyiv region were hit in a massive strike, according to IFX.
- Loud explosions have been heard in Kyiv, Ukraine.
OTHER
- South Korean military said North Korea fortification works increased tensions on the Korean peninsula and that North Korea should stop fortification works immediately, while it added that North Korea should apologise for its fortification work and that South Korea military personnel were seriously wounded by North Korean mines.
- North Korea said South Korea is fabricating baseless findings regarding a mine blast in the demilitarised zone that injured troops, while it warned that South Korea could encounter a miserable and catastrophic situation.
CRYPTO
- Bitcoin found a trough at USD 82.9k before completely reversing to top at USD 83.8k.
APAC TRADE
- APAC stocks were ultimately mixed following the recent drop in oil prices and upside in long-term US yields, while participants digested a slew of data at month- and quarter-end.
- ASX 200 rallied with nearly all sectors in the green and real estate leading the advances as softer-than-expected headline monthly CPI data and a wider contraction in building approvals lessened the odds for an RBA November rate hike.
- Nikkei 225 gapped above the 66,000 level and continued to advance with the index shrugging off disappointing Industrial Production and Retail Sales data, in which the former showed a surprise contraction.
- KOSPI traded indecisively amid weak data and tensions with North Korea after a DMZ landmine explosion injured South Korean officers, while South Korea’s military stated that North Korea’s fortification works increased tensions in the Korean peninsula and that it should apologise for its fortification works.
- Hang Seng and Shanghai Comp were mixed, with the Hang Seng indecisive and the mainland mildly underpinned following the encouraging Chinese PMI data, in which headline official Manufacturing PMI matched estimates at 50.1, and Non-Manufacturing topped forecasts and returned to expansion territory at 50.2 (exp. 49.3), while RatingDog Manufacturing and Services PMIs were both stronger-than-expected. In addition, the PBoC recently announced support measures including a 25bps cut to the Pledged Supplementary Lending facility rate to 1.50% from 1.75%, while participants look ahead to the National Day holidays and the week-long closure in the mainland beginning tomorrow.
NOTABLE ASIA-PAC HEADLINES
- Japanese PM Takaichi said that the administration will boost supply side of the economy and that the government will clarify the direction of economic and fiscal policy management.
- Japan’s Finance Minister said that they has been in close communication with the BoJ at all levels and sees no big difference in views on the economy and prices.
- South Korea’s Finance Ministry said it is watching bond market developments closely and plans to use excess tax revenue to lower bond issuance if required, while it will conduct other stabilising measures including treasury bond buybacks if bond yields rise excessively.
NOTABLE APAC DATA RECAP
- Chinese RatingDog Manufacturing PMI (Sep) 52.1 vs. Exp. 51.6 (Prev. 51.5).
- Chinese RatingDog Services PMI (Sep) 51.6 vs. Exp. 51.1 (Prev. 51.4).
- Chinese RatingDog Composite PMI (Sep) 52.4 (Prev. 52.1).
- Chinese NBS Manufacturing PMI (Sep) 50.1 vs. Exp. 50.1 (Prev. 49.8).
- Chinese NBS Non Manufacturing PMI (Sep) 50.2 vs. Exp. 49.3 (Prev. 49.0).
- Chinese NBS General PMI (Sep) 50.7 (Prev. 49.5).
- Australian CPI (Aug YY) 4.0% vs. Exp. 4.1% (Prev. 3.5%).
- Australian CPI (Aug MM) 0.4% vs. Exp. 0.5% (Prev. 1%).
- Australian RBA Trimmed Mean CPI (Aug YY) 3.6% vs. Exp. 3.6% (Prev. 3.6%).
- Australian RBA Trimmed Mean CPI (Aug MM) 0.2% vs. Exp. 0.3% (Prev. 0.5%).
- Japanese Industrial Production Prel (Aug MM) -1.7% vs. Exp. 1.7% (Prev. -0.2%).
- Japanese Industrial Production Prel (Aug YY) 3.4% (Prev. 3.9%).
1c Asian opening report
APAC stocks were ultimately mixed, with US-Iran showing little progress; European equity futures indicate a positive cash market open – Newsquawk EU Market Open
Wednesday, Sep 30, 2026 – 01:57 AM
- US-Iran talks and efforts by mediators this week yielded little progress, raising the odds of renewed combat, while Qatar will continue efforts despite growing frustrations with both sides, according to Axios.
- An Iranian diplomatic source said Iran will only be ready to discuss the nuclear issue after the Strait of Hormuz issue is resolved and Washington lifts the blockade.
- APAC stocks were ultimately mixed; European equity futures indicate a positive cash market open.
- DXY took a breather after gaining yesterday; 10yr UST futures edged higher overnight following the prior day’s steepening.
- Crude futures were constrained after sliding yesterday following several downside catalysts; Spot gold was little changed beneath the USD 4,200/oz level.
- Looking ahead, highlights include German Retail Sales (Aug), French CPI (Sep), German State/National CPI (Sep), Italian CPI (Sep), US PCE Price Index (Aug/Q2), GDP Final (Q2), Atlanta Fed GDP. Speakers include ECB’s Elderson & Schnabel, Fed’s Barkin, Cook, Goolsbee & Kashkari. Supply from Germany, US Treasury buyback announcement (10-20yr; liquidity support), Earnings from Micron, Accenture & McCormick.
Newsquawk in 3 steps:
1. Subscribe to the free premarket movers reports
2. Listen to this report in the market open podcast (available on Apple and Spotify)
3. Trial Newsquawk’s premium real-time audio news squawk box for 7 days
SNAPSHOT
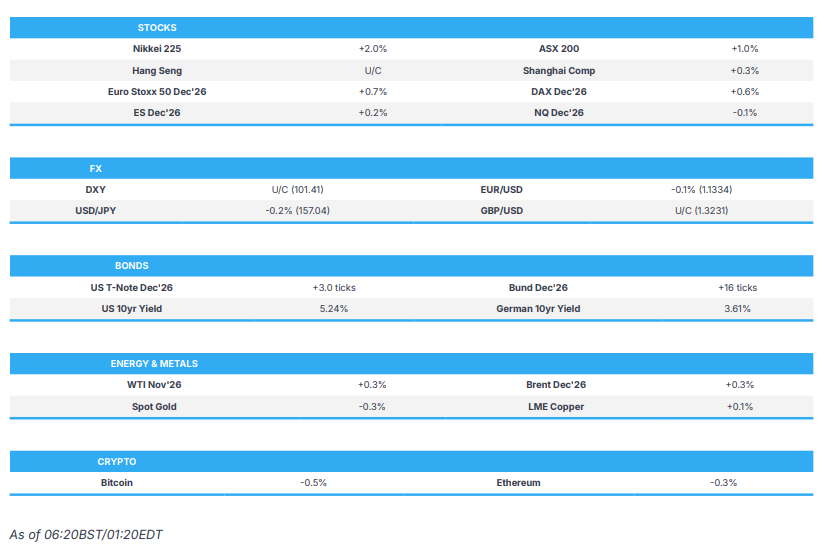
IRAN CONFLICT
- US President Trump said Iran is doing very poorly and he doesn’t know if they will give up yet.
- US-Iran talks and efforts by mediators this week yielded little progress, raising the odds of renewed combat, while Qatar will continue efforts despite growing frustrations with both sides, according to Axios.
- US OFAC sanctioned 10 individuals and entities across multiple jurisdictions under Operation Economic Outcast for procuring weapons and components for Iran’s Ministry of Defence and armed forces.
- Mediators push to break the US-Iran deadlock, and negotiators were expected to hand over the latest amended draft of a proposed interim agreement to Iran on Tuesday, according to FT.
- Iranian diplomatic source said Iran will only be ready to discuss the nuclear issue after the Strait of Hormuz issue is resolved and Washington lifts the blockade, while Iran will be ready to discuss the nuclear dossier only after a number of conditions are met, according to Russia’s RIA.
- IRGC claimed in a recent letter to the American people that it had destroyed more than 200 drones, 30 fighter jets, 12 tankers and transport aircraft and one AWACS, according to Fars News Agency.
- A drone reportedly fired at an offending ship in the southern route of the Strait of Hormuz.
- Iranian Foreign Ministry said regarding Israeli PM Netanyahu’s visit to the UAE that all countries in the region should be careful about the consequences of this trip, according to Fars News.
- Israeli PM Netanyahu was reportedly urging the UAE to engage in the war on Yemen in exchange for restoring some of Abu Dhabi’s regional roles, according to Al Mayadeen.
- Saudi source denied that Saudi Arabia was involved in the Israel-UAE talks.
- Yemeni sources said Saudi forces conducted a missile attack on the Sahar district in Yemen’s Saada.
- Houthi source told Al-Mayadeen that any attempt to establish Saudi-backed groups and troop buildups will be met with targeting, while the source stated daily Saudi airstrikes are indiscriminate, target civilian infrastructure and will not go unanswered.
- Israeli army conducted a new bombing in the city of Khiam in southern Lebanon, while Israel also conducted attacks on eastern areas of Gaza City.
- IDF is prepared for a wide range of scenarios in the near and far theatres, while no concrete, well-founded information has emerged so far that directly links Election Day in Israel to escalation.
US TRADE
EQUITIES
- US stocks were mixed, with most major indices in the red although the tech-heavy Nasdaq 100 outperformed and closed with gains as Oracle saw strength amid reports that OpenAI’s annual recurring revenue is reportedly close to USD 70bln, a steep increase from earlier reports of an annualised run rate over USD 40bln by mid-2026. Sectors were varied, as Utilities and Communication Services sat atop of the breakdown, while Energy lagged amid the losses in the crude complex after some more positive US/Iran rhetoric, as well as a couple of other bearish oil reports, including Trump backing Russia sanctions relief on prisoner release, and would create a path for the US to sign lucrative deals involving Russian oil, diesel, rare earth minerals, while the US DoE offered up to 40mln barrels from SPR.
- SPX -0.17% at 7,671, NDX +0.21% at 30,339, DJI -0.26% at 51,355, RUT -0.35% at 2,808.
- Click here for a detailed summary.
TARIFFS/TRADE
- US Trade Representative Greer said tariff caps will be considered when setting tariffs in the Section 301 excess‑capacity probe.
- US Agriculture Secretary Rollins said they will have more agricultural products going to China.
- China’s MOFCOM warned that if the European side persists in introducing discriminatory restrictions on Chinese enterprises or products, China will resolutely respond in the interests of Chinese industry. It also said regarding reports of some EU member states mulling more forceful trade measures on China, that the tools mentioned are typical protectionist and unilateralist measures and will disrupt the stability of China-EU trade.
- EU trade chief Sefcovic said they are pushing for reforms to tackle excess industrial capacity in G20 and WTO frameworks, while they are working for greater cooperation with the US and other allies to secure supply chains and prevent weaponisation of critical minerals.
NOTABLE HEADLINES
- Fed’s Barr (voter) said there is a need to recalibrate policy, with a base case that further policy adjustments are likely needed, while he stated that risks to achieving the inflation target have increased and risks to the labour market have reduced. Furthermore, Barr expects GDP growth to pick up a bit in H2 from 2% in H1 and said inflation is a clear concern, with the Fed having been knocked off course to its 2% goal. Barr also said he is seeing some elevated wage rates in the skilled trades and that, taking the longer view, the Fed needs to be sure to do what it takes to bring supply and demand into balance.
- Fed’s Williams (voter) said he sees no need for urgency after the September rate hike, while he added that US economic momentum is strong and may be strengthening. Williams stated AI investment issues are an increasingly big issue for inflation, and he sees US GDP at 2.25% this year and unemployment at 4% over 2027, as well as stated that Fed policy can make sure the impact of supply shocks is not long-lasting.
- Fed’s Goolsbee (2027 voter) said expectations of productivity gains from AI in the future create a high danger of overheating now and noted that nothing in the Federal Reserve Act says to make sure the bond market is happy or stock markets are not surprised. Goolsbee also stated that the Fed needs to revisit the logic of looking through supply shocks.
- Fed’s Musalem (2028 voter) said central bankers needn’t make promises, but should tell the public how and why the central bank makes policy decisions. He also stated that a well-articulated framework should include two or three likely scenarios, and that central banks should avoid communications and actions with no framework to make sense of them.
- US President Trump released the White House Accord on Super Intelligence following the meeting with AI executives on Tuesday, while the document noted that every company is responsible for developing its own technology safely and each should apply four layers of controls and audits, including implementing strong internal controls to oversee model capabilities and alignment.
- US President Trump said the AI meeting was very good and very productive, while he added the US has a big lead in AI and will keep the lead. Trump also announced he would sign the AI renaming order and stated that AI leaders are to work with local communities on data centres.
- US President Trump said he will be naming an AI czar in the next three or four days and that he discussed the Xi meeting in great detail with tech firms, while it was later reported that Trump said Jay Clayton would be a good AI czar, according to Axios.
APAC TRADE
EQUITIES
- APAC stocks were ultimately mixed following the recent drop in oil prices and upside in long-term US yields, while participants digested a slew of data at month- and quarter-end.
- ASX 200 rallied with nearly all sectors in the green and real estate leading the advances as softer-than-expected headline monthly CPI data and a wider contraction in building approvals lessened the odds for an RBA November rate hike.
- Nikkei 225 gapped above the 66,000 level and continued to advance with the index shrugging off disappointing Industrial Production and Retail Sales data, in which the former showed a surprise contraction.
- KOSPI traded indecisively amid weak data and tensions with North Korea after a DMZ landmine explosion injured South Korean officers, while South Korea’s military stated that North Korea’s fortification works increased tensions in the Korean peninsula and that it should apologise for its fortification works.
- Hang Seng and Shanghai Comp were mixed, with the Hang Seng indecisive and the mainland mildly underpinned following the encouraging Chinese PMI data, in which headline official Manufacturing PMI matched estimates at 50.1, and Non-Manufacturing topped forecasts and returned to expansion territory at 50.2 (exp. 49.3), while RatingDog Manufacturing and Services PMIs were both stronger-than-expected. In addition, the PBoC recently announced support measures including a 25bps cut to the Pledged Supplementary Lending facility rate to 1.50% from 1.75%, while participants look ahead to the National Day holidays and the week-long closure in the mainland beginning tomorrow.
- US equity futures were marginally higher following the mostly subdued performance on Wall St, while participants await key data including the latest PCE price index.
- European equity futures indicate a positive cash market open with Euro Stoxx 50 futures up 0.7% after the cash market closed with gains of 0.3% on Tuesday.
FX
- DXY took a breather after gaining yesterday amid a rise in long-term yields, albeit with some of the gains pared following dovish remarks from Fed’s Williams, who sees no need for urgency after the September rate hike and noted there is time to gather more information to provide greater clarity on the underlying economic trends and associated risks, while participants now await a slew of data including final Q2 GDP and the Fed’s preferred PCE inflation gauge.
- EUR/USD was lacklustre after having trickled lower for most of the prior day despite hawkish-leaning rhetoric from ECB officials, but with a floor seen after dovish comments from Fed’s Williams.
- GBP/USD struggled for direction after recently giving up ground to the greenback and with the currency not helped by PM Burnham’s vow to scrap the pensions triple lock, while UK final Q2 GDP is due today.
- USD/JPY briefly retreated beneath the 157.00 handle and breached a weekly low, despite the lack of obvious drivers behind the move and disappointing domestic activity data, although the pair then rebounded
- Antipodeans were somewhat mixed with NZD/USD flat, while AUD/USD was pressured following a slew of data, including softer-than-expected headline monthly inflation and a worse-than-feared contraction in building approvals, but with the downside stemmed as participants also digested encouraging Chinese PMI releases.
- PBoC set USD/CNY mid-point at 6.7351 vs Exp. 6.7025 (prev. 6.7411)
FIXED INCOME
- 10yr UST futures edged higher overnight following the prior day’s steepening, in which the short-end had rebounded on dovish remarks from Fed Williams, who sees no need for urgency after the September rate hike, while he argued there is time to gather more information to provide greater clarity on the underlying economic trends and associated risks in support of setting the appropriate monetary policy.
- Bund futures kept afloat after benefitting from the recent pullback in oil prices, while participants await looming German supply and data, including Retail Sales and CPI figures.
- 10yr JGB futures were choppy amid the positive risk mood in Tokyo stocks and weak data from Japan, while the 2yr JGB auction results were mostly stronger-than-previous.
COMMODITIES
- Crude futures were constrained after sliding yesterday following several downside catalysts, including US President Trump backing a strategy to ease Russia sanctions in exchange for the release of political prisoners, which could pave the way for deals involving Russian oil, diesel, rare earth minerals, and other commodities. In addition, the US DoE offered up to 40mln barrels from the SPR, while Qatar stated mediation efforts are ongoing and focused on building common ground between the US and Iran, although a more recent article by Axios stated US-Iran talks and efforts by mediators this week yield little progress, raising odds of renewed combat.
- US Private Inventory Data (bbls): Crude +1.0mln (exp. -1.1mln), Gasoline +3.0mln (exp. -0.5mln), Distillate -0.3mln (exp. +0.0mln), Cushing +0.2mln.
- OPEC+ is likely to stick with the plan for steady quotas, according to delegates.
- US reportedly offers up to 40mln barrels from strategic oil reserve.
- US President Trump will unveil a USD 54bln Alaska LNG plan amid midterm woes.
- White House held crunch talks on a diesel export ban as midterms near, according to FT.
- White House urged the EU to draw down from diesel emergency inventories in a bid to lower global prices. It was also reported that the Trump administration said several EU member countries have not released as much oil and refined products from reserves as they promised.
- EU Energy Commissioner said they have discussed possible oil release with IEA’s Birol, and still need to have talks with member states and IEA on these issues.
- Spot gold was little changed beneath the USD 4,200/oz level amid a steady dollar and ahead of a deluge of US data releases, including the Fed’s preferred inflation gauge.
- Copper futures pared the majority of its earlier gains of the day amid mixed risk appetite and despite encouraging Chinese PMI data releases.
CRYPTO
- Bitcoin marginally declined in choppy range-bound trade above the USD 83,000 level.
NOTABLE ASIA-PAC HEADLINES
- South Korea’s Finance Ministry said it is watching bond market developments closely and plans to use excess tax revenue to lower bond issuance if required, while it will conduct other stabilising measures including treasury bond buybacks if bond yields rise excessively.
DATA RECAP
- Chinese NBS Manufacturing PMI (Sep) 50.1 vs. Exp. 50.1 (Prev. 49.8)
- Chinese NBS Non-Manufacturing PMI (Sep) 50.2 vs. Exp. 49.3 (Prev. 49.0)
- Chinese RatingDog Manufacturing PMI (Sep) 52.1 vs. Exp. 51.6 (Prev. 51.5)
- Chinese RatingDog Services PMI (Sep) 51.6 vs. Exp. 51.1 (Prev. 51.4)
- Chinese RatingDog Composite PMI (Sep) 52.4 (Prev. 52.1)
- Japanese Retail Sales (Aug YY) 2.7% vs. Exp. 3.3% (Prev. 3.7%)
- Japanese Industrial Production Prel (Aug MM) -1.7% vs. Exp. 1.7% (Prev. -0.2%)
- South Korean Industrial Production (Aug YY) -2.2% vs. Exp. 4% (Prev. 4.0%)
- Australian CPI (Aug YY) 4.0% vs. Exp. 4.1% (Prev. 3.5%)
- Australian RBA Trimmed Mean CPI (Aug YY) 3.6% vs. Exp. 3.6% (Prev. 3.6%)
- Australian Building Permits Prel (Aug MM) -6.1% vs. Exp. -2% (Prev. -3.6%)
GEOPOLITICS
OTHER
- US President Trump said North Korean Leader Kim will be fine as long as he is around.
- South Korean military said North Korea fortification works increased tensions on the Korean peninsula and that North Korea should stop fortification works immediately, while it added that North Korea should apologise for its fortification work and that South Korea military personnel were seriously wounded by North Korean mines.
- North Korea said South Korea is fabricating baseless findings regarding a mine blast in the demilitarised zone that injured troops, while it warned that South Korea could encounter a miserable and catastrophic situation.
- China’s military stationed readiness patrols over the Scarborough Shoal’s sea and airspace.
EU/UK
NOTABLE HEADLINES
- BoE’s Mann said inflation staying above 2% is an equality problem.
- BoE’s Taylor said the right policy response is to be vigilant but disciplined and monetary policy should not react mechanically to movements in energy prices if those movements remain primarily relative-price shocks. Taylor added that the case for further rate increases is not compelling to him unless energy prices remain high for an extended period and also generate clearer signals of a transmission into broader inflation persistence.
- France is to issue EUR 340bln of medium and long-term bonds next year, net of buybacks.
- ECB’s DeMarco said stronger core inflation could be grounds to act and would not exclude a rate hike in October, while the recent rise in long-term bond yields is quite worrying.
DATA RECAP
- UK Lloyds Business Barometer (Sep) 41 (Prev. 53)
2.NORTH AND SOUTH KOREA/
SOUTH KOREA//NORTH KOREA
SOUTH KOREA/USA
Trump’s $200BN Korean “Investment” Is A Gas Plant With No Customers, Eight Reactors With No Sites, And A Pipeline Seoul Calls A “Future Discussion”
Wednesday, Sep 30, 2026 – 02:00 PM
A week ago, we wrote that South Korea had finally found a home for the first slice of the $350 billion it promised Trump: a $22.3 billion, 6.3GW gas plant in Encinal, Texas, with no customers, no PPA, and turbines that may not show up this decade. That left, as we put it then, “$328 billion to go.”
That number is about to get a lot smaller, if only on paper. According to Bloomberg, at 3pm ET, Trump will announce from the Oval Office that Korea is committing $200 billion to US energy projects: eight large nuclear reactors, the Encinal plant, and the long-suffering Alaska LNG export venture, which Bloomberg earlier reported would get $54 billion of Korean backing. A White House official described it as the first tranche of projects to win approval under last year’s trade deal.
One small detail: Seoul hasn’t publicly confirmed any of it. And according to Korean press, it doesn’t entirely agree.
The math adds up… a little too well
Recall how the deal is structured. Of the $350 billion, $200 billion is upfront capital for “strategic industries,” capped at $20 billion a year, with a separate $150 billion for shipbuilding. Now add up the three projects that have been floated:
- Eight reactors: about $120 billion, per Korea’s own government briefing (six Westinghouse AP1000s and two Korean APR1400s, per Kyunghyang Shinmun)
- Alaska LNG: $54 billion
- Encinal, Texas: $22.3 billion
Total: $196.3 billion. In other words, today’s announcement would use up about 98% of Korea’s entire strategic-investment tranche in one go, with $3.7 billion left over for bubble tea or whatever. At the $20 billion annual cap, just funding these three would take roughly a decade, which is convenient for a program that runs well past the next two elections.
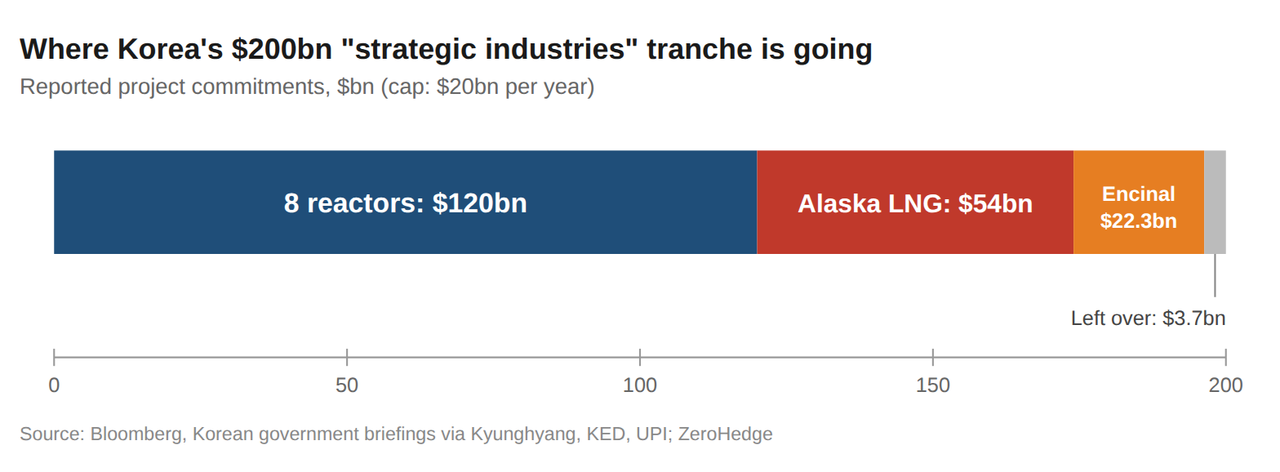
Here is where it gets awkward. In its National Assembly briefings, the Korean government listed Encinal as the only approved first project. The eight reactors and Alaska LNG were both classified as “items for future negotiation,” according to SBS and Seoul Economic Daily. The latter notes that Commerce Secretary Lutnick is leading the announcement, flanked by Alaska Senator Dan Sullivan, while Korea’s own trade minister, Kim Jung-kwan, who actually negotiated the thing, is not expected to be there.
Kim was even more explicit on the nuclear piece, telling reporters that the plan “does not mean that the nuclear power projects will immediately proceed” until final arrangements and government reviews are done. So the $200 billion headline is roughly $22 billion that Seoul has signed off on and $174 billion that Seoul is still arguing about.
The midterm pipeline
Bloomberg flagged the timing, noting that the announcement comes amid deep voter dissatisfaction with the cost of living and the risk that Republicans lose Congress in November. Goldman’s Alec Phillips relaunched the bank’s US Election Monitor this morning (full note available to pro subs) and his numbers are not great for the GOP: Democrats lead the generic ballot by 8.5 points, prediction markets give them a greater than 90% chance of winning the House, and better than 60% odds of taking the Senate. Phillips does caution that Senate polling has historically overstated Democratic performance at this stage, especially in red-leaning states.
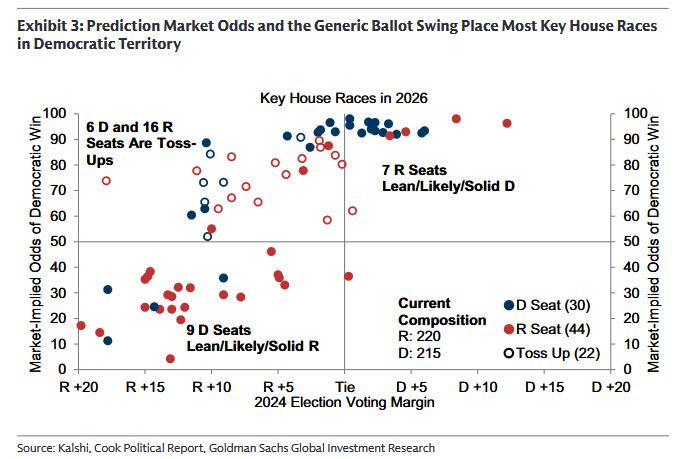
Which brings us to Alaska. Per Seoul Economic Daily, Democrat Mary Peltola leads incumbent Sullivan 46.5% to 45%, with local fuel prices a big issue. Korean commentators are openly calling the Alaska LNG announcement a “midterm card.” As for whether a 740-mile pipeline that hasn’t reached FID will lower anyone’s gas bill before November 3, we had a thought on that last night:
Recall that the whole point of Alaska LNG is to ship North Slope gas to Asian buyers, with some diverted for in-state power. When we last covered the project in October 2025, it was a $44 billion venture, and Asian buyers were quietly worried the costs were too high. Korea’s reported $54 billion commitment alone is now bigger than the whole project’s price tag was a year ago. That is some impressive cost inflation, even by pipeline standards. Glenfarne has signed preliminary deals with importers but still hasn’t taken FID; Korea’s money is supposed to unlock it.
To be fair to Seoul, the timing isn’t crazy from an energy-security perspective. Goldman’s Samantha Dart wrote after Gastech last week that corporates across the LNG chain expect the Iran status quo to persist, and that without a meaningful recovery in Persian Gulf exports this winter, JKM will likely reach $35/mmBtu by year-end, versus a $24.85 base case. A supply source that doesn’t pass through Hormuz has obvious appeal for Asian importers. It’s also telling that KOGAS just approved roughly $1.26 billion for LNG Canada Phase 2, which is a project that actually exists. Meanwhile Goldman’s John Mackay listed “higher costs for new US greenfield capacity” among the key debates heading into Gastech, and few greenfield projects are more greenfield than a 740-mile trench across the Arctic permafrost.
Eight reactors, zero sites
The nuclear piece is the biggest part of the package and the least developed. What we know:
- Structure: $120 billion for eight units in three phases: two AP1000s first, then two APR1400s plus two more AP1000s, then two final AP1000s. A six-month gap is targeted between the Phase 1 and Phase 2 EPC contracts, and both sides agreed only to make “reasonable efforts” to keep to it (UPI).
- Sites: None yet, though talks favor federal land.
- Lead times: 54 months for reactor vessels, 57 months for steam generators and 65 months for coolant pumps. Seoul has floated up to $10 billion by year-end for advance equipment purchases, pending National Assembly approval, and DOE has separately authorized $17.5 billion in conditional loans for long-lead AP1000 gear.
- Per-unit cost: $15 billion per reactor. That’s ambitious given Vogtle’s two AP1000s came in north of $30 billion, but at least it’s within shouting distance.
The real fight has been over who gets to design and own what. Goldman’s Seoul trading desk flagged on September 16 that the core disagreement delaying the talks was the nuclear leg, with the US “reportedly showing reluctance toward constructing Korean-designed reactors on its soil,” and not keen on handing Korea voting rights in Westinghouse. That friction shows up in the numbers: a day earlier the same desk reported Seoul wanted at least a 15% stake in Westinghouse plus board seats. By last week, KED had it at about 7%, and Kyunghyang reported a 5–10% target, with the government insisting voting rights “could be obtained even at” that level. We’ll see.
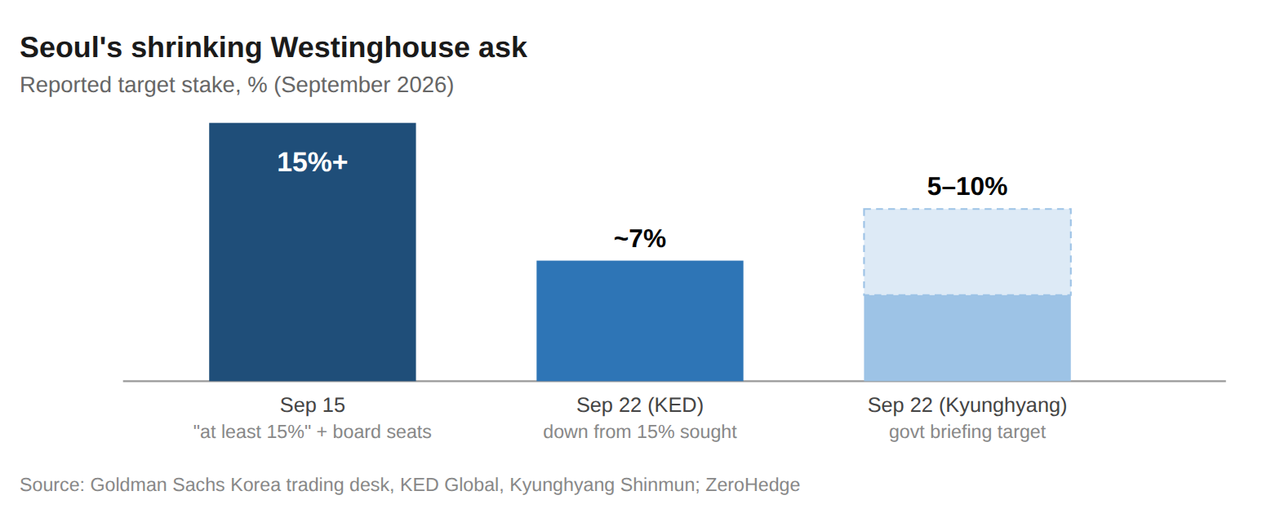
This is a saga we’ve been tracking for a while. Back in November 2025 the administration declared it a “national emergency” and said it would buy 10 large new reactors. By March, slow progress had pushed the administration to start talking with Westinghouse’s rivals. In August, the plan became a Korean problem:
And by Labor Day, “up to eight” reactors with a price tag of $120–130 billion. So in about ten months we went from 10 reactors for $80 billion to eight for $120 billion, which is the most nuclear thing about this whole story.
Longer term, the more interesting action may be in smaller units. Goldman’s Yuichiro Isayama noted this month that Japan’s third tranche under its own $550 billion pledge is likely to focus on SMRs (after about 10 units were already assumed in the second), and flagged Japan Steel Works (Buy) as the big winner because SMR primary components still need the same large forgings as full-size reactors. As we’ve argued for a while, modular reactors are the only long-term solution to the AI power crunch; Tokyo seems to agree, while Seoul is betting on the gigawatt-scale designs that made Vogtle famous for all the wrong reasons.
Who buys all this power?
As a reminder, Korea’s own case for Encinal assumes the power “can be sold to Big Tech at premium prices,” per a local report flagged by Goldman’s Seoul desk. The demand is certainly there. Goldman’s Power Up America team projects AI infrastructure capex of $1.3 trillion in 2027 and $2 trillion in 2028, which it says corresponds to 35GW and 57GW of new data center deployments, adding that “the physical grid could emerge as the ultimate constraint.” Against that, Encinal’s 6.3GW plus roughly 9.5GW of reactors that won’t be online until well into the 2030s is a rounding error… if it gets built at all.
And then there’s the behind-the-meter question. As we noted last week, Goldman’s Carbonomics team raised its outlook for BTM generation at data centers from 40GW to 67GW by 2030. If hyperscalers increasingly build their own on-site power (which we have long argued should be mandatory), then grid-scale plants that were financed on the premise of selling premium power to Big Tech may find Big Tech has already left the room. And with large gas turbines effectively sold out through 2030, Encinal and the BTM crowd are fighting over the same equipment anyway.
Bottom line
Japan went first in February with a $36 billion opening tranche, led by an Ohio gas plant whose sponsor, SB Energy, has since delayed its IPO. Korea is now doing the same thing, just bigger and faster: one gas plant Seoul has agreed to, $174 billion of projects it still calls “future discussion,” and a headline number that will do a lot of work between now and November 3.
Last week we said there was $328 billion to go. After today, Trump will say $150 billion. Seoul will probably say it’s still $328 billion. For once, both may be right.
END
JAPAN
JAPAN//USA
AI
Focus Turns To Japan As Source Of Relentless Treasury Selling
Japan has emerged as a key focus for U.S. Treasury market pressure in 2026, primarily due to large-scale yen interventions that appear to have involved sales of foreign securities (including Treasuries), alongside reduced appetite from Japanese private investors amid rising domestic yields.
bloomberg.com
Japan remains the largest foreign holder of U.S. Treasuries (around $1.10–1.15 trillion as of mid-2026 data, down from higher levels earlier in the year/peak periods). Official holdings have declined notably: TIC data and related reports show reductions of tens of billions in recent months (e.g., ~$135 billion from February through July in one analysis; further drops tied to August activity). Foreign securities in Japan’s reserves fell by a record ~$87.8 billion in August alone, closely matching the scale of intervention.
japantimes.co.jp
Why the selling?
- Yen defense via intervention: The yen weakened sharply (testing multi-decade lows near 160–164 per dollar). Japanese authorities conducted record interventions, spending the equivalent of ~¥15.4 trillion (~$98–99 billion) in the period through late August (partly coordinated with the U.S., the first joint action in years). Earlier waves also occurred. Funding this typically involves selling liquid foreign assets from reserves (estimated ~70% in Treasuries, often shorter-dated for liquidity). Reserves overall dropped sharply (e.g., record ~$80–95 billion declines in key months). bloomberg.com
- Domestic yield rise and capital repatriation: Japanese government bond (JGB) yields surged, with the 10-year crossing 3% for the first time since the mid-1990s. This narrows the yield gap with Treasuries and makes domestic bonds more attractive. Japanese investors (including institutions) have been net sellers of overseas debt (e.g., ~¥3 trillion / ~$19 billion year-to-date through late August in one report; larger quarterly private sales earlier). Pensions and others are increasing domestic allocations. reuters.com
- Broader context: Higher U.S. yields, fiscal concerns, and carry-trade dynamics amplify sensitivity. U.S. officials (including Treasury Secretary Scott Bessent) have pressed Japan on fiscal restraint, BOJ rate policy, and stability partly to limit spillover risks from Japanese selling or reduced buying into U.S. yields. reuters.com
Sales are not a wholesale “dump” of the entire stockpile—Japan still holds a massive position, and interventions can also draw on deposits, repos (e.g., FIMA facility), or other liquidity without always liquidating long-term bonds. Private flows reflect portfolio rebalancing more than forced official liquidation. Still, the scale of intervention-linked activity and the shift away from being a reliable marginal buyer have contributed to upward pressure on longer-term Treasury yields at a time when they were already elevated.
wolfstreet.com
Markets and policymakers continue to monitor Japanese reserve data, TIC releases, JGB yields, yen levels, and any further BOJ/fiscal signals, as sustained reduced demand or additional sales from such a large holder can influence global bond markets even if orderly. Data lags mean exact official Treasury sales versus other foreign securities or valuation effects are inferred rather than always confirmed in real time.
END
3. CHINA
CHINA/
AI
China Underwhlems With First Mini Stimulus In Two Years Seen “Securing GDP Target, Not Much More”
China’s first coordinated “mini stimulus” in about two years—announced after markets closed on Tuesday, September 29, 2026—is widely seen as targeted support aimed mainly at securing the official GDP growth target of 4.5%–5%, rather than delivering a broad economic revival.
bloomberg.com
Key MeasuresGovernment agencies rolled out a package of fiscal and monetary steps following a State Council meeting the day before that pledged “a package of practical and effective additional policies” and stronger counter-cyclical adjustments. Main elements include:
reuters.com
- Mortgage interest subsidies for eligible first-time homebuyers (starting October 1, on a one-year trial basis): an annual 1 percentage point subsidy for up to five years on new commercial mortgages, capped at 1 million yuan (~$149,000) of principal per household. Homes must be ≤120 square meters and cost ≤1.5 million yuan (~$224,000). This is China’s first nationwide measure of this type and is expected to mainly help lower-tier cities. reuters.com
- People’s Bank of China (PBOC) actions:
- Cut the one-year pledged supplementary lending (PSL) rate by 25 basis points to 1.5% (from 1.75%), and broadened PSL support for infrastructure networks (water, power grids, computing/communications, urban pipelines, logistics).
- Raised relending quotas: +200 billion yuan for sci-tech innovation and technological upgrading (to 1.4 trillion yuan total); +500 billion yuan for agriculture and small businesses (to 4.85 trillion yuan); +300 billion yuan for private enterprises (to 1.3 trillion yuan). reuters.com
These steps form the biggest coordinated stimulus effort since around September 2024. Analysts (e.g., Pantheon Macro) have described it as the largest in two years and aimed at getting growth back on track.
tradingview.com
Context and AssessmentChina’s economy has been losing momentum. Growth slowed to 4.3% in Q2 2026, with industrial output, retail sales, and investment weakening further into Q3, while the property sector remains in a prolonged downturn. The annual target is already lower than prior years.
reuters.com
Bloomberg and other coverage characterize the package as designed to keep growth on target rather than spark a broad revival, leaving underlying demand weakness largely unaddressed. Measures are targeted (property support focused on affordable/lower-end homes, plus directed credit for tech, infrastructure, SMEs, and agriculture) and stop short of large-scale broad fiscal expansion or aggressive benchmark rate cuts. Constraints include limited room for deeper monetary easing amid US rate dynamics, elevated debt levels, and bank margin pressures.
bloomberg.com
Local governments may also accelerate use of remaining/unused bond quotas, which could increase supply in Q4. Markets and investors have reacted warily so far, with skepticism that the steps will produce a sustained boost without deeper structural reforms (e.g., stronger social safety nets to support consumption).
tradingview.com
In short, the “mini stimulus” raises the odds of hitting the 2026 GDP target but is not viewed as a game-changer for China’s multiyear challenges of weak domestic demand and the property overhang. Further measures remain possible if data stays soft.
END
4. EUROPEAN AND SCANDINAVIAN COMMENTARIES PLUS NATO
EUROPE/
The End of Europe
by GeoVest
Tuesday, Sep 29, 2026 – 10:14
I sincerely believe that banking establishments are more dangerous than standing armies – Thomas Jefferson
Europe is failing. Europe’s leadership is preparing for war to cover their mistakes of the past fifty years and the people aren’t having it. Europeans don’t want war and to date, Russia has been unwilling to be provoked into a wider conflict.
It’s obvious to anyone who knows anything about military campaigns that Russia lacks the logistical capacity to invade Western Europe. Their domestic semiconductor fabs are 25 years behind the West which means they are unable to fight a modern war. Besides, Western Europe is a hollowed out economic shell that offers no advantages to Russia and innumerable headaches.
Northern Europe has outstanding defensive militaries, backed by NATO. Eastern Europe has Poland with their massive, modern army which is more than capable of blunting Russia if it somehow gets past Ukraine. Turkey’s massive army sits on Russia’s flank.
It would take an extraordinary level of credulity to paint Russia as a military threat that warrants mass mobilization of Europe’s limited industrial base. Regretfully, it’s not stopping them.
All Wars Are Bankers Wars
War is a racket – General Smedley Butler (US Marines)
Europe is run by bankers and politicians; every other economic power center has been marginalized. Green energy policies, pushed by bankers and politicians, have destroyed domestic energy production in Germany and Britain and have left the regional economy dependent on high-priced, imported natural gas, and ultra-high-cost renewable energy. The result is a regional economy that can no longer compete on world markets.
The German Mittelstand, the economic rock that Europe is built on, has been decimated by these disastrous decisions. The Mittelstand refers to the small, private or family-owned businesses that represent the excellence of German engineering and manufacturing and employs roughly 60% of Germans.
These businesses are being tasked with shifting from domestic products to military products, to fight a war that is unlikely to start. Many of their industrial inputs such as natural gas for chemicals and metallic inputs were formerly sourced from Ukraine and Russia but now come from new and more expensive sources.
The Mittelstand, already decimated financially, needs to re-tool and find new input sources, which will require massive capital investment. To make this happen, Ursula von der Leyen, President of the European Union, has proposed using €10 trillion from household bank deposits to fund this capital investment, claiming these deposits are “idle” and “lazy”.
The people who destroyed the European economy in the first place want the voters to turn over their savings to fund a fool’s errand. They want to fight a war that has no reason to be fought other than to bail out bankers and politicians.
The scary thing is that European leaders would rather risk destroying the world than loosen restrictions on the pan European economy. They can’t think of any better ideas than World War III. It’s little wonder that voters in Germany, Britain, and France want the current leadership voted out.
There is no appetite for war in Europe. The bankers and the politicians have failed the European people and will not be allowed to destroy the world.
Whither the Euro?
It’s the invincible arrogance of Europe’s elites that gets me. These are people who have seen the euro collapse. These are people who are presiding over a migration crisis on their borders, and yet do they ever acknowledge that they need to change? No. They say that they need more integration, more of our money, more control over this country – Michael Gove
The euro was created to compete with the US dollar in global trade and ultimately replace it as global reserve currency. The euro was initially introduced at $1.18 for each €1. Over 27 years, it has remained roughly the same – presently $1.14 per euro.
Yet at the start of the GFC or Great Financial Crisis of 2008, the euro hit just under $1.6 per euro when it appeared that the Federal Reserve was losing its collective mind, only to fall dramatically since that time. That was Europe’s opportunity to replace the buck and they failed. They won’t get another chance.
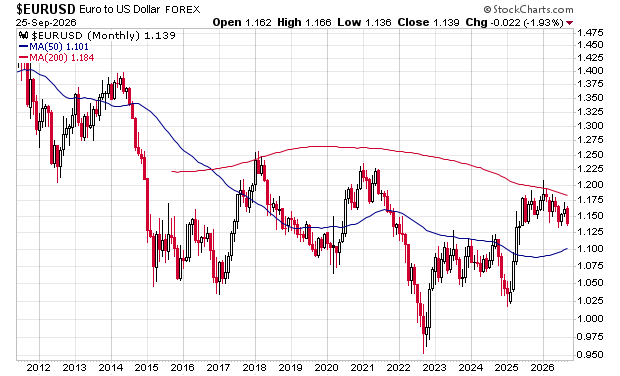
Von der Layen’s plan risks driving domestic savings out of the Eurozone into other currencies such as the dollar and yen. If this happens, the value of the euro in currency markets will fall, making it much harder for the remaining European manufacturers to shift to arms production. Inflation is already decimating European consumers, a drop in the euro would accelerate an already untenable economic situation forcing consumer inflation even higher.
The timing is yet to be determined but the conditions have been set; the euro is going to break, not the US dollar. Within ten years, Europe will be irrelevant as an economic bloc and the euro, if it’s still around, will resemble the Indian rupee.
Twilight of the Central Bank Model
The worst evils which mankind has ever had to endure were inflicted by bad governments – Ludwig von Mises
Central banking is a British invention and it started with the Bank of England in 1694 although it can be argued that the Knights Templar represented the first central bank in history. Their power was seemingly destroyed in 1307 by King Philip IV of France. I believe the power of the European central banks and their offshoot, the Federal Reserve Board, are presently facing an existential fight.
At the heart of central banking is the process of money creation. National governments borrow from central banks and pay interest on that money. Central banks, which are largely private institutions, make money by creating more money. They are incentivized to expand money supply.
My formative years in the investment business were built on the belief that central banks needed to be independent to prevent runaway inflation. The truth is the opposite.
Central banks loot economies and destroy them. We can see this in Britain, France and Germany where prices have been driven too high to compete. That’s when industrial activity is exported to the lower cost venues, hollowing out the economies that supported borrowing in the first place.
The Fed is in the process of destroying the US economy. The country is littered with former industrial cities and towns, a testament to the destruction wrought by bankers.
The chart below shows US government debt over my lifetime. Everything has been inflated and monetized and now we’re left with the financial wreckage of excess debt and a hollowed out industrial base.
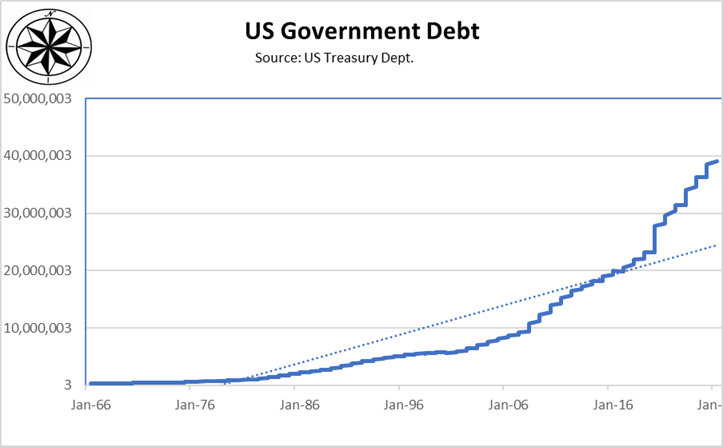
It was both political parties. JFK issued silver certificates to counter the Fed; he was shot. Ronald Reagan was exploring a return to a gold standard, not coincidentally, he was shot. From George Herbert Walker Bush through Joe Biden, US Presidents ceded power to the Fed incrementally until we got to our present condition.
M1 money supply has grown by 80% since 2020. This represents cash and checking and it is the reason consumer prices are much higher. The chart above shows how that money got there. It also shows why our capital markets have remained elevated. It’s not sustainable.
The only part of the yield curve that global central banks can impact is the long end – 7 years and up. We can see the spike in 10-year bond yields below. This doesn’t indicate rising inflation expectations; it represents the death throes of global central banks desperate to derail the efforts of the US to drain dollars out of global money markets.
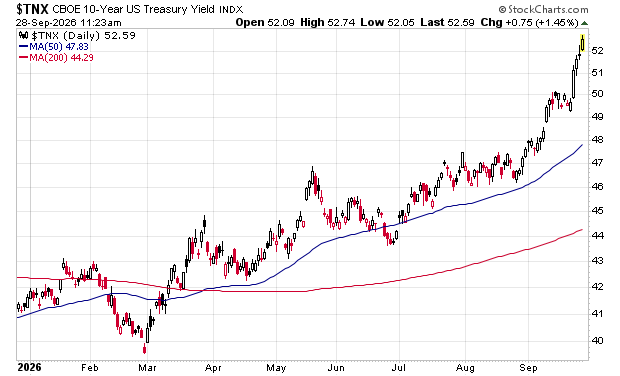
The inflation damage has already been done during the years 2020 through 2024. US dollars are being drained out of the global economy and re-invested in the US. The US is effectively sucking the lifeblood out of the global central banking system. I view the rise in long term bond yields as a generational buying opportunity because interest rates will be forced down to 0% in the US before long.
Eurodollars
Never interrupt your enemy when he is making a mistake – Napoleon Bonaparte
I wrote a piece called the Main Event that discusses the draining of the Eurodollar market in detail. Here’s a link: https://geovestadvisors.com/the-main-event/ The Cliff Notes version is that the abundance of oil and natural gas developed in the US shale fields has resulted in the reversal of energy flows from into the US to out of the US. Inversely, this redirects US dollars from moving out of the US to moving into the US, leaving global central banks bereft of US dollar assets.
US dollars are being drained out of Europe and Europe’s international banks in London, Paris, Zurich, Amsterdam, and Frankfurt. The war on the international drug trade by the US military is destroying the profitability of European banks which regretfully, rely heavily on this ugly trade.
The City of London and UK Crown dependencies launder an estimated 40% of the world’s illicit trade. Banks in Paris, Rome, Zurich, and Amsterdam also feed at that trough. By cutting them off from this lifeblood, these bad actors are going to be sharply curtailed in power and global influence. Central banks in Europe are rapidly losing the ability to move markets around the world.
Globalism was created by the Bank of England and other European Central Banks but those banks are being marginalized in global matters, particularly since their regional economies are fractions of their former relevance. The pan European economy has been over-harvested by bankers and politicians as discussed previously.
Food and energy are traded in US dollars and the European banking establishment is watching those dollars head back to the US. Every oil tanker or LNG tanker that docks in the Port of Antwerp drains dollars from European banking coffers. Without dollars, European banks decline in relevance.
European central banks have relied on hidden swap arrangements with the US Federal Reserve Bank to supply them with US dollars when they are short. I expect increased scrutiny of these arrangements by the US Treasury going forward and if those swap arrangements are curtailed, the euro is going to drop like a stone versus the US dollar.
Here’s the same chart from above with some lines marking important levels. If the euro falls convincingly below parity with the US dollar, it’s game over. The Europeans have relied on their extraordinary influence with the US Congress for 200 years but that influence is rapidly waning.
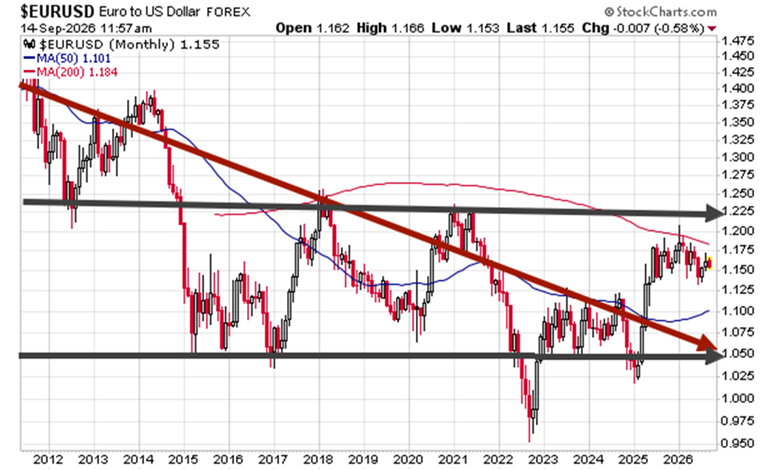
As Europe goes, so too goes globalism and the central bank model. This is why they need to drag the world into a war. It’s their final lifeline.
In politics, stupidity is not a handicap – Napoleon Bonaparte
Europe isn’t going to disintegrate; it will cease to matter. Eastern Europe, especially Poland and the Czech Republic, as well as Scandinavia have bright futures. Britain, France, Germany, Italy, and Spain have serious problems. The money has run out for those trust fund babies
The US has been hampered by European influence since the beginning. Presidents such as Jefferson, Jackson, Lincoln, McKinley, Kennedy, and Reagan have tried to limit European influence in banking and policy but the connection was too strong.
As the US melting pot integrates the world into our hybrid genetic mix and as European bureaucrats destroy what’s left of their economy, the connection is finally breaking. Good riddance! Without the US, the global central banking model finally fails and with it, the artificial asset inflation that is preventing the US economy from renewing itself.
The financialization cycle is over after 125 years. The future is about re-building a destroyed industrial base, not about trading crypto and Mag 7 stocks. If you’re interested in learning more, visit us at https://geovestadvisors.com/ and give us a call.
Philip M. Byrne, CFA
END
EUROPE:
Bernstein Puts Timeline On When EU Rearmament Supercycle “Goes Boom”
Wednesday, Sep 30, 2026 – 05:45 AM
Readers by now know how we’ve laid out the looming rearmament supercycle in the West colliding with the “own the bottlenecks” theme, as resource nationalism makes industrial metals and rare earths scarce because of Beijing’s export restrictions.
Adrien Rabier, Bernstein’s equity analyst covering European aerospace and defense, penned a note on Tuesday explaining why the European defense rearmament cycle remains a top investment theme and even outlined a timeline.
In a report titled “European Defense: Beyond the order boom,” Rabier said EU defense firms are set to enter a massive demand-driven cycle for new weapons.
Here’s the timeline in three phases:
Stage 1: New paradigm (2022-2026).
The first stage, following the invasion of Ukraine, was characterized by rapid order collection. It drove multiple expansion across the sector, in anticipation of faster growth. The stocks re-rated from 9x EV/EBIT (-30% discount vs. SX600) to 15x currently (+17%). Exposure to the best geographies (Germany) and the quickest growth segments (short-cycle) were the most important drivers of performance.
Stage 2: Re-Arming Europe (2026-2030).
The second stage marked the transition from an order-driven performance to execution-driven, as backlogs became rich across the sector. Exposure to structurally attractive product categories will remain the most important factor, in our view. We expect the narrative against short cycles products, legacy weapons, and Ukraine-related demand to intensify. Our “new warfare” basket is up +14% YTD, vs. the “old warfare” basket down -34%. We expect this gap to keep widening. We see few positive catalysts for the sector, and therefore favor self-help stories. We expect investors to focus increasingly on the exit multiples, as we head toward Stage 3.
Stage 3: Normalization (2030+).
After the re-arming phase, we believe European military budgets will normalize near 3% of GDP. European Defense should then return to a GDP+ growth and ~12% EBIT margins sector, close to the Index’s average.
Rabier’s key message is that investors will reward companies capable of converting backlogs into profitable deliveries:
With all players now virtually benefiting from very large backlogs, the ability to convert backlog into profitable growth and scale capacity efficiently will matter more. We continue to view electronics exposure as the best, because these businesses grow through volume and content share, and are easier to scale (Thales, Leonardo, BAE Systems). Some companies will also benefit from turning around parts of their businesses (TKMS, Leonardo).
Top picks:
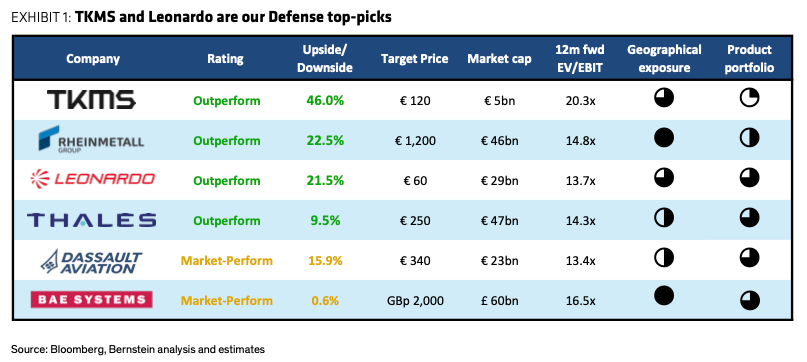
One major constraint on both Europe’s rearmament cycle and the looming US weapons buildup is access to reliable, conflict-free supplies of critical materials. Larger budgets and expanding order books can translate into weapons deliveries only if manufacturers secure the necessary copper, tungsten, and rare earths that are in scarce supply.
That makes “owning the bottlenecks” a complementary investment theme to the broader defense buildup.
END
EUROPE/ENERGY
Europe Races To Contain Energy Crisis With Patchwork Measures
Wednesday, Sep 30, 2026 – 05:00 AM
European governments are racing to blunt a fuel shock that even some analysts now refuse to forecast, as Brent crude holds near $100 a barrel and diesel prices climb across Europe.
The international oil market has been expensive for months. What has changed is the confidence of the people paid to explain it. JPMorgan told clients on Sept. 17 that, for the first time since fighting began around Iran about seven months earlier, its commodities team no longer has a baseline view of how the disruption ends.
“We simply don’t know how to model the endgame,” the bank’s analysts wrote, after several economic thresholds they once assumed would force a diplomatic off-ramp, including oil above $100 a barrel, had already been crossed.
The bank said a Brent price near $90 would have been consistent with known supply and demand in September. Futures instead traded around $100 and higher as traders priced the risk of further losses that no one can yet measure. By Monday, front-month Brent was still hovering near $99 a barrel.
Inventories are doing little to cushion the blow. The U.S. Energy Information Administration has said prices are likely to stay elevated until Middle East oil trade is restored and stocks can be rebuilt. The International Energy Agency’s September report put the scale of the drain in starker terms: observed global inventories fell another 95 million barrels in August, taking the cumulative draw since February to 507 million barrels, or about 2.8 million barrels a day. World oil supply is now projected to average 100.7 million barrels a day in 2026, down 5.7 million from a year earlier.
Diesel shortages are acute
In some countries, such as Hungary, there is a major imbalance in terms of available energy sources. Crude held in strategic storage remains ample, but diesel is quickly running out. Data from the Hungarian Hydrocarbon Stockpiling Association show gas oil stocks at 520.3 kilotons at the end of January and about 390 kilotons at the end of both July and August. That thinner diesel cushion matters in a country where more than 1.3 million passenger cars run on the fuel and the regional market is competing for the same scarce imports.
Pump prices have already moved. Official and commercial trackers put Hungarian diesel around 701 forints a liter in late September on some official series and closer to 730 forints on daily station averages – well above the roughly 593 forints recorded at the end of June. The original worry in Budapest was not whether prices would rise, but how quickly 800 forints would stop looking like a distant ceiling.
That speed is not a mystery to central bankers. Bank of Slovenia research covering euro-area data from 2005 through 2026 found that a 10% rise in Brent lifts pretax diesel and gasoline prices by about 6.5% and 6.2%, respectively, over the longer term. A large share of the increase shows up at stations within the first two weeks – faster than the physical chain of shipping, refining and wholesale delivery would suggest.
The European Central Bank has reached a similar conclusion and added an unwelcome twist: refinery margins can amplify the shock. During the spring spike, Brent briefly reached $138 a barrel while diesel at the refinery gate jumped to $197. ECB staff later estimated that refining margins were contributing about 41 euro cents a liter to euro-area retail diesel in mid-September, and they told reporters those diesel margins may not peak until October.
The way down is slower than the way up. Taxes, refining and transport costs, inventories, margins and local competition all delay relief when crude finally eases. That asymmetry is why governments are acting now, before higher fuel bills work through freight, food and services and lift broader inflation.
Europe-wide crisis
The policy dilemma is the same from Lisbon to Warsaw: protect households and trucking firms without writing a blank check for fossil-fuel consumption. Europe has answered with a patchwork rather than a single rule. Some governments cap retail prices. Others cut excise taxes, sometimes below the European Union minimum. A third group aims help at farmers, haulers and other heavy users. A few still let global prices hit consumers with no cushion at all. The result is that the same barrel of oil can produce pump prices that differ dramatically at the pump across Europe.
Here are just a few examples of what Europe looks like in this regard.
- Austria has been running a mineral-oil tax cut of 1.9 euro cents a liter into the end of September.
- Belgium has implemented an official price ceiling.
- Croatia cut diesel excise duty by another 3 cents, taking it 10 cents below the EU floor; Zagreb says the average diesel price is 1.91 euros a liter instead of 2.26 euros without the intervention.
- Cyprus is offering an 8.33-cent discount through Nov. 30.
- Luxembourg is absorbing 5 cents of the pump price from July through December.
- Malta is using direct state aid to keep prices below the euro-area average.
- Portugal decided on Sept. 17 to recycle extra value-added tax receipts from more expensive fuel into tax relief worth about 1.3 billion euros through year-end.
- Slovenia posted official maxima of 1.748 euros for gasoline and 2.012 euros for diesel in the week of Sept. 22-28.
- Spain has kept an excise cut below the EU minimum through Sept. 30.
- Italy reduced and capped diesel duty into early October.
- Montenegro and Serbia combine retail caps with lower excise taxes.
Targeted aid is running in parallel
- Greece extended a 10-cent-a-liter diesel subsidy into October and is preparing a heating-oil package.
- France steered relief to agriculture, high-mileage workers and construction rather than a blanket cut.
- Ireland is rebating duty for commercial haulers and bus operators.
- Spain added a 402 million-euro program for truckers on top of its general tax reduction.
- Italy is offering carriers a tax credit for earlier extra costs.
Larger packages are still moving through parliaments
Germany will cut energy tax by 14 cents a liter from Oct. 1 through year-end, about 17 cents once lower VAT is counted, in a 2.5 billion-euro package.
Chancellor Friedrich Merz said drivers who depend on a car every day “are reaching their breaking point.”
Berlin is also talking with the oil industry about a temporary price cap modeled on Luxembourg or Belgium, aimed at Jan. 1, 2027.
The Czech government will restore a station-margin ceiling from Oct. 1, cut diesel duty to the EU minimum and cap retail margins at 2.50 koruna a liter.
Poland has floated a 60% levy on oil companies’ extra profits to finance about 4 billion zlotys of price relief, though the plan faces parliamentary and constitutional hurdles.
The International Energy Agency has described the response as global, not merely European. In a matter of months, the number of countries applying fuel subsidies rose from 16 to 38, and the number cutting energy taxes rose from 40 to 57. Pew Research Center, drawing on IEA tallies from mid-June, counted 113 countries that had taken at least one energy-cost measure after the Iran war, including tax changes in 55 countries and fuel subsidies in 32. The agency’s own warning is implicit in those numbers: governments are treating the symptom at the pump because they cannot reopen the Strait of Hormuz from a finance ministry or end the war in Ukraine.
END
FRANCE
FASHION!! MY GOODNESS!!
How Do You Say “What The Actual F**k” In French?
Wednesday, Sep 30, 2026 – 06:30 AM
Authored by Steve Watson via Modernity News,
Paris Fashion Week is no longer in the business of clothes. It is in the business of humiliation. The Spring/Summer 2027 season opened in the French capital this week as a contest to see who can manufacture the most freakish garbage: outfits and makeup built to wipe out sex, wipe out beauty, and leave the human face looking like a prop from a cheap horror set.
The models are interchangeable. Rakishly thin. Ghoulish. Faces sanded into the same deformed, demonic mask. The crowd claps. The trade press calls it “prestige.” Ordinary people looking at the footage call it a dystopian freak show.
And of course, the ever present MESSAGE is in full force. In one clip, a black model in a gold gown staggers down the runway with two lifeless white male figures slung over her.
That was not a random stunt. It was the finale of The Ninety-Nine Percent, the Paris Fashion Week debut of Montreal label Matières Fécales – French for “fecal matter” – staged Monday at Place de la République. Designers Steven Raj Bhaskaran and Hannah Rose Dalton put 99 models on the square. Every one of them, Vogue reported, was a person of color.
The images that defined the show, Vogue wrote, were the last two looks: “two young Black models carried Sarah Sitkin’s hyper-realistic statues of well-fed old white men wearing dollar-bill blindfolds.”
FashionNetwork described the close as two models – one in a white single-button suit, one in a gold lamé gown with a train – “each staggering beneath the weight of mannequins portraying billionaires, hoisted on their shoulders.”
Bhaskaran framed it as liberation. “This one is for the 99%,” he told Vogue. “It’s taking the source of power from last season and giving it to the people that we want to empower.” In a longer note he added: “Ninety-nine models of colour and ninety-nine looks by a designer of colour. The casting wasn’t just a creative choice; it reflects all the people I grew up with in social housing.” He called Place de la République “a place of revolution” and said it was “perfect that the first-ever fashion show” there was “organised by a group of immigrants like us.”
The previous Matières Fécales collection, The One Percent, had already gone in for dollar-bill masks over the eyes, “guilt gloves” of white lambskin with bloody palms, and prosthetic faces with blacked-out eyeballs that Times Now described as “almost devilish.” This week’s sequel just swapped the sermon.
Last season the house dressed the rich as demons. This season it dressed “the 99%” as gods and hung the rich, white, and male off their backs like carcasses. The industry called it a ‘protest’.
Imagine the outrage if the imagery were reversed.
Paris is the perfect setting for it. The city that once stood for light, proportion, and a civilisation sure enough of itself to invent haute couture has spent decades deleting the culture that made the place matter.
Mass migration and the official cult of modernity have turned whole districts and the banlieues into parallel societies while the old French capital is kept on as a backdrop for visitors.
Interior ministry figures for 2025 put foreign nationals at 87 percent of theft suspects and 61 percent of sexual-violence suspects on Île-de-France public transport – in a country where foreigners are about 9 percent of the population.
A runway that erases sex, beauty, and the European face is not an accident that happened to land in Paris. It is what a conquered capital stages when its elites have already decided the native civilisation is finished.
The runway was only half the story. The front row at what is still sold as the most prestigious fashion week on earth featured animal-head masks, dollar bills taped over eyes, headset hardware, nails like weapons, haircuts that look like the individuals lost a fight with a woodchipper.
This is the clientele. The clothes are designed for people who have already decided that looking human is bourgeois. Gender is sanded off. Beauty is treated as a political error.
Makeup does not enhance a face. It cancels it. Bone structure is pushed toward the same starved, hollowed, slightly wrong geometry until the models stop being women or men and become a single branded ghoul.
This is what the circuit now produces: not desire, not dressmaking, but a scavenger hunt for which house can make the human form look most cursed.
It’s a cross between the Hunger Games and a Satanic freak show.
The same starved silhouettes keep coming back. The same cadaver makeup. The same flattened sex. The same racial morality play dressed up as couture. Luxury’s ruling class has decided that the highest status signal is contempt for the thing fashion used to sell: a beautiful woman, clearly a woman, wearing something a normal person might actually want.
Beauty is not a conservative hobby. It is one of the oldest human instincts that modernity now treats as suspect. A culture that cannot stand a pretty face, a female silhouette, or a male body that is not being in some way tortured or murdered, will not stop at the runway.
It will keep going until the only acceptable look is the one that says: you are not a man, you are not a woman, you are not a people, you are inventory.
END
FRANCE
French President Macron’s Approval Rate Hits Record Low As Fuel Crisis Worsens
Wednesday, Sep 30, 2026 – 02:00 AM
The popularity of French President Emmanuel Macron and his prime minister, Sébastien Lecornu, has plummeted due to the ongoing fuel crisis, BFMTV reports, citing a poll conducted by Odoxa-Mascaret for the online broadcaster Public Sénat and regional media.
The poll was conducted last week, ahead of Emmanuel Macron’s speech on rising fuel prices.
The French president’s approval rating has fallen to a historic low of just 18 percent. That is a decrease of as much as 7 percentage points from the end of June.
At the same time, support for the French prime minister fell by 8 percentage points. Currently, 24 percent of the French consider him a good head of government.
The poll shows that 75 percent of respondents in France believe the government’s announced expansion of assistance for frequent long-distance drivers is insufficient. Sixty-two percent argue that the government should allocate more resources to solve the problem, despite France’s budget deficit.
A poll conducted for radio station RTL shows that if Marine Le Pen faced Jean-Luc Mélenchon, the candidate of the far-left La France Insoumise party, in the second round of the French presidential election, she would receive 69 percent of the vote and Mélenchon 31 percent.
The poll shows that Le Pen is well poised to crush the far-left contender.
If Marine Le Pen faced Édouard Philippe, the candidate of the centre-right Horizons party, in the second round, she would receive 57 percent of the vote and Philippe 43 percent.
In both scenarios, Marine Le Pen’s lead is larger than in previous similar polls.
For a candidate that has been convicted and attacked for years by the French establishment media, Le Pen’s turnaround is incredible.
The study also shows that in the first round, under various candidate scenarios, Marine Le Pen would come first if the election were held now, with 35 to 36 percent of the vote.
The first round of the French presidential election will take place on April 18, 2027 and the second round on May 2. The election will end 12 days before the end of Emmanuel Macron’s second and final presidential term, which ends on May 14.
The RTL poll was conducted between September 22 and 24 among a sample of nearly 2,000 people.
END
EU/GOOGLE
Google Challenges EU Orders Requiring It Reveal AI, Search-Engine Information To Rivals
Wednesday, Sep 30, 2026 – 04:15 AM
Google parent Alphabet on Monday took Brussels to court over two European Union orders that would force the search giant to open its Android devices to rival AI services and hand competing search engines access to its search data.
The European Commission issued both orders in July under the Digital Markets Act, the EU’s gatekeeper law, which Brussels says exists to ensure fair competition and prevent monopolies in tech.
“We’re appealing decisions that will force us to share people’s private search history without sufficient anonymization and weaken vital security protections on Android,” said Oliver Bethell, Google’s senior director of competition.
“People use Search for their most personal questions – from medical worries to close relationships – and mandating we share these personal queries without adequate safeguards would cause irreversible harm to user privacy.”
Google argues the data would go to unvetted businesses without users’ knowledge or consent, and that once it leaves Google’s systems, third parties could re-identify users and expose their personal lives, trade secrets, or sensitive government information. Advances in AI have made that kind of re-identification far faster and cheaper, the company adds.
As the Epoch Times notes further, the EU-enforced changes are set to kick in in January 2027.
Google’s challenges, filed in the Luxembourg-based General Court, Europe’s second-highest court, on Sept. 28, will not prevent them from taking effect unless the California company seeks interim measures to delay them as proceedings continue.
A European Commission spokesperson told The Epoch Times that the commission “takes note that Alphabet has announced that it will lodge an appeal against the Commission’s decisions at the General Court. As always, the Commission will defend its decisions in court.”
The Commission added that it should be “stressed that the two specification decisions carefully consider the integrity and security with respect to the features involved, as well as ensuring the protection of the personal data of end users.”
At the time, the commission said the first decision aimed to ensure that competitors’ AI services “can compete with Google’s own AI services, such as Gemini, by having equal access to features on Google’s Android devices.”
The aim of the second, the EU said, was to “rebalance the playing field by giving third-party search engines access to search data that only Google Search can collect at scale.”
Google’s move marks the latest escalation in the company’s long-running battle with European regulators over the scope of the Digital Markets Act.
The tech giant has already been slapped with multiple fines totaling billions of dollars in recent years after a series of European court rulings found it had breached aspects of the Act.
The targeting of Google and other American tech giants such as Apple, Meta, and Amazon by EU authorities has drawn criticism from Washington, with President Donald Trump saying in July that his administration would open a formal investigation into the EU’s trade practices, threatening new tariffs over billions of dollars in fines leveled against U.S. tech companies.
In a Truth Social post on July 24, Trump said the investigation would begin “immediately” under Section 301 of the Trade Act of 1974, which allows the president to protect U.S. businesses against unfair trade practices with tariffs and sanctions.
He accused the EU of “robbing” U.S. companies and, in turn, American taxpayers.
“The European Union is at it again and, as usual, taking direct aim at GREAT American Companies!” Trump wrote, referring to European enforcement actions over recent years against Google, Apple, Meta, and Amazon.
As yet, there have been no public revelations regarding that investigation.
END
5.RUSSIA AND ISRAEL AND MIDDLE EASTERN AFFIARS
ISRAEL/USA VS IRAN/TUESDAY NIGHT
Iran Says It Received Official US Counter-Proposal On Ending The War
Wednesday, Sep 30, 2026 – 08:25 AM
At a moment there are widespread reports that Persian Gulf exports are fast recovering, there are simultaneous emerging albeit delayed reports of new tanker attack incidents that happened Tuesday.
On apparent crude transit recovery amid continued deep uncertainty, “For now, that reduces fears of an immediate crude shortage and explains why prices can fall even though talks between the US and Iran have made no clear progress,” Simon-Peter Massabni from XS.com says. “The market’s main question is whether this faster pace of shipments can be sustained through October.”
But the UK’s Maritime Trade Operations agency has announced more vessel incidents which looked to have happened on Tuesday. Three distinct incident advisories detailing strikes on vessels within the region. The affected ships included a liquefied natural gas carrier and a crude oil tanker, both of which were reportedly impacted by unidentified projectiles – with little other details known.
We reported earlier on one of the three assaults, which involved a Very Large Crude Carrier in the Strait of Hormuz getting hit by a drone, after which a fire briefly erupted but was extinguished, and the tanker traversed on, and with no casualties.
In the meantime Islamic Revolutionary Guard Corps (IRGC) spokesman Hossein Mohebbi has proclaimed that there is a “military conflict” in the Strait of Hormuz on a daily basis but that the US is not responding.
“We have been hitting small ships and preventing them from passing for a long time, but America does not respond,“ Mohebbi told semi-official Fars news agency.
Axios late in the day Tuesday had cited “little progress” in US-Iran indirect talks, with on Wednesday an Al Jazeera correspondent saying that Washington has submitted a counter-proposal to Tehran. Here’s more from Axios which basically contradicts much of their own earlier in the week reporting:
Efforts this week by Qatari mediators to broker a diplomatic breakthrough between the U.S. and Iran have made little progress, with neither side willing to budge, according to three sources familiar with the talks. The stalemate bolsters the belief on both sides that a renewed military conflict is becoming more likely. U.S. officials think President Trump could order a return to major combat operations after the midterms.
On the counter-proposal: “So far, we have no idea what Iranian Foreign Minister Abbas Araghchi received from the US through Qatari mediators,” Al Jazeera writes. “But we know he has received a proposal and presented it to the Iranian cabinet, opening it up for discussion.”
According to more:
Iranian Foreign Minister Abbas Araghchi presented the U.S. response to President Masoud Pezeshkian at a Cabinet meeting, government spokesperson Fatemeh Mohajerani told the state-run IRNA news agency.
“We will make every effort to bring the agreement to fruition and will firmly stand up for the rights of the Iranian people,” Pezeshkian said. “The agreement must now be based on a win-win strategy.”
Some additional, though scant details:
Iranian Foreign Minister Abbas Araghchi received U.S. feedback via Qatari mediators in Doha on Tuesday on a seven-day plan aimed at building trust between Washington and Tehran, with sequencing the main sticking point, Reuters reported. Reuters said the Qatari mediators conveyed the feedback they had received from Washington on Monday, meeting Araghchi and his team on their way back from the United States.
President Trump had over last weekend made clear he he was rejecting Iran’s initial proposal for a 7-day ceasefire plan and roadmap to peace. But clearly there’s still some important messaging taking place via Qatar, and now that the Iranian officials who traveled to New York for the UN General Assembly are back in Tehran.
Qatar also feeling deep economic pain:
Al Jazeera has some solid commentary from a regional watcher on the big picture and where things stand, also as the Iranian economy is obviously taking big hits:
The United States and Iran are under intense pressure to end the conflict with Tehran’s economy reeling from expanding US sanctions and President Trump looking for a political victory ahead of midterm elections in November, an analyst says.
“Both sides are suffering pressure,” said Luciano Zaccara, an adjunct associate professor at Georgetown University in Qatar.
“Iran needs to get something in exchange for lifting the blockade [of the Strait of Hormuz]. They need the release of sanctions, they need to get money or else the economy will be totally devastated.”
The US, meanwhile, needs to “get out of this mess” in a way in which Trump can plausibly claim to have “won something”, added Zaccara.
The alarming alternative, which could be unleashed at any moment, is that either side could attempt to further bomb their way out of the standoff while seeking to impose new red lines toward getting what they want.
More Latest Developments
via Newsquawk…
- The Iranian government spokesperson said Foreign Minister Araghchi presented President Pezeshkian with a US proposal following his New York trip, which included discussions on Iran’s conditions for reopening the Strait of Hormuz, IRNA reported. This followed a Reuters report, which also highlighted that the main dispute between the US and Iran does not concern the components of the plan itself, but rather the order of operations and the stages of implementation of the seven-day framework.
- US White House is reportedly tempering expectations of an imminent breakthrough between US-Iran, Semafor reported, with a source suggesting that “the bar is being raised very high.”
- A senior source said mediators are working to return negotiations to a broader track that includes the nuclear issue, Al Hadath reported.
- US-Iran talks and efforts by mediators this week yielded little progress, raising the odds of renewed combat, while Qatar will continue efforts despite growing frustrations with both sides, according to Axios.
- IRGC aerospace advisor said Iran can sustain current missile firing rates for years and the era of attacks without response is over.
- UKMTO said that a crude oil tanker was struck on the port side by an unknown projectile in the Strait of Hormuz on September 29th. Following this, UKMTO separately reported that an LNG tanker was struck by an unknown projectile on September 29th within the Strait of Hormuz.
- An incident was reported on a plane flying from Dubai to Tel Aviv, with recent reporting suggesting that the incident was a terrorist attack, Al Jazeera reported. The report suggested that the co-pilot who stabbed the other pilot was of Omani origin
ISRAEL TBN
https://www.youtube.com/watch?v=5F81m_yh5eo
https://www.youtube.com/watch?v=dGFPqSEJkL4
END
IRAN/ISRAEL/USA
Iran State Media Says Houthis Launched Fresh Attack On Saudi Abqaiq Oil City
Wednesday, Sep 30, 2026 – 11:59 AM
Update(1159ET): While very unconfirmed at this early stage, the Houthis have reportedly attacked the Abqaiq oil city in eastern Saudi Arabia this afternoon (local), reports IRNA citing anonymous news sources. Abqaiq is at the heart of of Saudi crude processing, and it has been struck previously in the context of the Saudi-Yemen conflict. However, there have been conflicting reports, with some open-source accounts offering satellite imaging saying there are signs of a large fire at the site:
No official sources have confirmed a Wednesday attack as of yet.
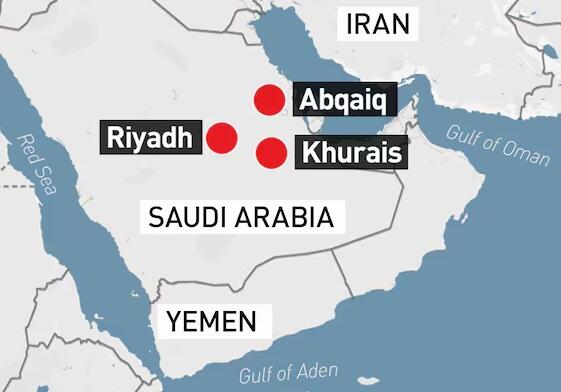
* * *
At a moment there are widespread reports that Persian Gulf exports are fast recovering, there are simultaneous emerging albeit delayed reports of new tanker attack incidents that happened Tuesday.
On apparent crude transit recovery amid continued deep uncertainty, “For now, that reduces fears of an immediate crude shortage and explains why prices can fall even though talks between the US and Iran have made no clear progress,” Simon-Peter Massabni from XS.com says. “The market’s main question is whether this faster pace of shipments can be sustained through October.”
But the UK’s Maritime Trade Operations agency has announced more vessel incidents which looked to have happened on Tuesday. Three distinct incident advisories detailing strikes on vessels within the region. The affected ships included a liquefied natural gas carrier and a crude oil tanker, both of which were reportedly impacted by unidentified projectiles – with little other details known.
We reported earlier on one of the three assaults, which involved a Very Large Crude Carrier in the Strait of Hormuz getting hit by a drone, after which a fire briefly erupted but was extinguished, and the tanker traversed on, and with no casualties.
In the meantime Islamic Revolutionary Guard Corps (IRGC) spokesman Hossein Mohebbi has proclaimed that there is a “military conflict” in the Strait of Hormuz on a daily basis but that the US is not responding.
“We have been hitting small ships and preventing them from passing for a long time, but America does not respond,“ Mohebbi told semi-official Fars news agency.
Axios late in the day Tuesday had cited “little progress” in US-Iran indirect talks, with on Wednesday an Al Jazeera correspondent saying that Washington has submitted a counter-proposal to Tehran. Here’s more from Axios which basically contradicts much of their own earlier in the week reporting:
Efforts this week by Qatari mediators to broker a diplomatic breakthrough between the U.S. and Iran have made little progress, with neither side willing to budge, according to three sources familiar with the talks. The stalemate bolsters the belief on both sides that a renewed military conflict is becoming more likely. U.S. officials think President Trump could order a return to major combat operations after the midterms.
On the counter-proposal: “So far, we have no idea what Iranian Foreign Minister Abbas Araghchi received from the US through Qatari mediators,” Al Jazeera writes. “But we know he has received a proposal and presented it to the Iranian cabinet, opening it up for discussion.”
According to more:
Iranian Foreign Minister Abbas Araghchi presented the U.S. response to President Masoud Pezeshkian at a Cabinet meeting, government spokesperson Fatemeh Mohajerani told the state-run IRNA news agency.
“We will make every effort to bring the agreement to fruition and will firmly stand up for the rights of the Iranian people,” Pezeshkian said. “The agreement must now be based on a win-win strategy.”
Some additional, though scant details:
Iranian Foreign Minister Abbas Araghchi received U.S. feedback via Qatari mediators in Doha on Tuesday on a seven-day plan aimed at building trust between Washington and Tehran, with sequencing the main sticking point, Reuters reported. Reuters said the Qatari mediators conveyed the feedback they had received from Washington on Monday, meeting Araghchi and his team on their way back from the United States.
President Trump had over last weekend made clear he he was rejecting Iran’s initial proposal for a 7-day ceasefire plan and roadmap to peace. But clearly there’s still some important messaging taking place via Qatar, and now that the Iranian officials who traveled to New York for the UN General Assembly are back in Tehran.
Qatar also feeling deep economic pain:
Al Jazeera has some solid commentary from a regional watcher on the big picture and where things stand, also as the Iranian economy is obviously taking big hits:
The United States and Iran are under intense pressure to end the conflict with Tehran’s economy reeling from expanding US sanctions and President Trump looking for a political victory ahead of midterm elections in November, an analyst says.
“Both sides are suffering pressure,” said Luciano Zaccara, an adjunct associate professor at Georgetown University in Qatar.
“Iran needs to get something in exchange for lifting the blockade [of the Strait of Hormuz]. They need the release of sanctions, they need to get money or else the economy will be totally devastated.”
The US, meanwhile, needs to “get out of this mess” in a way in which Trump can plausibly claim to have “won something”, added Zaccara.
The alarming alternative, which could be unleashed at any moment, is that either side could attempt to further bomb their way out of the standoff while seeking to impose new red lines toward getting what they want.
More Latest Developments
via Newsquawk…
- The Iranian government spokesperson said Foreign Minister Araghchi presented President Pezeshkian with a US proposal following his New York trip, which included discussions on Iran’s conditions for reopening the Strait of Hormuz, IRNA reported. This followed a Reuters report, which also highlighted that the main dispute between the US and Iran does not concern the components of the plan itself, but rather the order of operations and the stages of implementation of the seven-day framework.
- US White House is reportedly tempering expectations of an imminent breakthrough between US-Iran, Semafor reported, with a source suggesting that “the bar is being raised very high.”
- A senior source said mediators are working to return negotiations to a broader track that includes the nuclear issue, Al Hadath reported.
- US-Iran talks and efforts by mediators this week yielded little progress, raising the odds of renewed combat, while Qatar will continue efforts despite growing frustrations with both sides, according to Axios.
- IRGC aerospace advisor said Iran can sustain current missile firing rates for years and the era of attacks without response is over.
- UKMTO said that a crude oil tanker was struck on the port side by an unknown projectile in the Strait of Hormuz on September 29th. Following this, UKMTO separately reported that an LNG tanker was struck by an unknown projectile on September 29th within the Strait of Hormuz.
- An incident was reported on a plane flying from Dubai to Tel Aviv, with recent reporting suggesting that the incident was a terrorist attack, Al Jazeera reported. The report suggested that the co-pilot who stabbed the other pilot was of Omani origin.
UAE/ISRAEL
FLYDUBAI/ISRAEL
Israel says pilot tried to hijack flydubai flight to Tel Aviv that diverted, landed in Saudi Arabia
Israeli official says “major disaster avoided” after pilot stabbed his co-pilot, attempted to hijack aircraft with over 100 Israeli passengers • Israelis on board helped subdue would-be hijacker

Flydubai plane.(photo credit: SHUTTERSTOCK)
ByAMICHAI STEIN, JAMES GENN, YONAH JEREMY BOB
FollowSEPTEMBER 30, 2026 09:31Updated: SEPTEMBER 30, 2026 12:31
A flydubai commercial passenger aircraft flying from Dubai to Tel Aviv diverted to and landed in Saudi Arabia on Wednesday morning after what Israeli officials said was an attempted hijacking by one of the pilots that led to a mid-air altercation.
An Israeli official told The Jerusalem Post a “major disaster was narrowly avoided” amid growing fears that one of the pilots attempted to hijack the plane with the intention of crashing it into the ground. Additional flight crew, aided by Israelis on board the flight, managed to subdue the pilot and bring him under control, the official told the Post.
The growing assessment among the Israeli security establishment, including the IDF, Mossad, and Shin Bet (Israel Security Agency), is that the incident was intended as an act of terror.
During the altercation, the aircraft plunged approximately 4,000 meters in altitude, the official noted.
The aircraft, operating as flight FZ1073 and carrying over 100 Israeli passengers, initially transmitted squawk code 7700, indicating a general emergency, before switching to 7500, which signals unlawful interference, and later reverting to the initial code.

As the incident unfolded, the Israel Air Force (IAF) scrambled fighter jets in preparation for a possible emergency and raised its alert level, Walla reported. Prime Minister Benjamin Netanyahu had convened a security meeting with defense officials, the Post learned.
“The incident is under control, and all measures are currently being deployed in order to return the Israeli passengers safely to Israel,” the Prime Minister’s Office said following the consultations.
Israeli airspace was also temporarily closed and later reopened after the plane landed in Saudi Arabia. It landed at Prince Sultan bin Abdulaziz Airport, also known as Tabuk Airport, the airline confirmed.
The Emirati airline is set to send another aircraft to Saudi Arabia to bring the passengers back to Tel Aviv.
Defense Minister Israel Katz and IDF Chief of Staff Lt.-Gen. Eyal Zamir were also considering the possibility of dispatching Israeli military or civilian aircraft in order to bring the Israelis home, Walla learned.
Zamir canceled his planned trip to the US due to the ongoing situation. Zamir was slated to meet with US Chair of the Joint Chiefs of Staff Gen. Dan Caine and US Central Command (CENTCOM) chief Adm. Brad Cooper, the Post confirmed.
Israeli official: Pilot attempted to hijack aircraft, major disaster averted
Authorities were investigating what happened aboard the flight, including the identity and background of the pilot who allegedly stabbed the other pilot. It was reported that the altercation between the pilots, which later escalated to include Israeli passengers and the crew onboard, included the stabbing of one of the pilots.
An Israeli official said it remains unclear what the pilot was attempting to do – whether he intended to hijack the plane to Israel, crash it into the ground, or carry out a September 11-style attack. What is clear, the official said, is that he wanted to hijack the aircraft.
The official said authorities are still working to determine the identity of the pilot who carried out the stabbing. They are also investigating a suspicion that the pilot may be Middle Eastern.
The suspected terror hijacker is believed to be of Omani nationality, according to initial investigations, Israeli sources told the Post.
Yasmin Abu Kasis, whose daughter Miriam was on the flight, said that her daughter had told her that she had heard screaming and that a man took a knife, put the pilot on the floor, and that there was blood everywhere.
Israelis rushed to stop suspected terrorist from stabbing pilot, force him out of cockpit, passenger tells ‘Post’
An Israeli passenger aboard the flight told the Post that one pilot stabbed another and tried to force him out of the cockpit as the aircraft began to plunge.
The passenger said Israelis seated near the front rushed to the cockpit and fought the attacker while the plane was diving. Two other pilots seated at the back initially appeared to be in shock. “I shouted at them to run and take control of the plane,” the passenger said.
According to the passenger, the group managed to remove the attacker from the cockpit and get the two other pilots inside. One took control of the aircraft, while the other took longer to recover from the shock.
The passenger described the stabbed pilot as being in critical condition and said an Israeli dentist on board treated him and saved his life.
All passengers safe and accounted for, flydubai says
“Flydubai can confirm that flight FZ 1073 operating from Dubai International (DXB) to Ben-Gurion Airport (TLV) on 30 September experienced an incident while en route,” flydubai said.
“The aircraft has landed safely in Tabuk (TUU), and all passengers are safe and accounted for. The safety and well-being of our passengers and crew remain our highest priority. Our teams are working closely with the relevant authorities. Further updates will be issued as additional confirmed details become available,” the airline added.
It is not the first time a flight between Israel and the UAE has landed in Saudi Arabia. A flydubai flight from Dubai to Tel Aviv made an emergency landing in Riyadh in September 2025 due to a medical emergency, the Post reported at the time.
Similar incidents elsewhere have led to immediate suspensions.
In 2022, two Air France pilots were suspended after physically confronting each other in the cockpit during a flight from Geneva to Paris.
Crew members had to separate them, and one of the pilots remained in the cockpit until landing. An even more serious incident occurred in 2009 on an Air India flight from Sharjah, UAE, to New Delhi, India, when pilots and crew members exchanged blows, and the altercation spilled over from the cockpit into the aircraft’s galley. Two pilots and two crew members were suspended, and police launched an investigation.
Amir Bohbot, Eli Leon, and Reuters contributed to this report.
END
Midair Horror: FlyDubai Pilot Reportedly Stabbed, Israeli News Says Incident Treated As “Full-Fledged Terror Attack”
Wednesday, Sep 30, 2026 – 06:55 AM
Flydubai Flight FZ1073 from Dubai to Tel Aviv abruptly diverted to Saudi Arabia earlier today after a reported fight between the pilots triggered a distress alert, sources told CNN.
Flight-tracking data from Flightradar24 shows Flydubai Flight FZ1073 diverted over Jordanian airspace toward Saudi Arabia and rapidly descended 17,400 feet in just minutes around 0120 ET. Israeli fighter jets were scrambled.
According to Amit Segal of Israel’s Channel 12 News:
Following situation assessments and passenger testimonies, Israel is treating the incident as a full-fledged terrorist attack. It appears that the co-pilot repeatedly stabbed the captain. Once the attack began, several crew members and passengers managed to break through the cockpit door and subdue the attacker.
According to one senior official, the co-pilot is currently being questioned, and indications are mounting that he intended to take control of the plane and crash it with the passengers on board.
Flydubai confirmed the midair incident and said the Boeing 737 landed safely in Tabuk, with all passengers safe and accounted for. However, the airline did not specify the nature of the incident.
“Our teams are working closely with the relevant authorities,” the carrier said. “Further updates will be issued as additional confirmed details become available.”
Passengers told Israel’s Channel 12 that they heard shouting near the cockpit and an altercation inside. They also said the aircraft plunged before landing in Saudi Arabia.
END
Omani Co-Pilot Stabbed Captain, Tried To Hijack Israel-Bound Jet
Wednesday, Sep 30, 2026 – 09:58 AM
Summary:
- CNN Sources Say Co-Pilot Tried To Hijack Plane
- Omani Co-Pilot Stabbed Pilot
- Midair Horror: FlyDubai Pilot Reportedly Stabbed, Israeli News Says Incident Treated As “Full-Fledged Terror Attack”
Two Israeli sources told CNN that the Omani co-pilot aboard the Israel-bound Flydubai flight earlier this morning attempted to hijack the plane and stabbed the pilot in the process.
The outlet said:
The sources said it was not yet clear whether the intention would have been to crash the plane or to land it and take hostages.
Both the pilot and co-pilot were injured in the incident on the flight which was traveling to Tel Aviv but forced to make an emergency landing in Saudi Arabia
Added:
One of the main questions being looked into is why the flight crew included a pilot from a country with which Israel does not have diplomatic relations, the official said.
One of the pilots on Flydubai flight FZ1073 was Omani, two Israeli officials told CNN earlier. One of the officials said the Omani national was the co-pilot, allegedly the attacker in the violent incident.
Oman and Israel do not have formal diplomatic relations. It is not yet clear how the Omani pilot would have obtained clearance to fly to Israel.
A separate headline from Bloomberg cited Israeli Prime Minister Benjamin Netanyahu, who said the pilot tried to crash the plane.
The incident comes one week before the third anniversary of the October 7 attacks, when Hamas-led militants crossed from Gaza into Israel, killed about 1,200 people and took roughly 250 others hostage.
Midair Horror: FlyDubai Pilot Reportedly Stabbed, Israeli News Says Incident Treated As “Full-Fledged Terror Attack”
Flydubai Flight FZ1073 from Dubai to Tel Aviv abruptly diverted to Saudi Arabia earlier today after a reported fight between the pilots triggered a distress alert, sources told CNN.
Flight-tracking data from Flightradar24 shows Flydubai Flight FZ1073 diverted over Jordanian airspace toward Saudi Arabia and rapidly descended 17,400 feet in just minutes around 0120 ET. Israeli fighter jets were scrambled.
END
Stabbed Indian Pilot Foils Crash Plot By Crazed Omani Co-Pilot As Jet Plunged 18,000 Feet
Wednesday, Sep 30, 2026 – 09:58 AM
Summary:
- Heroic Captain Fights Off Omani Co-Pilot In Suspected Hijacking Of Israel-Bound Jet
- CNN Sources Say Co-Pilot Tried To Hijack Plane
- Omani Co-Pilot Stabbed Pilot
- Midair Horror: FlyDubai Pilot Reportedly Stabbed, Israeli News Says Incident Treated As “Full-Fledged Terror Attack”
New Details
New details have emerged about what happened on the Israel-bound Flydubai flight earlier this morning, when the co-pilot stabbed the pilot, who fought back to prevent the aircraft from being hijacked and crashed.
The New York Post cites Indian and Israeli outlets identifying the captain as Indian national Smit Machchhar, a veteran pilot with 10,000 flight hours. The Jerusalem Post reported that the suspected attacker was an Omani national who had worked for flydubai for less than a year.
Despite multiple stab wounds, Machchhar fought back, alerted the crew and released the cockpit door.
“The last moments of his energy, he used to click open the release on the door,” Doron Spielman, a spokesperson for the Israeli prime minister’s office, told Reuters.
Spielman said the attacker was striking the aircraft’s control panel violently in an apparent attempt to crash the plane.
“This is thought to be a 9/11 scenario where the co-pilot kills the pilot and crashes the plane inside of Israel with all the passengers, mostly Israelis,” one source told The Telegraph.
Flightradar24 data shows the aircraft descended 18,000 feet in 12 minutes during the ordeal.
The suspected attacker has not been publicly identified, according to the NYPost.
Notably, the attempted hijacking comes about one week before the third anniversary of the October 7 attacks.
lightradar24 shows Flydubai Flight FZ1073 diverted over Jordanian airspace toward Saudi Arabia and rapidly descended 17,400 feet in just minutes around 0120 ET. Israeli fighter jets were scrambled.
END
SYRIA
Mystery Explosions: Syria’s Recovering Gas Network Keeps Getting Sabotaged
Tuesday, Sep 29, 2026 – 06:50 PM
Syria has reported at least two acts of major sabotage against its gas infrastructure in six weeks, and it raises questions over who or what group is behind it, and what this means for future energy transit projects.
Monday evening saw a fire rage out of control for many hours at a gas pipeline between al-Shola and Deir Ezzor following a mystery explosion.
Syrian Petroleum Company (SPC), which oversees the site, called it an act of sabotage which abruptly halted gas flows from the Jbeissa gas plant to power generation stations, according to details from state-run SANA.
The New Arab writes that “In January, the SPC began pumping raw gas from the Jbeissa fields in Hasakah to the Furqlus gas plant in Homs province, with around 1.2 million cubic metres passing through the network each day to support electricity generation.”
The report adds, “Damascus has also been working to reconnect other major eastern gas facilities to the national network.”
For several years stretching through much of the last decade, Syrian cities – including the capital – have suffered intermittent and long power outages. It was especially during the tail-end of the proxy war to oust Assad that lack of fuel and electricity became a major crisis.
Damascus residents, for example, often had a mere one hour of electricity in their homes per day – if at all. Entire remote villages and towns simply proceeded with daily life amid a total and persistent blackout. This was to a large degree the result of a US-led sanctions war which in effect strangled the population. US troops had even for years directly occupied Syria’s eastern oil and gas fields, which had been crucial for meeting domestic energy needs.
But now after Jolani and his HTS jihadists seized power, and with Washington sanctions declared removed, the country is trying to restore and rebuild services.
While no group has yet claimed responsibility for sabotaging facilities in the east, it illustrates how the country is still in a deeply unstable situation.
As for the initial attack among these two latest, it happened on August 18 and involved an explosion at the Jbeissa plant’s gas export pipeline. Other sabotage examples back when the war was at its height are plentiful.
One explanation which has emerged for Monday’s incident is being reported in The National:
Hisham Al Saleh, a gas sector official at the Syrian Petroleum Company, said crews began isolating the area immediately after the fire broke out.
The local official said that the explosion was apparently caused by thieves who broke into the pipeline to steel the gas. “It seems that the theft had gone wrong. It takes a degree of professionalism to break into a gas pipeline and emerge unscathed,” the official said.
Whether sabotage or theft, it raises big questions as regional officials talk about ‘reviving’ energy pipelines crossing Syria as an ‘alternative’ to Hormuz Strait shipping, given the war-ravaged country’s longtime geopolitical importance and access to the Mediterranean. A future Iraq-Syria oil pipeline, for example, could be a prime target for unknown terror entities.
END
RUSSIA VS UKRAINE
NATO Condemns Russian ‘Nuclear Rhetoric’ Amid Kaliningrad Row
Wednesday, Sep 30, 2026 – 02:45 AM
NATO has called out what it dubs ‘desperate’ rhetoric on the part of the Kremlin which invokes potential use of strategic forces, also at a moment of growing accusations from European officials that Moscow is engaged in sabotage against EU interests and assets.
“Russia’s use of hybrid tactics is a sign of desperation. But we will not be dissuaded from our support to Ukraine,” NATO spokesperson Allison Hart said Tuesday, adding that “we [NATO] have what it takes to defend every inch of allied territory and remain strong, ready, and able to counter any threat.”
“NATO is a defensive alliance and none of our activities or exercises pose a risk to any part of Russia,” she reiterated. “We strongly denounce the threat of force, including any irresponsible nuclear rhetoric.” Hart added: “We call on Russia to end its unprovoked war in Ukraine.”
Moscow has just submitted a formal letter warning the Western military alliance concerning Kaliningrad, an exclave of Russia between NATO members Lithuania and Poland.
The letter accused NATO of an “unprecedented escalation of the military-political situation around Russia’s region of Kaliningrad accompanied by highly provocative public statements by NATO Allies’ officials.”
“This dangerous and reckless course entails high risk of the outbreak of a direct armed conflict with the possibility of Russian strikes against decision-making centers of the alliance’s member states right from the outset of the conflict,” the letter said.
NATO is incensed at this key line of Moscow’s letter:
“Russia will be ready to use the entire arsenal of forces and capabilities at its disposal, including nuclear weapons, in order to defend its territory, should NATO countries undertake any attempt aimed at isolating the Kaliningrad region from the rest of the country.”
Apparently this tense back-and-forth was initially triggered by a television show which recently aired in the UK this month.
Newsweek describes, “The statement follows a miniseries aired by British broadcaster Sky News last week, The Wargame, which traces a hypothetical Russian attack on the U.K. and how the country might respond—including by authorizing operations against the Baltic territory of Kaliningrad.”
Preview of the UK series The WarGame which started airing this month:
Meanwhile in real life serious accusations continue to fly…
On the other side of things, various diplomatic tensions and crises have been sparked over past years also when Russian broadcasters aired scenes imagining what a nuclear war and strikes on the West would look like, and charting the reach of strategic forces. In the context of the still raging Ukraine war, each side has taken these theoretical scenarios on TV screens more and more seriously.
END
RUSSIA/UKRAINE
Moscow Closes The Door: How Putin & Lavrov Hardened Russia’s Line On Ukraine In Ten Days
Tuesday, Sep 29, 2026 – 11:25 PM
Authored by Larry C. Johnson via SonarIntelligence (Sonar21),
In mid-September, the Kremlin was signaling that negotiations could resume. Putin had said the trilateral talks with the United States and Ukraine would be unlikely before the State Duma elections, but that Russia would be ready to resume contacts after them. The elections ended on September 20. Within a week, both Putin and Lavrov had shifted from conditional openness to a set of positions that make a negotiated end to the war harder to reach than at any point this year.
The trigger: September 20
The turning point was Ukraine’s drone campaign on election day. Putin said more than 1,600 drones entered the Moscow area that night, with strikes on polling stations, including one in a school he said was virtually destroyed. The chair of a territorial election commission was killed when her home was hit. Moscow Mayor Sergei Sobyanin called the raid unprecedented. According to RT, two civilians were killed in the suburbs and an oil refinery was damaged. Whatever one makes of Russian accounts of the damage, the political effect in Moscow was plain.
Putin: from “ready after the elections” to “we will think twice”
At his press conference in St. Petersburg on September 25, Putin recast the whole negotiating track. He listed a series of Ukrainian escalations: the strike on St. Petersburg’s port during the June economic forum, a campaign against Russian refineries, an attempted blockade of Russia’s Black Sea coast that he said damaged more than 100 vessels, and strikes on commercial warehouses. He said Russia had answered each one, so effectively that Kyiv is now seeking partial ceasefires in the energy sector and the air.
Putin didn’t treat those requests as an opening. He treated them as proof that Russian pressure is working. His message to Kyiv was that no provocation or escalation will get it what it wants, and that it is only making its own situation worse. Then came the key passage. The proposals, he said, remain on the table, but after everything Ukraine has done, Russia “will think twice” about how to respond. Any decision, including whether to resume the negotiations, will be based on Russia’s interests.
That is a marked change from ten days earlier. Putin didn’t close the door to talks, but he removed the implied commitment to resume them after the elections, and made any resumption depend on Russia’s own assessment of what it has to gain.
Lavrov at the Security Council: no pause “in any format”
Lavrov made the position explicit in New York on September 23. Speaking to a Security Council meeting on Ukraine, he said: “Having learned from bitter experience, we will not pause the special military operation for the period of negotiations in any format.” He said European countries wanted a pause to buy time to replenish Ukraine’s depleted arsenals. He dismissed a pre-agreement ceasefire as not serious and insisted that the goal is a long-term settlement.
The timing made it a direct rebuff. That same day, Ukraine and 51 supporters released a statement demanding that Russia accept an immediate and unconditional ceasefire so talks could begin. Its signatories included the EU and its member states, the UK, Canada and Australia. Ukraine’s foreign minister, Andrii Sybiha, noted that 14 of the 15 Security Council members had backed ceasefire proposals in one form or another, leaving Russia alone.
Lavrov went further than ceasefire mechanics. He said Ukraine would have kept its 1991 borders if the Europeans had not “engaged in their shenanigans.” That frames the loss of Ukrainian territory as permanent and places the blame on Europe. It is not the language of a government preparing to negotiate over the lines of control.
Lavrov at the General Assembly: Europe as the enemy
In his General Assembly speech on September 26, Lavrov made Europe the central threat. He said the EU is militarizing for war with Russia, and that a buildup on that scale could eventually lead to a conflict. He suggested Germany’s pursuit of military primacy could be seen as an attempt to create a “Fourth Reich.” At his press conference afterward, he argued that a European buildup must eventually be used, “because we are not planning to” attack. He called European war preparations a possible “self-fulfilling prophecy.“
The effect is to rule Europe out as a negotiating party. Lavrov has told the Europeans that they are the ones preparing a war, that their calls for a ceasefire are a device to rearm Ukraine, and that they destroyed the chance of a settlement on Ukraine’s 1991 borders. Moscow now treats only the United States as a legitimate interlocutor.
Even the U.S. channel produced nothing
After meeting Lavrov in New York, Secretary of State Marco Rubio said both Russia and Ukraine had shown interest in a limited ceasefire covering energy infrastructure and grain shipping, but admitted an agreement would not be easy. The Russian Foreign Ministry did not confirm any agreement, and Kremlin spokesman Dmitry Peskov said there were currently no conditions for moving toward a peace track, although Russia remained open to talks.
Putin’s own assessment of the U.S. relationship was cool. He welcomed the Trump-Xi talks in Washington, but said Russia’s relations with the United States had been reduced almost to zero, contrasting that with $240 billion in annual trade with China.
Pressure at sea, in the air and on the ground
The diplomatic hardening is matched by rising military pressure on three fronts at once. Moscow is not waiting for talks. It is using the interval to raise the cost to Ukraine of refusing Russia’s terms.
At sea, Russia has reimposed a de facto blockade of Ukraine’s Black Sea ports. It has not brought its warships back to Ukraine’s coast as it did in 2022; it has used missiles and drones against ports and merchant ships instead. After strikes in mid-July, including the sinking of the bulk carrier Golden Leo, shipowners and insurers pulled back, and traffic through Odesa, Chornomorsk and Pivdennyi collapsed. On September 12, Russia hit the Odesa region with cruise missiles, ballistic missiles and 129 drones, and said it struck two cargo ships at Chornomorsk that it claimed were delivering weapons. Ukraine’s acting foreign minister has accused Moscow of trying to turn the Black Sea into a “second Strait of Hormuz.” In St. Petersburg, Putin listed the lifting of the blockade among the concessions Kyiv is seeking, and made clear he is in no hurry to grant it.
In the air, Russia has intensified strikes on Kyiv and other major cities, aimed at transport, production, power, water and communications. On September 23, the day Lavrov spoke at the Security Council, hours of drone attacks on Kyiv hit railway infrastructure, warehouses and fuel stations, killing at least two people and injuring more than 30. Zelensky said Russia used large numbers of drones, including faster jet-powered models. Strikes have also hit power, water and internet networks, partially suspending water service on Kyiv’s left bank. Earlier in September, Russia struck Kyiv and southern and eastern Ukraine six nights in a row. With winter approaching, the grid is becoming a front of its own. Zelensky raised an energy-infrastructure truce with Trump at the UN; Moscow has not accepted it.
On the ground, Russian forces are attacking along the entire line of contact, and Russia is advancing while Ukraine gives ground. Ukraine’s own General Staff reported 277 combat engagements on September 24, from the Sloviansk and Kramatorsk sectors in northern Donetsk to Huliaipole in the south, with the heaviest assaults around Kostiantynivka and Pokrovsk. Russian forces took Shirokoe and Shevchenkovo in the Kharkiv region and Novoandreevka in the Zaporizhzhia region on September 14, and Olkhovatka in the Kharkiv region, within an encirclement, the next day. Every day of stalled diplomacy is another day of this pressure.
What this adds up to
Taken together, the statements of the past ten days set out a harder Russian position:
- Talks resume only on Moscow’s timetable and on its judgment of its own interests, not as the promised follow-up to the elections.
- No ceasefire of any kind during negotiations, including the unconditional ceasefire backed by more than 50 countries.
- Ukraine’s requests for partial truces are treated as evidence that Russian pressure is working, not as openings.
- Europe is cast as the aggressor, excluded as a partner, and blamed for the loss of Ukraine’s territory.
- Military pressure rising on every axis: a de facto blockade of Ukraine’s ports, intensified strikes on Kyiv’s infrastructure, and assaults along the entire front.
The direction is clear. In mid-September, Moscow was talking about when negotiations would resume. By September 26, it was talking about whether it wanted them at all, and on what terms
I discussed prospects for a Russia – NATO war with Lena Petrova:
Nima and I discuss Iran’s latest strikes on ships in the Strait of Hormuz:
Sulaiman and I discuss, among other things, confirmation that the reports of additional US Navy and Marine casualties were the result of Iranian strikes on US vessels:
6/.GLOBAL ISSUES, COVID ISSUES, VACCINE INJURIES/HEALTH ISSUES
GLOBAL ISSUES
COVID VACCINE INJURY REPORT: DR. MARK CRISPIN MILLER
In memory of those who “died suddenly” in the United States and worldwide, September 21-28, 2026TV actor Dennis Haskins; rockers Peter Byrne, Chuck Varga; blues guitarist Carvin Jones (60, C); wrestlers PAC, Jose “Jacobs” Trujillo (30); US Figure Skating official Elliot Schwartz; & moreMark Crispin MillerSep 30     READ IN APP  A survey of the likely global toll of COVID “vaccination,” based on the reports collected by our worldwide team of researchers this past week.Note: These reports are not arbitrarily included. For a list of the criteria we use, see this footnote.¹To help support our work, consider subscribing or making a donation.UNITED STATES (118)Chattanooga native Dennis Haskins, ‘Saved by the Bell’ principal, dies at 75September 28, 2026  CHATTANOOGA, Tenn. – Chattanooga native and actor Dennis Haskins, best known as Principal Richard Belding on “Saved by the Bell,” has died at age 75, according to his friend and caretaker. An official cause of death has not been confirmed, but Haskins did have Parkinson’s. That’s according to Dimples Karaoke where Haskins was a regular. Before his television career, Haskins was deeply involved at the University of Tennessee at Chattanooga.Peter Byrne, Singer From ’80s Synth-Pop Duo Naked Eyes, Dies at 74September 23, 2026  Peter Byrne, the singer of the 1980s synth-pop duo Naked Eyes, has died at age 74. A press release announcing his death states that Byrne “died peacefully in Los Angeles on Monday, Sept. 14, after a brief illness.” According to Setlist.fm, Naked Eyes last performed on June 6, 2026, as part of the Totally ’80s Pool Party in Las Vegas. Naked Eyes scored their first hit in 1983 with a synth-pop cover of Burt Bacharach and Hal David’s “Always Something There to Remind Me,” which reached No. 8.No cause of death reported.Chuck Varga Dies: Singer With Shock Metal Band GWAR Was 68September 26, 2026  Chuck Varga, a founding member and vocalist of the shock-rock heavy metal band GWAR, has died following a battle with cancer. A resident of Brooklyn, New York, Varga was 68. His death was announced GWAR bass player Casey Orr, who said Varga, who during his time with the band sometimes played the character Sexicutioner, died peacefully with wife Bambi at his side. Varga disclosed his cancer diagnosis last April, with his GWAR bandmates launching a nationwide blood donation campaign in his honor.A Guitar ‘King’ Has Died: Carvin Jones Was 60September 25, 2026  Blues guitarist Carvin Jones, known as “King of Strings,” has passed away. He was 60 years old. Jones’ Instagram announced his passing earlier this week, saying in part, “It is with immeasurable sadness that we share that Corvin Keith Anthony Jones, known to his family and friends around the world as Carvin Jones, the “King of Strings,” passed away in the early morning of September 20, 2026.” Per news shared by azfamily.com, Jones’ untimely death was a result of prostate cancer. He shared his diagnosis publicly in April 2025.Two pro wrestlers “died suddenly”:PAC (Benjamin Satterley) Tragically Dies At 40September 27, 2026  Hoffman Estates, Illinois – AEW star and former champion Benjamin Satterley, known as PAC, has sadly passed away. Just hours after competing against Andrade El Idolo last night for the AEW National Championship in the opening match at All Out, All Elite Wrestling announced PAC’s passing through its social media channels. PAC was just 40 years old and still going strong in his physical prime. PAC signed with WWE in 2012, where he became a top star on WWE NXT. AEW has been rocked by tragedy in 2026 amid the sudden death of former AEW star Andy “The Butcher” Williams and the heartbreaking announcement of Tanea “Rebel” Brooks’ ALS diagnosis.Researcher’s Note – Tony Khan was recently interviewed by PWTorch about the COVID-19 vaccination [sic] status of the AEW roster. The AEW President revealed that the majority of the roster is currently vaccinated [sic], and he noted that international touring will create an issue for those that are not: https://www.wrestlinginc.com/news/2021/11/tony-khan-confirms-he-does-not-require-aew-wrestlers-to-be-vaccinated/No cause of death reported.MCW Wrestler Jose ‘Jacobs’ Trujillo Passes Away at 30September 25, 2026  The wrestling community is mourning the loss of Jose “Jacobs” Trujillo. Maryland Championship Wrestling announced that Trujillo has passed away at just 30 years old. MCW Pro Wrestling shared the news, remembering Trujillo as someone whose time with the promotion may have been brief, but who still became part of its locker room and the larger wrestling community. The promotion did not disclose a cause of death in its announcement.WWE Stars Pay Tribute After Beloved ‘Sign Guy’ Rick Achberger DiesSeptember 27, 2026One of the most recognizable fans in WWE history has died. Rick Achberger [54], better known to generations of wrestling fans as “WWE Sign Guy,” passed away Sunday, Sept. 27. Lance Peterson announced the news on social media, remembering Achberger as a great person who loved talking with fellow fans at wrestling shows. Peterson said Achberger had dealt with health issues for the past couple of years and that his condition had declined rapidly over the past month. A specific cause of death has not been publicly disclosed. Achberger became instantly recognizable during the 2000s for his red hat, blue work shirt and seemingly endless collection of signs. He attended dozens of WWE events each year and eventually became enough of a fixture that seeing him on television felt like part of the show itself.Renowned Official Elliot Schwartz Passes AwaySeptember 25, 2026  Longtime and beloved U.S. Figure Skating official Elliot Schwartz passed away on Thursday, Sept. 24, after complications from a medical procedure. He was 59. “Today, the global skating community is mourning the tragic loss of Elliot,” U.S. Figure Skating President Kevin Rosenstein said. “Elliot was a light in the figure skating world, as a superfan, an official, a dedicated volunteer, our data guru, and as one of the kindest individuals our community has known.” At the Paris Olympics in 2024, he worked with U.S. teams involved in the acrobatic sports, gymnastics, diving and artistic swimming.Researcher’s note – U.S. Figure Skating did not mandate proof of COVID-19 “vaccination” as a condition of participation for participants, athletes, or attendees at its sanctioned events and competitions, instead leaving proof-of-vaccination [sic] requirements up to individual host facilities or local organizing committees: https://members.usfsaonline.org/news/press-release/us-figure-skating-covid-19-policy-updateNo cause of death reported.Don Cooper cause of death: What happened to former White Sox pitching coach? Tributes pour in after death at 70September 24, 2026  Former Chicago White Sox pitching coach Don Cooper has died at age 70. Cooper died on September 22, 2026, at his home in Brentwood, Tennessee, according to his family. His family announced the death on social media the following day, while the White Sox also confirmed his passing. Cooper spent 33 seasons with the White Sox organisation and served as the team’s major-league pitching coach for 18 full seasons. Cooper’s family said he died peacefully at his home, but did not give a cause of death.Rocky Hill mourns town mechanic and Stafford Speedway champion from TollandSeptember 24, 2026  ROCKY HILL, CT – Emergency response departments in Rocky Hill said they are mourning the sudden death of a colleague and town employee. Rich Hammann, 60, of Tolland [CT], died on Sept. 18, according to his obituary. He died of natural causes, the Office of the Chief Medical Examiner said. “He was not only a Stafford Speedway champion, but also an important part of our racing community for nearly 30 years,” the racetrack wrote in a Facebook post. He served in the United States Army, had his own auto repair shop, and eventually ended up as head mechanic of the highway department for the Town of Rocky Hill.Researcher’s note – While the track did not implement an employee “vaccination” mandate, the organization heavily focused on public and fan “vaccination” initiatives. Stafford Motor Speedway repeatedly partnered with the Connecticut Department of Public Health and Griffin Health to host free, on-site mobile “vaccination” clinics in its parking lot during race days throughout the 2021 season: LinkNo cause of death reported.Venice Loses One of Its Own as Benjamin “Barefoot Ben” Johnson Has Passed AwaySeptember 24, 2026  Benjamin “Barefoot Ben” Johnson has passed away, with all the good homies remembering the Venice [CA] local through the memories they shared with him. River Perez shared the news with a personal tribute, calling Ben the “radest skater” he knew. Perez recalled meeting him after moving to Venice and becoming friends. The two would often walk around barefoot together. Perez also encouraged people to check on their friends before remembering the camping trips they shared at Lake Elsinore. Diggity Dog also paid tribute, writing: “Gone too soon. Rest in Peace Ben.”No age or cause of death reported.BET host Angela Stribling dies after brain cancer battleSeptember 27, 2026  Angela Stribling [58], a former host of BET shows and radio personality, has died. Stribling’s husband, Ken Washington, shared the news in an Instagram post shared on her account and in a statement to her longtime Washington, D.C., radio station, WHUR 96.3 FM, on Sept. 27. “It is with a broken heart that I share that my beloved wife, Angela Marie Stribling, passed away peacefully at home on Saturday, September 26, after a courageous two-yea |
…
DR PAUL ALEXANDER
RABOBANK/MICHAEL EVERY/OR OR PICTON/GIFFIN OR RABOBANK EXECUTIVE/COMMENTARY ON WORLDLY AFFAIRS
7. OIL AND NATURAL GAS/ENERGY COMMENTARIES
Texas Governor Declares Disaster Over Soaring Diesel Prices
Tuesday, Sep 29, 2026 – 05:00 PM
Texas ranchers and truckers could start seeing some relief at the fuel pump starting this week after Gov. Greg Abbott proclaimed a statewide disaster on Sept. 28 to ease diesel shortages.
“Texas agriculture and freight run on diesel,” Abbott said in a statement.
“Record prices put both industries at risk and raise costs for every Texas family.“
Record-high diesel prices in the Lone Star State have increased in the past few weeks, hovering at an average of $5.90 per gallon on Sept. 28, about 10 cents less than a week ago on average, but $2.70 more than a year ago, according to the American Automobile Association (AAA).
The national average reached $6.44 per gallon on Sept. 28, about 2 cents less than the day before but $2.77 more than last year, AAA reported.
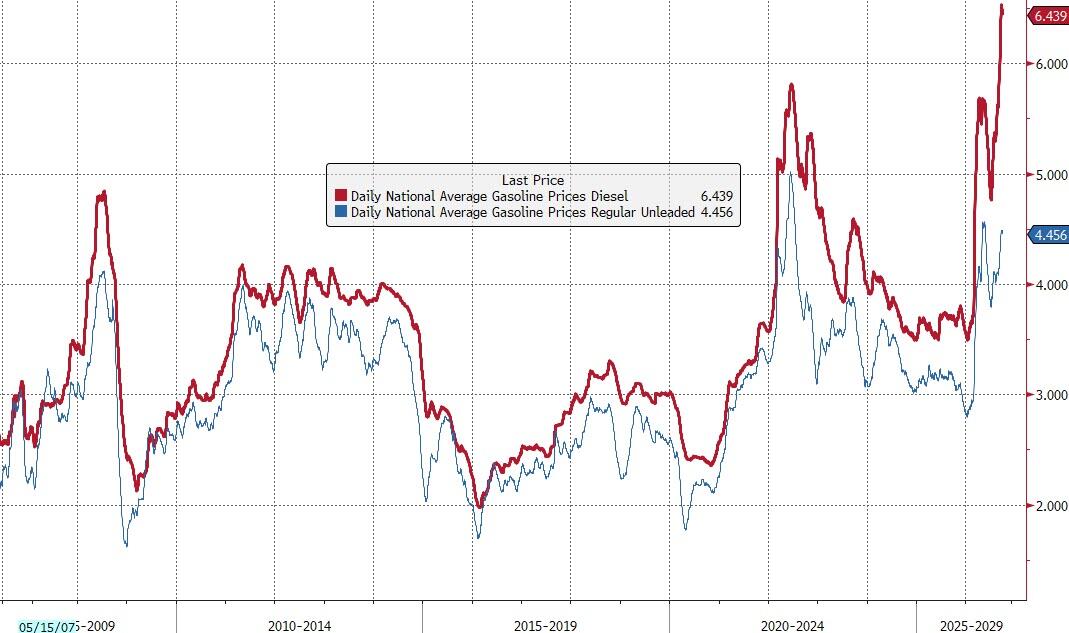
As Jill McLaughlin further report for The Epoch Times, Abbott’s declaration allows for the expanded use of dyed diesel on Texas roads and raises the allowable weight for fuel, agricultural, and timber loads.
The proclamation also suspends the state’s low emission diesel rules to a level authorized by federal environmental standards. This is expected to increase diesel supplies and ease the record-high fuel prices.
Abbott also asked the U.S. Environmental Protection Agency to waive federal ultra-low sulfur diesel requirements.
Dyed diesel is off-road fuel marked with solvent red 164 dye and is typically only used in agricultural operations. The fuel is sold without a motor fuel tax, which is why the state usually prohibits its use on public roadways.
Using red-dyed diesel doesn’t compromise fuel quality or engine performance, but it can stain tanks, hoses, and skin, according to Senergy Petroleum.
“From a performance standpoint, clear diesel and dyed diesel are virtually identical,” the company stated.
The Texas governor sent a letter to Environmental Protection Agency Administrator Lee Zelden on Sept. 28, asking for a temporary Clean Air Act waiver of federal ultra-low sulfur diesel rules and the Texas low emission diesel rules that apply in 110 counties.
The rules limit which diesel can be sold, and a waiver would let the state allow more fuel to reach Texas pumps, Abbott said.
The Texas Forestry Association applauded Abbott’s diesel declaration.
“A BIG WIN FOR LOGGING & TEXAS FORESTRY!” the association posted on X.
“Gov. Abbott’s new disaster proclamation expands dyed-diesel use on Texas roads and allows fuel, agricultural, and timber loads up to 95,000 pounds.”
Oil prices surged on Sept. 28 after President Donald Trump turned down Iran’s conditional seven-day proposal to reopen the Strait of Hormuz. He told reporters over the weekend that he had rejected it and declined to rule out restarting strikes on Iran ahead of the midterms.
The rejection dashed hopes of diplomacy seen last week at the U.N. General Assembly, said oil expert Patrick De Haan in a social media post. Early trading sent oil prices slightly higher for domestic and international crude.
Prices for diesel fuel nationwide have rocketed to record levels this month after a combination of events reduced supplies and caused uncertainties in the global oil market.
Conflicts in the Middle East and between Russia and Ukraine have slowed delivery of supplies reaching the United States.
Diesel supplies are expected to remain tight and below average through much of next year, according to an analysis by the U.S. Energy Information Administration (EIA), the federal statistical and analytical agency for energy data.
“We assume global production of distillate fuel will remain below last year’s levels in the coming months, contributing to low U.S. diesel inventories and high diesel prices,” the EIA reported on Sept. 9.
However, oil prices are expected to start falling at the start of next year, as production in the Middle East rises in the coming months with more traffic coming through the Strait of Hormuz and alternative routes out of the region, the EIA reported.
U.S. natural gas inventories are on track to be above the five-year average at the start of winter, due to rising production in the U.S. Permian Basin and Haynesville Shale regions, according to the EIA.
END
8. EMERGING MARKETS//AUSTRALIA NEW ZEALAND ISSUES
U.S./GOLD AND SILVER PRICING/ASIAN CLOSING MARKETS AND EUROPEAN BOURSE OPENING AND CLOSING/ INTEREST RATE SETTINGS WEDNESDAY MORNING 6;30AM//OPENING AND CLOSING\
OPENING LEVELS OF CURRENCIES// AND CLOSING ASIAN STOCK MARKET AND OPENING EUROPEAN STOCKS:6 AM EST
EURO VS USA DOLLAR: 1.1358 UP 0.0018
USA/ YEN 157.13 DOWN 0.398 NOW TARGETS INTEREST RATE AT 1.75% AS IT WILL BUY UNLIMITED BONDS TO GETS TO THAT LEVEL…//YEN STILL FALLS//END OF YEN CARRY TRADE BEGINS AGAIN DEC 2024/Bank of Japan raises rates by .25% TO 1.75 ..TAKAICHI NEW PM AS YIELDS RISE//JAPAN DEEPLY IN TROUBLE WITH RISING RATES AND A FALLING YEN!! BANK OF JAPAN WILL NO LONGER DO QE. URGES PENSION AND INSUANCE FUNDS TO BUY JAPANESE BONDS//
YEN CARRY TRADERS MURDERED
GBP/USA1.3279 UP 0.0054 OR 54 BASIS PTS
USA/CAN DOLLAR: 1.4182 DOWN 0.0009 //CDN DOLLAR UP 9 BASIS PTS//
Last night Shanghai COMPOSITE CLOSED UP 11.74 OR 0.31%
Hang Seng CLOSED UP 89.70 PTS OR 0.37%
AUSTRALIA CLOSED UP 0.60%
// EUROPEAN BOURSE: ALL MIXED
Trading from Europe and ASIA
I) EUROPEAN BOURSES: ALL MIXED
2/ CHINESE BOURSES / :Hang SENG CLOSED UP 89.70 PTS OR 0.37%
/SHANGHAI CLOSED UP 11.74 PTS OR 0.31%
AUSTRALIA BOURSE CLOSED UP 0.60%
(Nikkei (Japan) CLOSED UP 1414.78 PTS OR 2.16%
INDIA’S SENSEX IN THE RED
Gold very early morning trading: $4187.20
silver:$60.81
USA DOLLAR VS TRY (TURKISH LIRA): 49.02 UP 2 BASIS PTS AND NOW WE SEE THEIR STUPIDITY OF SELLING SOME OF THEIR GOLD AND ALL OF THEIR USA DOLLAR RESERVES. THE COUNTRY IS IN BIG FINANCIAL TROUBLE
USA DOLLAR VS RUSSIAN ROUBLE: 83.94 ROUBLE// UP 0 ROUBLE AND 6 BASIS PTS.
UK 10 YR BOND YIELD: 5.3738 DOWN 4 BASIS PTS
UK 30 YR BOND YIELD: 5.903 DOWN 2 BASIS PTS
CDN 10 YR BOND YIELD: 3.999 UP 3 BASIS PTS
CDN 5 YR BOND YIELD; 3.703 UP 2 BASIS PTS
USA dollar index early WEDNESDAY MORNING: 100.94 DOWN 18 BASIS POINTS FROM TUESDAY’s CLOSE
WEDNESDAY MORNING NUMBERS ENDS
And now your closing WEDNESDAY NUMBERS 10.00 AM
Portuguese 10 year bond yield: 3.9728% DOWN 8 in basis point(s) yield
JAPANESE BOND 10 yr YIELD: +3.059% DOWN 4 FULL POINTS BASIS POINTS /JAPAN losing control of its yield curve/
JAPAN 30 YR: 4.134 DOWN 4 BASIS PTS//
SPANISH 10 YR BOND YIELD: 4.1090 DOWN 5 in basis points yield
ITALY 10 YR BOND: 4.590 DOWN 1 points in basis points yield ./
GERMAN 10 YR BOND YIELD: 3.5928 DOWN 0 BASIS PTS
IMPORTANT CURRENCY CLOSES : MID DAY WEDNESDAY
Closing currency crosses for day /USA DOLLAR INDEX/USA 10 YR BOND YIELD/10:00 AM
Euro/USA 1.1363 UP 0.0022 OR 22 basis points
USA/Japan: 156.78 DOWN 0.642 OR YEN IS UP 64 BASIS PTS// HIGHLY INFLATIONARY TO JAPAN
Great Britain 10 YR RATE 5.4044 UP 1 BASIS POINTS //
GREAT BRITAIN 30 YR BOND; 5.9310 UP 2 BASIS POINTS.
CANADIAN DOLLAR UP 20 BASIS PTS TO 1.4172
xxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxx
The USA/Yuan CNY 6.7046 ON SHORE ..DOWN
THE USA/YUAN OFFSHORE// CNH DOWN TO 6.7061
TURKISH LIRA: 49.02 UP 2 EXTREMELY DANGEROUS LEVEL/DEATH WATCH/HYPERINFLATION TO BEGIN.//
Your closing 10 yr US bond yield DOWN 2 in basis points from TUESDAY at 5.234% //trading well ABOVE the resistance level of 2.27-2.32%)
USA 30 yr bond yield 5.581 DOWN 1 basis points /10:00 AM
USA 2 YR BOND YIELD: 4.831 DOWN 7 BASIS PTS.
GOLD AT 10;00 AM $4202.00
SILVER AT 10;00: $60.95
Your 11:00 AM bourses for Europe and the Dow along with the USA dollar index closing and interest ratesTUESDAY
DAY CLOSING TIME/ 12:00 AM///
London: CLOSED DOWN 30.71 PTS OR 0.29%
GERMAN DAX: CLOSED DOWN 200.02 PTS OR 0.79%
FRANCE: DOWN 71.36 OR 0.89 PTS
Spain IBEX CLOSED DOWN 91.30 PTS OR 0.47%
Italian MIB: CLOSED DOWN 432.96 PTS OR 0.84%
WTI Oil price 90.24 10.00 EST/
Brent Oil: 98.14 10:00 EST
USA /RUSSIAN ROUBLE: 83.11/// ROUBLE UP 0 AND 91/ 100
CDN 10 YEAR RATE: 3.999 UP 3 BASIS PTS.
CDN 5 YEAR RATE: 3.703 UP 2 BASIS PTS
CLOSING NUMBERS: 4 PM//
Euro vs USA 1.1331 DOWN 0.0009 OR 9 BASIS POINTS//
British Pound: 1.3264 UP 0.0034 OR 34 basis pts/
BRITISH 10 YR GILT BOND YIELD: 5.4358 UP 2 FULL BASIS PTS//
BRITISH 30 YR BOND YIELD: 5.958 UP 5 IN BASIS PTS.
JAPAN 10 YR YIELD: 3.051 DOWN 3 FULL BASIS PTS (DANGEROUS TO THEIR ECONOMY
JAPANESE 30 YR BOND: 4.121 DOWN 5 PTS AND STILL VERY DANGEROUS TO THEIR ECONOMY
USA dollar vs Japanese Yen: 157.36 DOWN 0.070 OR YEN UP 7 BASIS PTS//GETTING FURTHER AWAY FROM 160.00/ EXTREMELY DANGEROUS
USA dollar vs Canadian dollar: 1.4237 UP 0.0041 PTS// CDN DOLLAR DOWN 41 BASIS PTS
West Texas intermediate oil: 90.53
Brent OIL: 98.16
USA 10 yr bond yield UP 2 BASIS pts to 5.288
USA 30 yr bond yield: UP 5 PTS to 5.639%
USA 2 YR BOND 4.887 DOWN 1 PTS
CDN 10 YR RATE 3.993 UP 0 BASIS PTS
CDN 5 YEAR RATE: 3.703 UP 0 BASIS PTS
USA dollar index: 101.20 UP 2 BASIS POINTS
USA DOLLAR VS TURKISH LIRA: 49.02 UP 2 BASIS PTS GETTING QUITE CLOSE TO BLOWING UP/IDIOTS SOLD GOLD
USA DOLLAR VS RUSSIA//// ROUBLE: 83.37 UP 0 AND 63 /100 roubles //
GOLD $4,153.50 3:30 PM)
SILVER: 60.32 3;30 PM)
DOW JONES INDUSTRIAL AVERAGE: DOWN 402.60 POINTS OR 0.78%
NASDAQ 100 UP 69.17 PTS OR 0.23%
VOLATILITY INDEX 16.19 UP 0.15 PTS OR 0.94%
GLD: $ 380.84 DOWN 2.05 PTS OR 0.54%
SLV/ 54.51 PTS DOWN 0.97 OR .175%
TORONTO STOCK INDEX// TSX INDEX: CLOSED DOWN 121.98 PTS OR 0.34%
end
TRADING today ZEROHEDGE 4 PM: HEADLINE NEWS/TRADING
‘
Third Quarter Ends With Surging Yields Closing At 24 Year High… As Stocks Yawn
WRAP UP
Stocks mixed and yields rise despite soft PCE – Newsquawk US Market Wrap
Wednesday, Sep 30, 2026 – 04:13 PM
- SNAPSHOT: Equities mixed, Treasuries down, Crude up, Dollar up, Gold down.
- REAR VIEW: Softer-than-expected US PCE; US GDP revised higher; US Goods Trade Balance deficit widens; US ADP beats; Yemeni armed forces reportedly attacked Abqaiq oil city in eastern Saudi Arabia; Senior source said mediators conveyed Washington’s response to the Iranian Foreign Minister; EIA crude stocks show bigger-than-expected build; Softer-than-expected Aussie CPI.
- COMING UP: Data: Japanese Tankan Survey (Q3), Australian Trade Balance (Aug), Swiss CPI (Sep), US Challenger Job Cuts (Sep), Jobless Claims (Sep/26), ISM Manufacturing PMI (Sep), Atlanta Fed GDP (Q3)
Events: BoJ SOO (Sep). Speakers: BoE’s Bailey, Mann, Pill; ECB’s Cipollone, Lagarde, Schnabel; Fed’s Barkin, Collins, Schmid, Waller, Jefferson, Bowman, Cook, Williams, Logan; BoC’s Rogers. Supply: Spain, France. Earnings: Accenture, McCormick, Nike
More Newsquawk in 2 steps:
- 1. Subscribe to the free premarket movers reports
- 2. Trial Newsquawk’s premium real-time audio news squawk box for 7 days
MARKET WRAP
Stocks were mixed on Wednesday, with notable Nasdaq outperformance, while the SPX saw mild gains, RUT was flat and DJI lower, with the equal-weight S&P also declining. The majority of sectors were lower, led by Consumer Staples, Health Care and Real Estate. Meanwhile, Technology and Communication Services rallied, supporting the broader indices given their weightings, largely led by gains in Apple (AAPL) and Alphabet (GOOGL). Attention turns to Micron (MU) earnings after-hours, with some choppy trade seen in late trade on account of month and quarter end.
The macro highlight was US PCE, which was broadly softer than expected, although somewhat clouded by BEA methodology changes, with many expecting a downside surprise. The initial reaction was dovish but ultimately faded. Q2 GDP was also stronger than expected, while the Goods Trade Balance deficit widened in August, led by further capital goods imports amid strong AI-related demand. ADP private payrolls also topped expectations.
The yield curve bear steepened, with front-end yields relatively anchored while the long end rose. Yields initially fell following the soft PCE report but swiftly pared the move. Money markets continued to pare Fed hike bets, with the probability of an October hike falling back to around 40% following Williams’ commentary on Tuesday and Wednesday’s PCE report. Goldman Sachs pushed back its next Fed hike call to December from October following the data.
In FX, the Dollar was ultimately little changed, while the Aussie lagged following softer-than-expected inflation data.
Oil prices settled higher amid little progress in US-Iran diplomacy, while the Yemeni Houthis reportedly struck the Saudi Abqaiq oil facility, with any impact on production still unclear. Gold initially rallied following the PCE data but tumbled into settlement as the initial dovish reaction faded and long-end US yields rose.
Attention on Thursday turns largely to the ISM Manufacturing PMI following the strong preliminary S&P Global PMI earlier in the month, before all eyes turn to Friday’s NFP report.
US
PCE: The August PCE report was soft with downward revisions, although largely due to methodology changes. Core PCE rose 0.2% M/M, cooling from 0.4% and below the 0.3% consensus, while the Y/Y rate was unchanged at 3.0%, below the 3.3% forecast, with the prior revised down from 3.3%. Headline PCE rose 0.3% M/M, accelerating from 0.1% but below the 0.4% forecast, while the Y/Y rate was unchanged at 3.4%, below the 3.7% forecast, with the prior revised down from 3.7%. Within the report, PCE services prices ex-energy and housing accelerated to 0.4% from 0.1%, while goods prices rose just 0.03%. The softer headline figures are welcome for the Fed, although Oxford Economics highlights that the annual NIPA update revealed a larger-than-expected downward revision to core PCE inflation due to methodological changes affecting software and accessories, portfolio management, and legal services. The consultancy notes that while the revisions ease core PCE inflation at the margin, they do not erase Fed concerns around a broadening of inflation pressures from supply shocks, including the Middle East, the AI investment boom and tariffs. The downward revision was concentrated in portfolio management and investment advice fees, which OxEco suggests should not be given too much weight from the Fed’s perspective. Indeed, the Fed tends to look through inflation tied to financial services and instead places greater emphasis on market-based PCE, which accelerated to 0.4% M/M from 0.1%, while the core market-based measure rose 0.3% from 0.1%. Elsewhere, Personal Income rose just 0.2%, below the 0.5% forecast and prior 0.3%, while consumption accelerated to 0.6% from 0.1%. Nonetheless, the report saw markets further pare hawkish Fed bets following Williams’ remarks on Tuesday.
ADP: The US ADP private payroll report was strong in September, rising 90k from 38k and above the 70k forecast, pointing to solid private-sector hiring. The report noted that hiring accelerated for the first time since May, with gains led by Education & Health Care and Leisure & Hospitality, while Financial Activities and Professional & Business Services showed weakness. The Pay Insights data showed gross pay growth was little changed. Median Y/Y pay growth for all workers was 4.7%, matching the prior month’s pace, while pay growth for job stayers was unchanged at 4.4% and slowed marginally for job changers to 7.3% from 7.4%. Despite the strong report, Pantheon Macroeconomics said it “provides little reason to alter expectations for Friday’s official payrolls report”, noting that the relationship between ADP employment and the BLS NFP report is unreliable.
ADVANCED GOODS TRADE BALANCE: US advanced goods trade balance rose 11.5% in August to a deficit of USD 132.6bln from USD 118.9bln, and deeper than the expected deficit of USD 115bln. Exports of goods were USD 203.4bln, +USD 3.7bln M/M, while imports of goods jumped USD 17.4bln M/M to USD 336.1bln. The net deficit widened to its largest level since Q1 2025. For imports, Capital Goods was the largest category and printed USD 145.84bln (vs. USD 140.26bln in July) amid ongoing strong demand for AI, while industrial supplies imports, a category that includes oil and petroleum products, surged by 16% last month; Oxford Economics writes that the possibility of a diesel export ban remains a risk for further widening of the trade deficit in the near term. Overall, Oxford thinks the August advanced goods data points to a 3ppt drag from net trade on Q3 GDP.
FIXED INCOME
T-NOTE FUTURES (Z6) SETTLED 7 TICKS LOWER AT 104-06+
Yield curve bear steepens despite soft PCE data. At settlement, 2-year +1.0bps at 4.889%, 3-year +2.6bps at 4.998%, 5-year +4.5bps at 5.093%, 7-year +5.7bps at 5.198%, 10-year +6.1bps at 5.295%, 20-year +7.2bps at 5.691%, 30-year +7.5bps at 5.641%.
THE DAY: Treasury yields rose across the curve on Wednesday, with the long end leading the move to see the curve bear steepen. There was plenty of data to digest, with yields initially rising after ADP private payrolls increased 90k in September, above the prior 38k and 70k forecast, pointing to solid private-sector hiring. The move swiftly pared, however, with participants cognisant of the historically weak relationship between ADP and Friday’s official NFP report.
Shortly after, August PCE and final Q2 GDP data were released. PCE was soft, with prior figures revised lower, although much of the softness reflected well-documented BEA methodology changes affecting software and accessories, portfolio management, and legal services. Yields initially fell across the curve before swiftly paring the move. Oxford Economics noted the report is unlikely to prevent the Fed from hiking again, highlighting that the Fed tends to look through inflation tied to financial services and instead places greater emphasis on market-based PCE, which accelerated to 0.4% M/M from 0.1%, while the core market-based measure rose 0.3% from 0.1%.
Final Q2 GDP growth was revised higher to 2.2% from 2.1%, despite expectations for a revision down to 1.5%, while consumer spending accelerated to 3.8% from 0.5%, above the 3.4% forecast, pointing to a robust consumer. Many Fed speakers were scheduled but little new was said, while following the data Goldman Sachs pushed back its next Fed hike forecast to December from October.
On geopolitics, oil prices climbed throughout the session amid supply concerns after the Houthis reportedly hit the Saudi Abqaiq oil city, although front-end yields remained relatively anchored despite the rise in energy prices. Money markets pared hawkish Fed bets further, with October pricing falling to 9.8bps from 12.9bps and December to 30.6bps from 33.6bps.
Supply
Bills
STIRS / OPERATIONS
- Fed Hike Pricing via CME FedWatch: Oct 9.8bps (prev. 12.9bps), Dec 30.6bps (prev. 33.6bps)
- EFFR at 3.88% (prev. 3.88%), volumes at USD 111bln (prev. USD 110bln) on September 29th
- SOFR at 3.88% (prev. 3.90%), volumes at USD 2.967tln (prev. USD 2.964tln) on September 29th
- NY Fed RRP op demand at 11.54bln (prev. 11.45bln) across 18 counterparties (prev. 10) on September 30th
- US Treasury announced it will buyback USD 6bln of 10-20year bonds on Thursday, matching the prior size.
CRUDE
WTI (X6) SETTLED USD 1.04 HIGHER AT 90.42/BBL; BRENT (Z6) SETTLED USD 1.87 HIGHER AT 98.03/BBL
The crude complex saw gains, recovering earlier losses, amid seemingly little progress on US-Iran talks while the Abqaiq oil city in Saudi Arabia was attacked by the Houthis. WTI and Brent hit lows of USD 88.58/bbl and USD 95.12/bbl, respectively, in the European morning as they initially extended Tuesday’s losses. However, benchmarks soon reversed, with some citing the FlyDubai incident as the initial catalyst, although it was later reported to involve a rogue pilot who was tackled by other pilots and passengers. There was otherwise little headline-specific news at the time to explain the recovery despite plenty of geopolitical newsflow, although it was later reported that the Houthis attacked the Abqaiq oil city in eastern Saudi Arabia during the afternoon. Trump reiterated that developments regarding Iran will be seen very soon and said there have been historic flows of oil out of Hormuz over the past three days.
On the supply front, sources suggested OPEC+ producers are set to keep output targets unchanged at Sunday’s meeting. Meanwhile, in the weekly EIA data, crude stocks saw a slightly larger build than expected, while both distillates and gasoline posted larger-than-expected draws. Overall, weekly crude production rose 16k BPD W/W to 13.955mln BPD.
Meanwhile, many were reporting the Kpler data that showed crude oil exports from the Strait of Hormuz has basically returned to levels seen before the Iran war, thanks to US military escorts boosting shipments and pipelines redirecting flows. Kpler noted that crude transiting the Straight reached a seven-day average of 13.5mln BPD as of Monday. Regarding the Middle East as a whole, including the Red Sea and Persian Gulf, Kper data found shipments are sometimes higher than pre war levels – reaching a seven-day average of 19.5mln BPD, above the pre-war baseline of 17mln BPD. However, JPMorgan emphasised although crude shipments have normalised, refined product supplies remain constrained.
EQUITIES
CLOSES: SPX -0.20% at 7,656, NDX +0.23% at 30,409, DJI -0.86% at 50,909, RUT -0.38% at 2,797.
SECTORS: Technology +0.66%, Consumer Discretionary +0.15%, Energy +0.09%, Communication Services +0.02%, Utilities -0.69%, Materials -0.79%, Financials -1.13%, Industrials -1.25%, Health -1.26%, Real Estate -1.26%, Consumer Staples -1.63%.
EUROPEAN CLOSES: Euro Stoxx 50 -0.83% at 6,268, Dax 40 -0.74% at 25,211, FTSE 100 -0.29% at 10,606, CAC 40 -0.89% at 7,965, FTSE MIB -0.84% at 51,372, IBEX 35 -0.45% at 19,431, PSI +0.01% at 9,667, SMI -0.66% at 13,820, AEX -0.47% at 1,115
STOCK SPECIFICS:
- Concentrix (CNXC) revenue missed with next quarter guidance light as was FY revenue view
- Hewlett Packard Enterprise (HPE) secures first AMD Helios order in $1.2bln deal w/ Vultr.
- FactSet (FDS) FY profit view underwhelmed
- Jacobs (J) to deploy data center digital twin for Nvidia’s R&D facility in the US.
- Target (TGT) was upgraded at HSBC
- Moderna (MRNA) was downgraded at Citi
- Boeing (BA) won a USD 20bln+ F/A-XX contract
- Cal-Maine Foods (CALM) deeper loss per shr. than exp. & rev. missed.
- Eli Lilly’s (LLY) EloraTZP delivered greater weight loss and A1C reduction vs. tirzepatide 15 mg in adults with obesity and type 2 diabetes
FX
The Dollar Index was more-or-less unchanged on Wednesday, despite seeing a bout of pressure following the cooler-than-expected US PCE report, although the signal was somewhat clouded by the BEA methodology changes. Following the dovish remarks from Fed’s Williams on Tuesday and the soft PCE report, money markets now see around a 40% chance of a 25bps hike in October, versus roughly 70% prior to his remarks. Elsewhere, ADP private payrolls rose above expectations, while the advanced goods trade deficit was wider than expected and deteriorated M/M. There was little Fed speak of note.
G10 FX was largely in the red against the Dollar, although the Pound was the clear outperformer and eked out gains, while the Aussie lagged. AUD was pressured by cooler-than-expected Australian CPI. Sterling saw modest strength following an upward revision to Q2 GDP, although the details were somewhat more mixed than the headline suggested, with output and services revised higher but production revised lower.
JPY, EUR, NZD, CHF and CAD all saw losses to varying degrees, albeit with little currency-specific newsflow. The Euro had seen marginal strength during the European morning as it digested inflation metrics from across the bloc, before ultimately fading.
USA DATA RELEASES
Core PCE Prints Cooler Than Expected Due To Change In Methodology, As Savings Rate Plunges To 3 Year Low
Wednesday, Sep 30, 2026 – 09:12 AM
Ahead of today’s closely watched core PCE report – the Fed’s (reportedly) favorite inflation indicator (although that will probably shift to Truflation after Kevin Warsh’s task force is done with analyzing the data), which was seen by many as deciding whether the Fed will hike in October and December, or just December as NY Fed president John Williams strongly hinted yesterday, we warned readers that PCE may surprise to the downside: “the Bureau of Economic Analysis updated methodology for calculating inflation in three components is expected to trim August year-on-year change by a few tenths of a percentage point.”
And surprise it did, because despite rampant energy inflation and record diesel prices, headline PCE came in line sequentially, printing up 0.3%, in line with expectations but coming in far cooler than expected on an annual basis, rising just 3.4%, vs expectations of a 3.7% print.
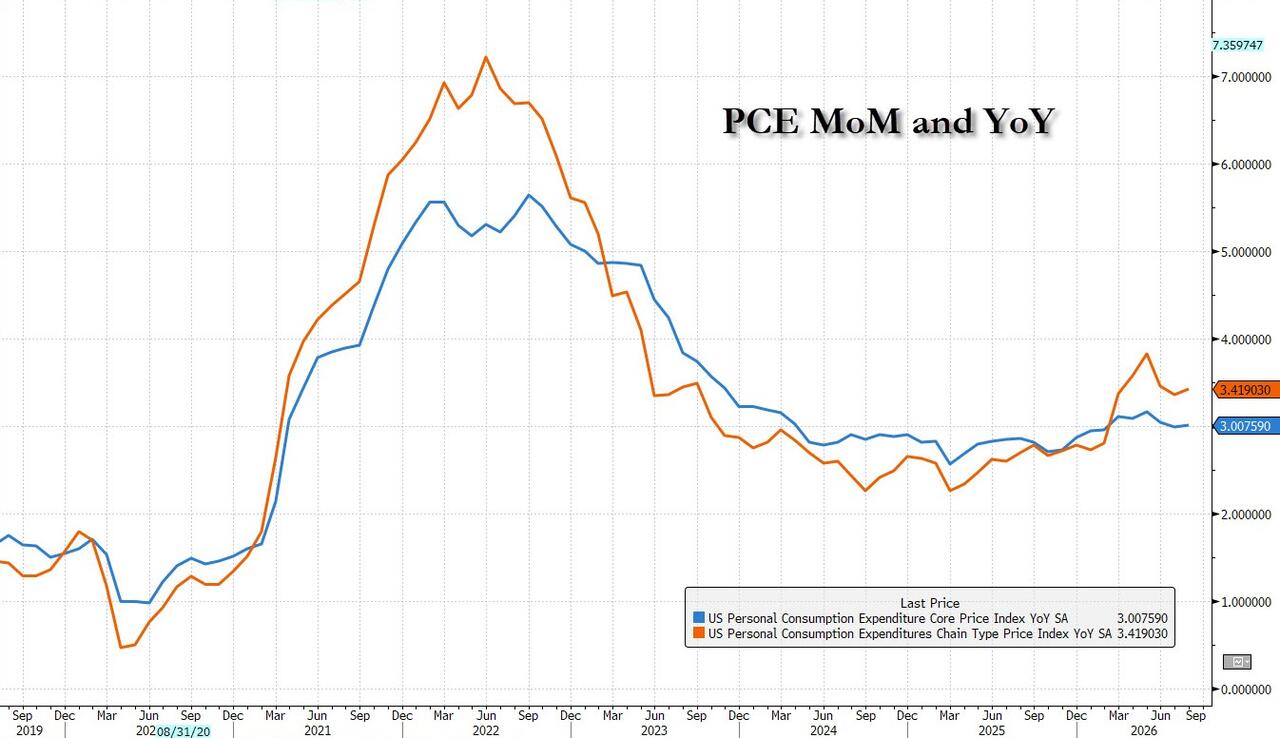
The MoM jump in headline PCE was driven by services, a reversal from last month’s drop, largely due to the spike in communication and education services.
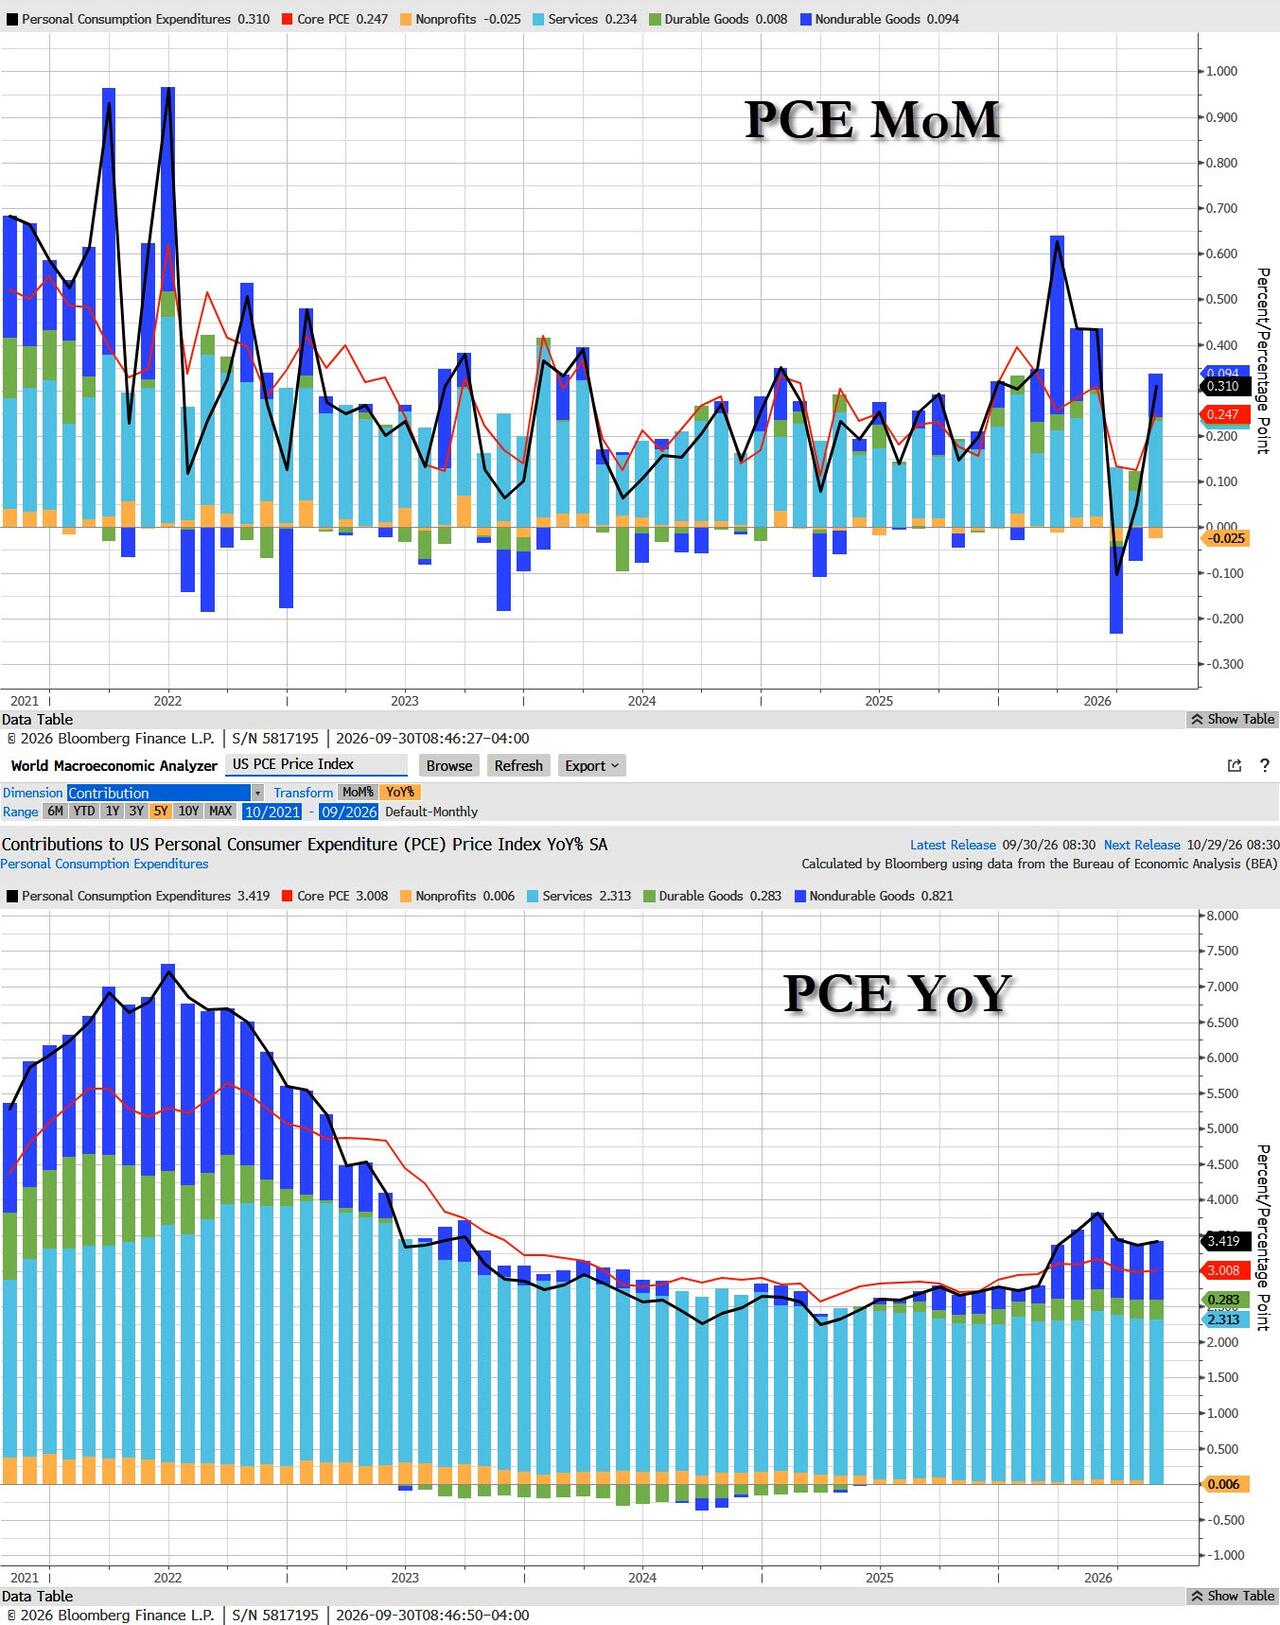
But it was the far more important core PCE, which strips out volatile energy and food prices, that rose 0.2% MoM (technically 0.247%, below the +0.3% MoM expected) with a notable miss in the YoY print, which dropped to +3.0% from the unrevised 3.3% (now revised to 3.0%), missing estimates of a 3.3% print.
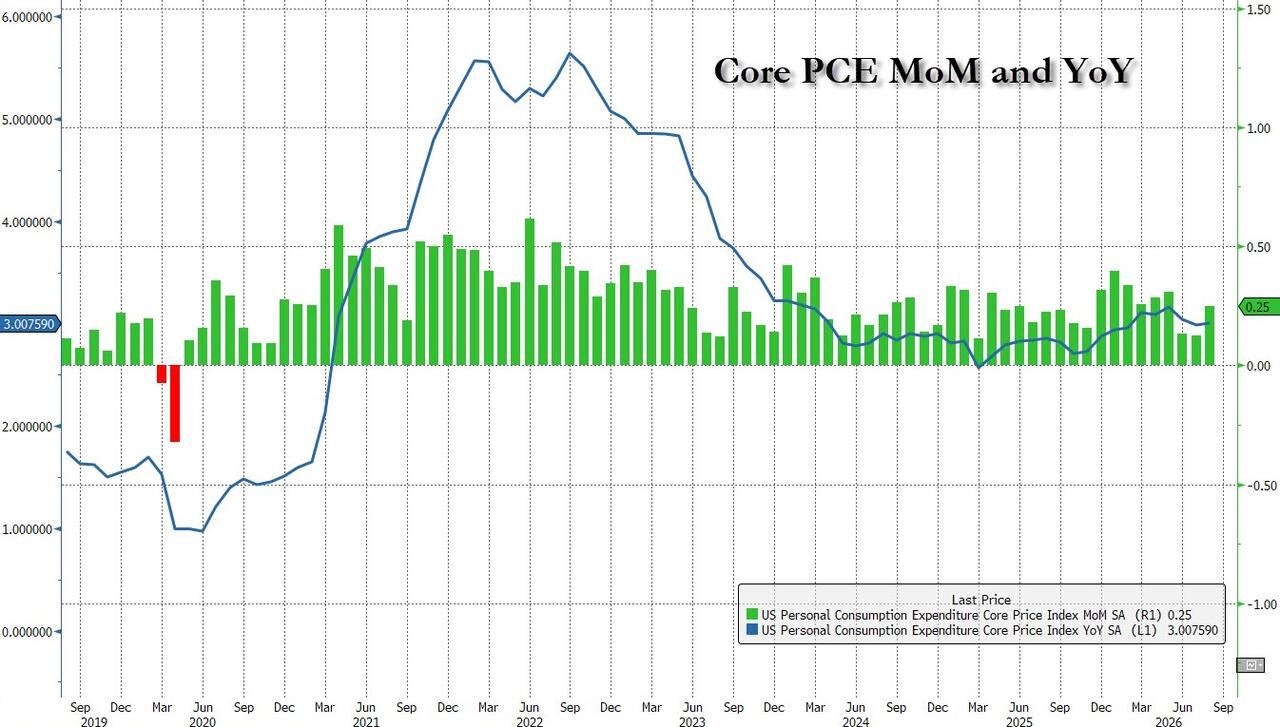
Within core, the biggest jump was again communications and education services.
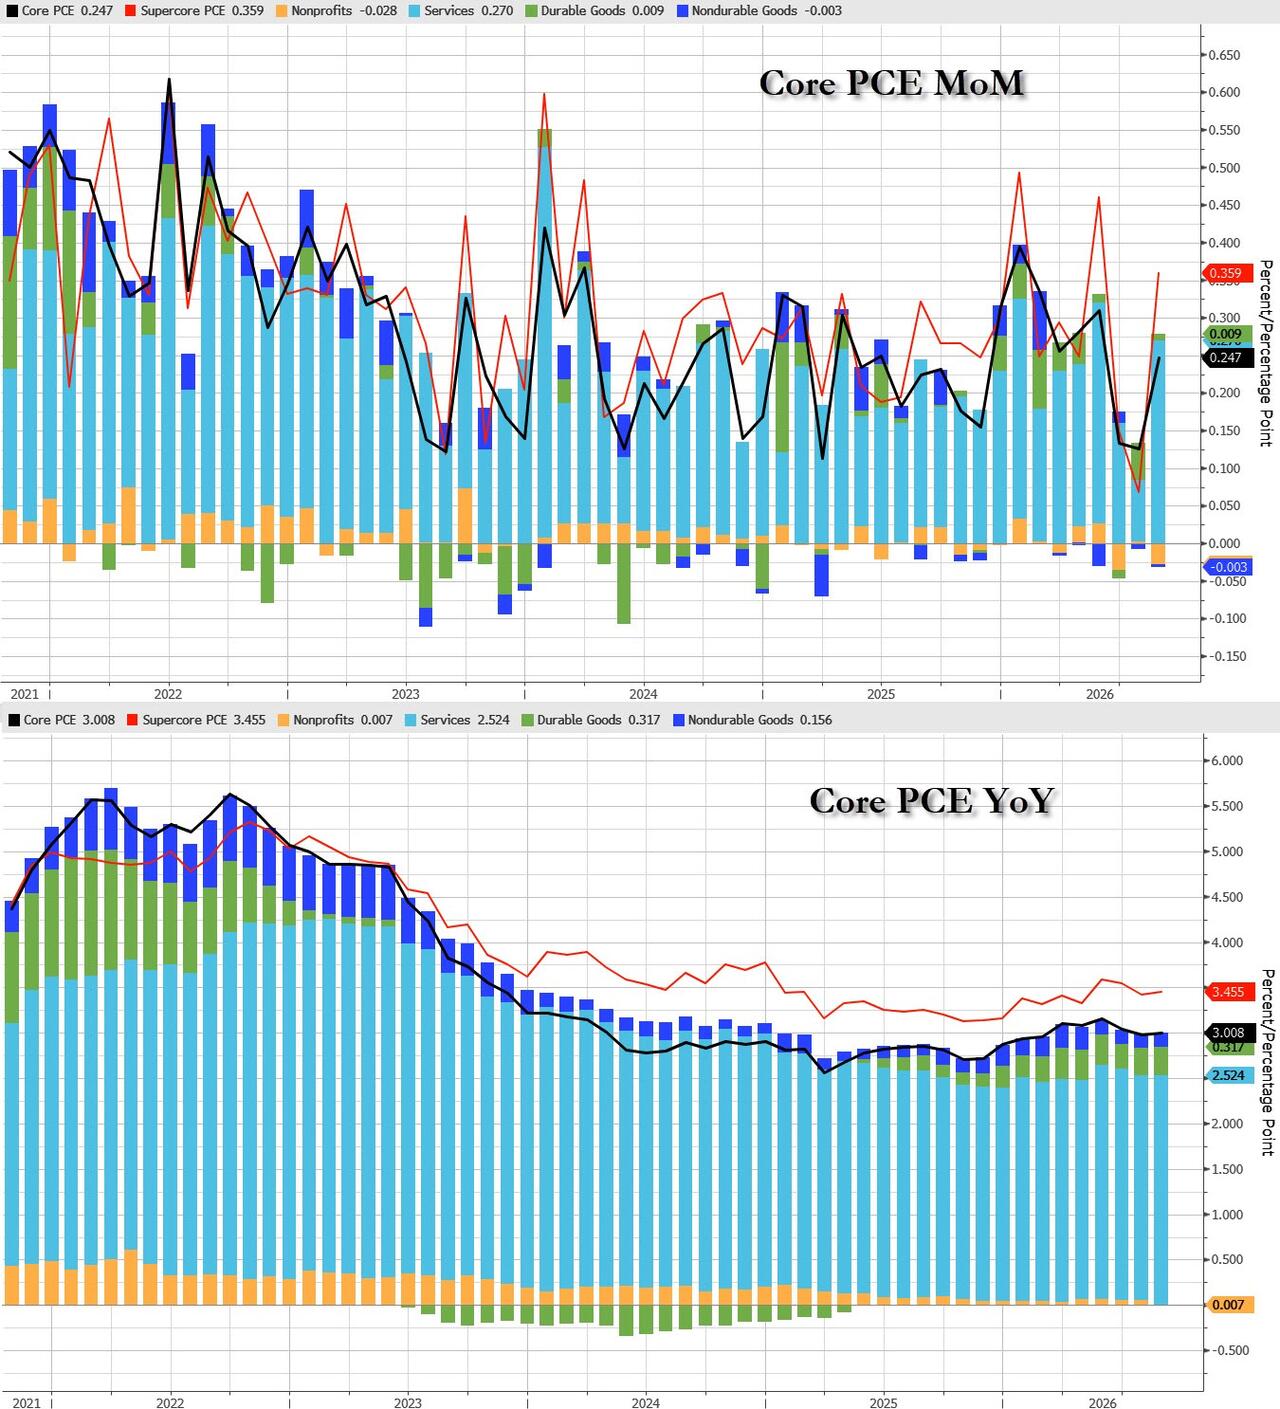
Ominously, the much-watched SuperCore PCE (Services ex-shelter) saw price inflation reverse the recent drop on a YoY basis, while surging on a MoM basis.
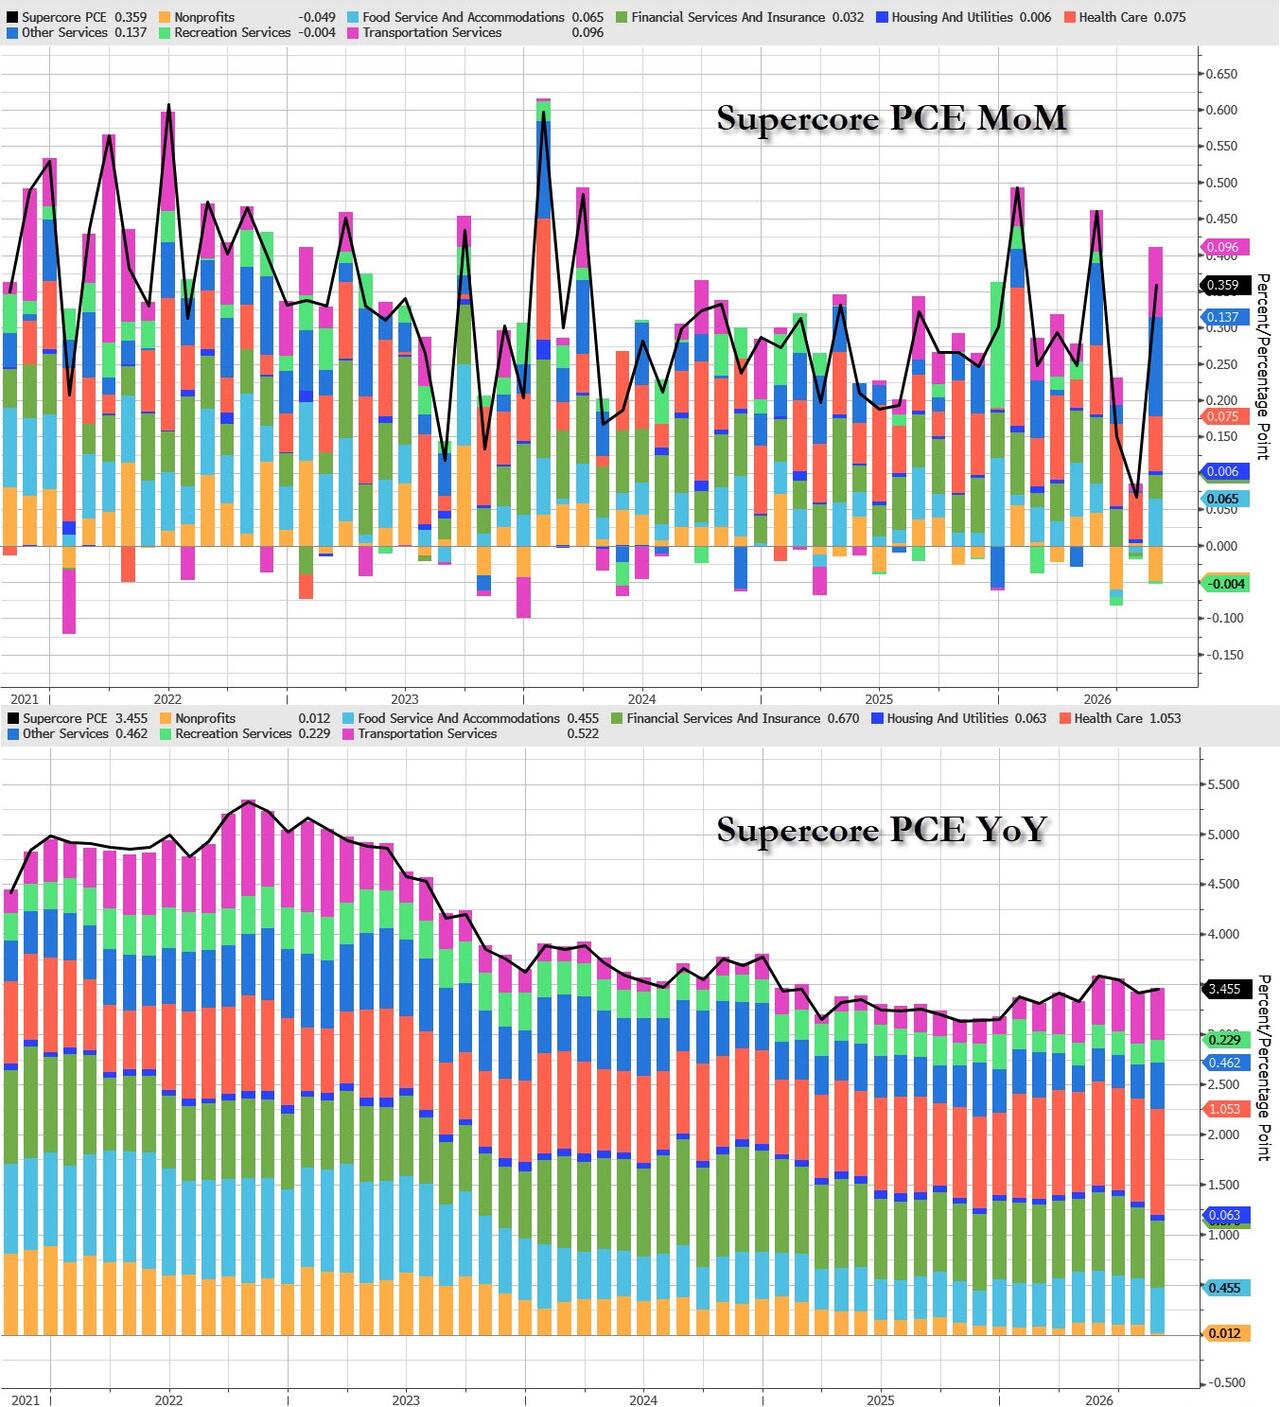
Commenting on the data, David Russell, Global Head of Market Strategy at TradeStation said that “this is good news for investors worried about the recent surge in bond yields, and it bolsters the case for not hiking in October. We might have seen peak hawkishness from the Fed given the recent jump in rates. However, it’s also relatively old data at this point that doesn’t reflect this month’s surge in diesel prices. Investors will remain wary of energy prices as we enter a key period of fuel consumption.“
The inflation-boosted prices were met with much higher spending (+0.9% MoM notional, in line with estimates and up from 0.1% in July) while income growth was dangerously lower, failing to keep up with spending, and rising just +0.2% MoM, which was down from 0.3% in the previous month and missed estimates of 0.5%.
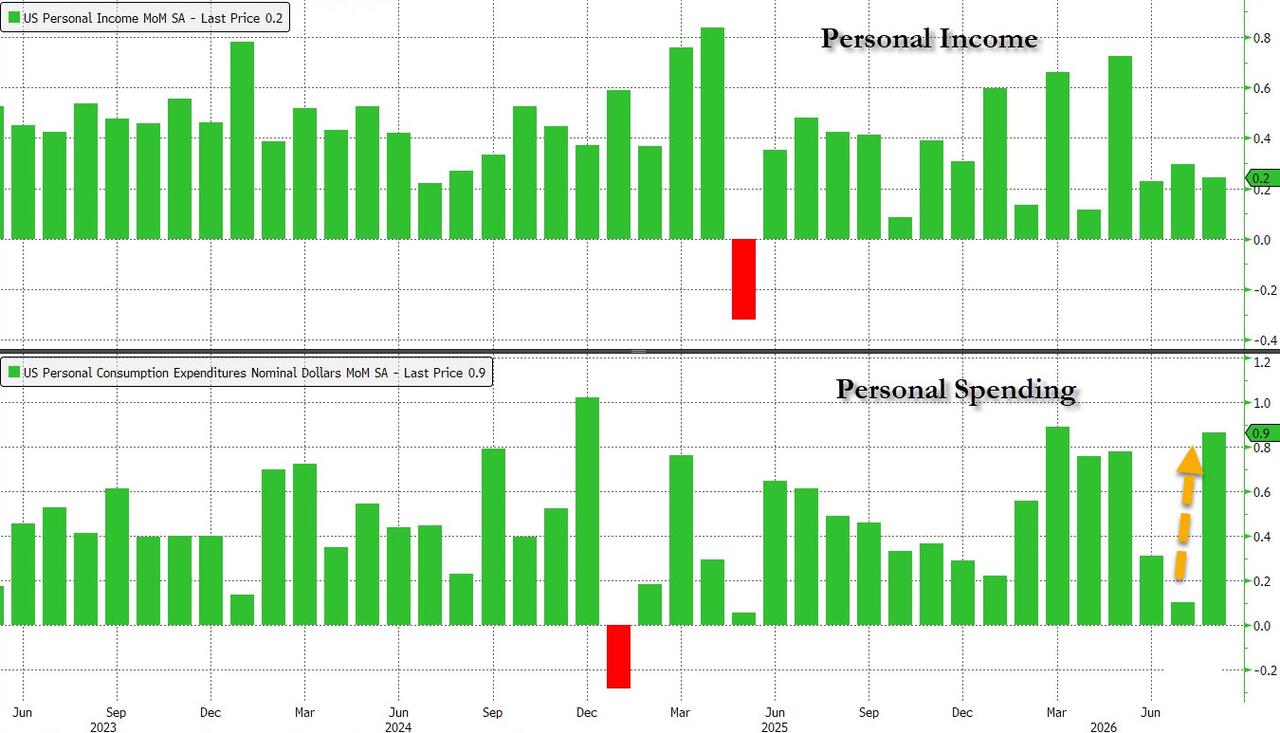
The surprising spike in spending not supported by income, meant that the freshly revised savings rate tumbled again, dropping from 4.6% in July to just 4.1% in August, the lowest since Nov 2022.
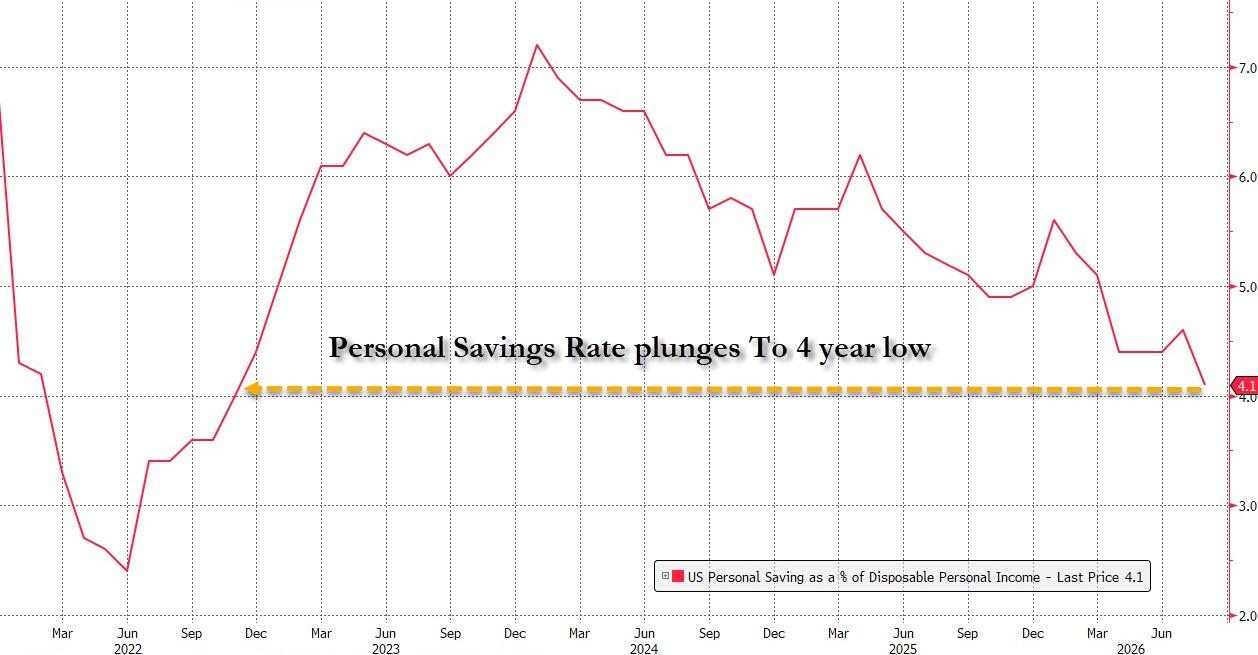
While spending growth rose again, Income growth is now the lowest since April 2022!
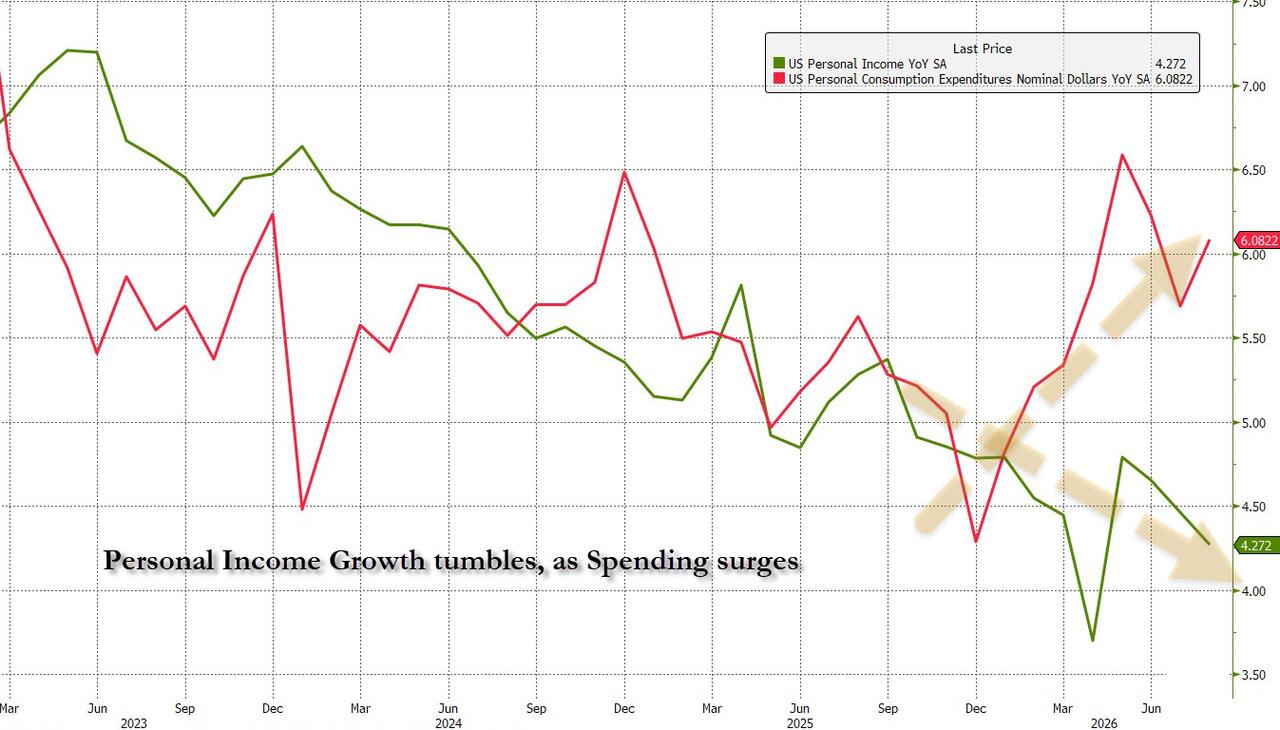
In other words, once again US consumers are failing to keep up with inflation and they can do so only – and temporarily – by digging deep into their savings.
Finally, while the core PCE was indeed lower than expected, recall that as we said above, this is mostly due to a change in methodology. Today, the Bureau of Economic Analysis released its updated PCE deflator methodology, which has been applied retroactively through Q1 2021, with RBC estimating that core PCE’s annual pace is expected to fall 18bps, which would revise July’s reading to 3.1% from 3.3%. They were spot on.
RBC analysts also aid that three changes drive this: portfolio management services will use a CES-based quantity series instead of nominal price deflation; computer software will use a new composite PPI/CPI deflator; and legal services will use a new deflator after the current CPI measure proved unreliable.
In other words, today’s welcome “miss” in core PCE is likely not due to lower prices but due to spreadsheet changes and rebenchmarking.
USA ECONOMIC REPORTS
These Are The Biggest Players In The $13.5 Trillion Repo Market: How Hedge Fund “Basis Trades” & Money Market Funds Fit In
Wednesday, Sep 30, 2026 – 08:45 AM
Authored by Wolf Richter via Wolf Street,
The size of the repo market has ballooned to over $13.5 trillion in outstanding agreements daily, according to the government’s Office of Financial Research (OFR). Via the repo market, financial institutions borrow from, and lend to, each other mostly overnight, but also for longer periods, such as for one week, secured by high-quality liquid collateral with a “haircut.”
About 70% of repos are secured by Treasury securities. The rest are secured by agency securities, such as MBS issued by government-sponsored enterprises (GSEs Fannie Mae and Freddie Mac), and also high-grade corporate bonds and Asset-Backed Securities (with a bigger haircut, the bigger the risk, the bigger the haircut).
Some institutions lend cash to the repo market for the yield and liquidity, such as money market funds. Others lend cash to the repo market to borrow Treasury securities they need for margin requirements on other trades, such as hedge funds. Dealers act as intermediaries between lenders and borrowers.
An analysis by the New York Fed today outlines who the biggest borrowers and lenders in the repo market are.
Biggest cash borrowers in the repo market: Hedge Funds.
Far ahead: Hedge funds (HFs) engaged in the “basis trade” borrowed $3.0 trillion in the repo market as of July 2025, up from $2.5 trillion in July 2024, $1.1 trillion in July 2022, and $664 billion in July 2017, according to the New York Fed’s analysis today (top red line in the chart below).
With the “Treasury cash-futures basis trade,” hedge funds purchase Treasury securities and sell Treasury futures contracts, thereby profiting from the spread between them. But the spread is small, so they lever up their strategy by borrowing cash in the repo market, and putting up the Treasury securities as collateral, thereby multiplying their returns through vast amounts of leverage.
Hedge funds in the basis trade provide liquidity in the Treasury market, as they’re big leveraged buyers of Treasury securities.
But when the basis trade encountered a rough spot in March 2020, and hedge funds had to unwind some of their positions, the Treasury market locked up. The effort to untangle this issue was one of the reasons the Fed cited for its massive Treasury purchases in March 2020.
The Fed has cited hedge funds, with their vast leverage and dense opacity, as a primary risk to financial stability, and they didn’t disappoint in March 2020, and again came to the Fed’s attention for their part in the repo market blowout in the fall of 2019.
Far behind, the next 3 largest borrowers: US branches and agencies of “Foreign Banking Organizations” (FBOs) at $445 billion; US banks (US Depository Institutions or USDIs) at $422 billion; and Real Estate Investment Trusts (REITs), especially mortgage REITs, at $313 billion, as of October 2025, for a combined $1.2 trillion.
Chart via the New York Fed, sources: OFR, Federal Financial Institutions Examination Council (FFIEC), and the St. Louis Fed’s FRED database.
Biggest cash lenders in the repo market: money market funds
Far ahead: Money market funds (MMFs) lent $3.0 trillion to the repo market as of January 2026, having tripled from July 2020. The high occurred in April 2023 at $3.3 trillion (top gray line in the chart below).
Lending to the repo market provides MMFs with short-term investments, including overnight with next-day liquidity, in high-grade securities, backed mostly by Treasuries. Overnight repos allow MMFs to manage their redemptions while keeping their cash invested.
Total MMF balances rose by nearly $1 trillion over the past 12 months, to $8.4 trillion in Q2 2026, including a record $5.1 trillion held by households, and a substantial portion of that was invested in the repo market.
Far behind: Hedge funds (HFs) lent $1.3 trillion to the repo market as of July 2025 (red in the chart below), in part to invest short-term their otherwise uninvested cash; and in part for “collateral transformation” purposes through a dealer where they in effect borrow Treasury securities from the repo market that they then post as collateral, such as to meet strict margin requirements for derivative trades. Hedge fund leverage is multi-layered and complex.
On net, hedge funds are far bigger borrowers from the repo market ($3.0 trillion), than lenders to the repo market ($1.3 trillion), with net borrowing amounting to about $1.7 trillion at that time.
Further behind: US banks (USDIs: $689 billion, brown line, as of October 2025); US branches of foreign banks (FBOs: $419 billion, light blue line, as of October 2025), and the GSEs ($249 billion, dark blue line, as of July 2025):
Chart via the New York Fed, sources: OFR, Federal Financial Institutions Examination Council (FFIEC), and the St. Louis Fed’s FRED database.
The $13.5 trillion repo market interconnects a large spectrum of financial institutions, including dealers, banks, hedge funds, money market funds, and the GSEs, through short-term cash and collateral exchanges.
Due to the repo-market interconnectedness and vastness, liquidity problems in one corner of the repo market – visible when repo rates, such as SOFR, soar – can spiral out into the rest of the financial system in no time.
To tamp down on liquidity issues before they spiral out into the financial system, the Fed set up its Standing Repo Facility (SRF) in July 2021, where approved banks can borrow from the Fed at its SRF rate (4.0% since the rate hike on Sep. 16) and a haircut to lend to the repo market to profit from the spread and bring down repo rates again in the process, which is what they did during the repo market squiggles in September through December 2025, that might have spiraled out into the financial system otherwise:
KING NEWS
| The King Report September 30, 2026 – Issue 7837 | Independent View of the News |
| The Conference Board Consumer Confidence Index fell by 6.7 points to 81.9 in September from 88.6 in August. 90 was consensus. The Present Situation Index—based on consumers’ assessment of current business and labor market conditions—retreated by 7.9 points to 109.3. The Expectations Index—based on consumers’ short-term outlook for income, business, and labor market conditions—fell by 5.9 points to 63.6, its third consecutive monthly decline. The survey period… was September 1-23. While higher-income groups remained generally more optimistic, those with a household income of $125,000-$149,000 reported the greatest decline in confidence over the last six months… Confidence fell in September across all political affiliations—Democrats, Republicans, and Independents… Consumers’ average and median 12-month inflation expectations rose 0.3 ppts in September to 6.1% and 5.1% respectively. The share of consumers anticipating higher interest rates over the next 12 months jumped by 5.2 ppts to 68.4%. Consumers still largely expected stock prices to rise in the next 12 months, but optimism moderated in September… https://www.conference-board.org/topics/consumer-confidence/ The US 30-year yield hit 5.586% (22-year high) and the 10-year yield hit 5.28% at 9:43 ET, the highest yield since June 2002! The 2-year yield hit 4.958% at 1:31 ET. US stocks, except AI bubble stocks and select Fangs declined early on Tuesday. Yes, Virginia, this has been the recurring MO for the US stock market for the past few months. At 10:25 ET: MU +2.4%, NVDA +0.54%, AMD +1.24%, SNDK +1.64%, INTC +0.84%, META +1.04%, AVGO +3.04%; the S&P 500 was down 0.06%; the DJIA was -0.17%; the SOX Index +1.84% The SP 500 Index gapped higher on the opening (7669.60) but it was ‘dumb money’ buying. Their incontinent buying made the opening the daily high. The S&P quickly declined and fell to 76675.30 at 10:49 ET. Traders then bought for the 2nd Hour Reversal. The S&P rallied to 7687.69 at 10:27 ET but rolled over and fell to a new daily low of 7655.55 at 11:24 ET as bond and note yields hit new highs. The US 10-year yield hit 5.289% at 11:23 ET. The 30-year was 5.615% at 11:28 ET. The S&P 500 Index intractably fell to a daily low of 7653.55 at 13:16 ET. The afternoon rally took the S&P 500 Index to 7682.33 at 14:40 ET. The index then fell to 7667.07 at 15:56 ET. The late manipulation forced the S&P to a 7670.84 close, -0.17%. Positive aspects of previous session DJTA +0.35%; Nas 100 +0.21%, SOX Index +1.32%SP Utes +1.14%, Comm Services +0.4%, Industrials +0.19%, Consumer Discretionary +0.05%Nov WTI Oil -3.54, Nov Brent -3.00, Nov Gasoline -2.11¢ at 16:16 ET Negative aspects of previous session S&P 500 -0.17%, DJIA -0.26%, Nasdaq -0.09%SP Energy -0.89%, Materials -0.55%, Consumer Staples -0.54%, Financials -0.37%, Health Care -0.32%,Info Tech -0.28%, Real Estate -0.01%USZs hit a low of 102 20/32, -27/32 and were -12/32 at 16:16 ET; Nov Diesel +2.4¢ at 16:16 ET Ambiguous aspects of previous session Are ‘they’ selling stocks due to end of Q3 rebalancing expectations? First Hour/Last Hour NYSE Action [S&P 500 Index]: 1st Hour: Down; Last Hour: Down. Pivot Point for S&P 500 Index [above/below indicates daily trend to day traders]: 7691.56 Previous session (S&P 500 Index) High/Low: 7699.60 (9:30 ET); 7653.55 (13:16 ET) WSJ: Americans Want Populist Policies That Defy Traditional Political LabelsA new Wall Street Journal survey finds broad support for caps on prescription drug prices and strong border security… Voters of all partisan stripes strongly support capping the cost of prescription drugs, childcare and credit-card interest rates… Today is the end of Q3. There should be pressure from end of Q3 portfolio rebalancing because bonds are historically undervalued, according to most models, versus stocks. Can the ingrained AI stock and trading sardine buying generate a rally? Operators, hedge funds, and institutions are historically over-invested in AI bubble stocks. Ergo, they want to manipulate them higher to game Q3 performance. Will Mr. Bond rally and stocks fall on Q3 portfolio rebalancing? Tuesday night trading indicates that ‘they’ are buying NQZs for the manipulation of AI stocks and trading sardines to game performance. ESZs are not as strong due to fear of portfolio rebalancing (sell stocks/buy bonds). ESZs +20.50; NQZs +118.00, USZs +10/32, Nov WTI -$0.03, Nov Gas -1.22¢, Yen/157.46 at 20:07 ET Expected economic data: Q2 GDP 1.5%, GDP Price Index 6.4% q/q, Aug PCE Price Index 0.4% m/m & 3.7% y/y; Aug Core PCE 0.3 m/m & 3.4%; Q2 PCE 3.6% y/y; Aug Personal Income 0.4% m/m, Spending 0.8%; Sept ADP Employment Change+72k; Aug Goods Trade Balance -$113.5B; Sept Chicago PMI 51; Richmond Fed Pres Barkin 12:30 ET S&P 500 50-day MA: 7645; 100-day MA: 7556; 200-day MA: 7212 (Close 7670.84, -0.18%)Nasdaq 100 50-day MA: 29,356; 100-day MA: 29,452; 200-day MA: 25,400 (Close 30,339.33, +0.21%) DJIA 50-day MA: 52,774; 100-day MA: 52,016; 200-day MA: 50,238 (Close 51,349.92, -0.26%) (Green is positive slope; Red is negative slope) | |
SWAMP STORIES FOR YOU TONIGHT
Fed Watchdog Finds No Crimes In $2.4 Billion Renovation, Just Everything Else
by Tyler Durden
Wednesday, Sep 30, 2026 – 01:31 PM
After more than a year of drama, subpoenas, surprise site visits, hard-hat photo ops and one very public fight over beehives, the Fed’s internal watchdog has finally weighed in on the central bank’s headquarters renovation. The verdict: nobody committed a crime, but almost nobody was minding the budget either.
According to a report released Wednesday by the Fed’s Office of Inspector General, there were no “reasonable grounds to believe that a violation of federal criminal law had occurred,” and no administrative misconduct.
What the OIG did find was a long list of management failures that helped the cost of renovating the Eccles Building and the adjacent 1931 federal building balloon from a budgeted $1.3 billion in 2020 to $2.4 billion:
- The Board never acted on the OIG’s earlier recommendation, made after the Martin Building renovation overran, to set a stated cost limit. It also never asked for a construction cost estimate.
- As recently as July, four years in and with contracts already awarded, the Fed still had not set a guaranteed maximum price.
- Some work drew few or no bids, which pushed costs up substantially.
- Internal governance “wasn’t equipped” to run a project of this size and complexity.
- Design changes, site conditions and, of course, inflation. The OIG said “inflation was clearly a factor,” which is a notable admission from an institution whose one job is controlling inflation.
As for the marble, water features and rooftop garden that critics fixated on, the OIG said they “did not materially drive” the cost surge (so Powell was vindicated on the beehives, if not on the budget).
The new Marriner Eccles sheriff, Fed Chair Kevin Warsh, said the Fed will adopt all of the recommendations, hand management of the project to the General Services Administration (reporting to the Board and to Warsh), and bring in an independent auditor to review every cost awarded to date. “There are important lessons to be learned,” Warsh wrote to IG Michael Horowitz, whom Powell appointed in June 2025.
Frequent ZH readers will remember how this saga played out. In July 2025, with Trump publicly pressing for rate cuts, the renovation became the administration’s preferred lever: Trump said he wouldn’t fire Powell “unless there is fraud w/ renovation” (July 16, 2025). Days later, Powell was criminally referred to the DOJ for perjury (July 21, 2025) over his June 2025 testimony that there was “no VIP dining room, there’s no new marble… there’s no beehives and there’s no roof terrace gardens.” Trump then toured the site in a hard hat alongside Powell (July 24-25, 2025), producing the most awkward cost-overrun negotiation in central banking history. At the time, OMB’s Russ Vought insisted the criticism was “not about firing Powell” but “about holding the Fed accountable.”
Things escalated in January, when the Fed was served with grand jury subpoenas and Powell vowed to “stand firm” (Jan 12, 2026), accusing the administration of using the probe to punish the Fed for not cutting rates:
“This is about whether the Fed will be able to continue to set interest rates based on evidence and economic conditions — or whether instead monetary policy will be directed by political pressure or intimidation.”
Federal prosecutors followed up with a surprise visit to the renovation site, with US Attorney Jeanine Pirro saying any project with “cost overruns of almost 80 percent” deserved “serious review.” Then in March, Judge Boasberg quashed the DOJ subpoena (March 13), calling it “pretextual.” After Republican senators held up Warsh’s confirmation over the probe, Pirro dropped the investigation (April 24), deferring to the very IG report that came out today.
So case closed? Not quite
Pirro said at the time that she would scrutinize the IG’s findings, leaving open the option to reopen the case. And Powell, who broke with tradition by staying on the Board as a governor after his term as chair ended in May, said he would not leave “until this investigation is well and truly over, with transparency and finality.”
Well, Powell can now leave as today’s report gives him the “finality” part. Whether it gives him a reason to leave is another question. And whether a clean bill of health from an IG that Powell himself appointed and whose review Powell himself ordered will satisfy Pirro or the White House is… well, we’ll find out soon enough: keep an eye on Trump’s Truth Social account (especially if like Jane Street and the HFTers you are paying $100,000 to get them 20 millisecond before everyone else).
One thing is certain: a building project that nearly doubled in cost thanks to poor planning, no price cap and “inflation” is a perfect metaphor for the institution it will house.
END
Trump Responds To Watchdog Report: Force Powell Off The Fed Board – Or Sue Him
by Tyler Durden
Wednesday, Sep 30, 2026 – 03:58 PM
Update (1554ET): So much for “finality.”
Minutes after the Fed’s own inspector general cleared the Eccles renovation of criminality – and of administrative misconduct – President Trump made clear he is not treating the Horowitz report as the last word. Powell, Trump said on Truth Social, should be “forced to resign” from the Board of Governors. If he doesn’t, “he should be sued by the US.”
As for the building itself: Trump said Attorney General Todd Blanche will “make a determination” about the project – which is another way of saying the White House does not consider a clean bill of health from an IG Powell appointed, after a review Powell ordered, to be dispositive.
“I have asked Attorney General Todd Blanche to study the report, and make a determination as to what to do about a relatively small Building Complex,” Trump wrote, adding “If he doesn’t resign, he should be sued, at the highest level, by the United States Government, for either corruption or incompetence.”
Pirro deferred to this report in April. Powell said he would stay on the Board until the investigation was “well and truly over, with transparency and finality.” The IG just gave him the no-crime finding. Trump just told him that isn’t enough to keep the seat.
Powell can still sit as a governor through January 2028. Forcing him off that Board – as opposed to waiting out a chair term that already ended in May – is a different fight: for-cause removal, a civil suit, or enough political heat that he walks. Blanche now has the file. Watch Truth Social, and watch whether “determination about the building” turns into a new referral or just another hard-hat presser.
* * *
After more than a year of drama, subpoenas, surprise site visits, hard-hat photo ops and one very public fight over beehives, the Fed’s internal watchdog has finally weighed in on the central bank’s headquarters renovation. The verdict: nobody committed a crime, but almost nobody was minding the budget either.
According to a report released Wednesday by the Fed’s Office of Inspector General, there were no “reasonable grounds to believe that a violation of federal criminal law had occurred,” and no administrative misconduct.
What the OIG did find was a long list of management failures that helped the cost of renovating the Eccles Building and the adjacent 1931 federal building balloon from a budgeted $1.3 billion in 2020 to $2.4 billion:
- The Board never acted on the OIG’s earlier recommendation, made after the Martin Building renovation overran, to set a stated cost limit. It also never asked for a construction cost estimate.
- As recently as July, four years in and with contracts already awarded, the Fed still had not set a guaranteed maximum price.
- Some work drew few or no bids, which pushed costs up substantially.
- Internal governance “wasn’t equipped” to run a project of this size and complexity.
- Design changes, site conditions and, of course, inflation. The OIG said “inflation was clearly a factor,” which is a notable admission from an institution whose one job is controlling inflation.
As for the marble, water features and rooftop garden that critics fixated on, the OIG said they “did not materially drive” the cost surge (so Powell was vindicated on the beehives, if not on the budget).
The new Marriner Eccles sheriff, Fed Chair Kevin Warsh, said the Fed will adopt all of the recommendations, hand management of the project to the General Services Administration (reporting to the Board and to Warsh), and bring in an independent auditor to review every cost awarded to date. “There are important lessons to be learned,” Warsh wrote to IG Michael Horowitz, whom Powell appointed in June 2025.
Frequent ZH readers will remember how this saga played out. In July 2025, with Trump publicly pressing for rate cuts, the renovation became the administration’s preferred lever: Trump said he wouldn’t fire Powell “unless there is fraud w/ renovation” (July 16, 2025). Days later, Powell was criminally referred to the DOJ for perjury (July 21, 2025) over his June 2025 testimony that there was “no VIP dining room, there’s no new marble… there’s no beehives and there’s no roof terrace gardens.” Trump then toured the site in a hard hat alongside Powell (July 24-25, 2025), producing the most awkward cost-overrun negotiation in central banking history. At the time, OMB’s Russ Vought insisted the criticism was “not about firing Powell” but “about holding the Fed accountable.”
Things escalated in January, when the Fed was served with grand jury subpoenas and Powell vowed to “stand firm” (Jan 12, 2026), accusing the administration of using the probe to punish the Fed for not cutting rates:
“This is about whether the Fed will be able to continue to set interest rates based on evidence and economic conditions — or whether instead monetary policy will be directed by political pressure or intimidation.”
Federal prosecutors followed up with a surprise visit to the renovation site, with US Attorney Jeanine Pirro saying any project with “cost overruns of almost 80 percent” deserved “serious review.” Then in March, Judge Boasberg quashed the DOJ subpoena (March 13), calling it “pretextual.” After Republican senators held up Warsh’s confirmation over the probe, Pirro dropped the investigation (April 24), deferring to the very IG report that came out today.
So case closed? Not quite
Pirro said at the time that she would scrutinize the IG’s findings, leaving open the option to reopen the case. And Powell, who broke with tradition by staying on the Board as a governor after his term as chair ended in May, said he would not leave “until this investigation is well and truly over, with transparency and finality.”
Well, Powell can now leave as today’s report gives him the “finality” part. Whether it gives him a reason to leave is another question. And whether a clean bill of health from an IG that Powell himself appointed and whose review Powell himself ordered will satisfy Pirro or the White House is… well, we’ll find out soon enough: keep an eye on Trump’s Truth Social account (especially if like Jane Street and the HFTers you are paying $100,000 to get them 20 millisecond before everyone else).
One thing is certain: a building project that nearly doubled in cost thanks to poor planning, no price cap and “inflation” is a perfect metaphor for the institution it will house.
END
GREG HUNTER….INTERVIEWING WARREN WESTON
Everything Coming to a Head Because of Black Star – Weston Warren
By Greg Hunter On September 29, 2026 In Market Analysis, Political Analysis3 Comments
By Greg Hunter’s USAWatchdog.com
For nearly a year and a half, scientist and inventor Weston Warren has been warning the earthquakes and volcanos you are seeing around the world are not about to die down. The so called “Black Star” slowly passing through our solar system will increase the number of catastrophic geological events. In mid-August, Warren warned of yet another “Black Star – Black Swan Event Coming.” A few weeks later in Nepal, flash floods that killed hundreds, with thousands still missing, hit because of an earthquake. It’s been a long time coming, and it’s not going to stop for several more years. Warren says, “Our understanding is when it (the Black Star) comes in, it comes in hot. Then it starts to slow up, slow up and slow up because of the polarity of the sun and this electromagnetic anomaly. . .. Because of the size of the Earth, it is roughly a 30-year process. So, for 30 years, the Earth’s core (made of nickel and iron) is receiving additional energy. After 30 years, it manifests itself to a crescendo where the magma is super-heated, rises, keeps rising and pushes and pushes until it breaches the crust of the Earth. It breaches areas where you have continental plates.”
Warren made predictions of wild weather, increased earthquakes and volcanos because of the Black Star back in 2007. Warren says, “I am looking at the models that we have, and the models are accurate up to this point, and it has not been proven wrong. According to this, it is at least a 30 year program, and the effects of the Black Star will continue into 2030 or 2031. . .. We have another three to four years of activity, and we are definitely not out of the woods. What we will have is more intensity in the next three or four years. . .. We will have more volcanic eruptions, and that means we will have more volcanic ash. . .. We know there is going to be 10, 12 15 volcanos in the Northern and Southern hemisphere going off. That completely changes the Earth’s temperature and growing seasons. There will be no air traffic, engines will be clogged and the supply chain globally gets interrupted as a ‘Black Swan’ event.”
So, Warren’s models have been correct in predicting what is going on today. His models are showing more earthquakes and more volcanoes than ever before are coming. Warren warns, “Everything is coming to a head. Prophecies, what is happening in our solar system, the world empire, the devaluing of the dollar, the rise of BRICS nations, alternative currencies like blockchain, and this is all happening. Then, you have volcanic activities like a volcano that has been dormant for 1,200 years that is active now. Connect the dots, and this is it. Now, we have entered into the spiritual realm, and prophecies say this event is survivable. This is also a spiritual issue.”
There is much more in the 72-minute interview.
To order bipolar air scrubbing tech from Weston Scientific like the “WS GO” you wear around your neck, click here, or call 573-469-5013.
Join Greg Hunter of USAWatchdog as he goes one-on-one with Weston Warren, scientist and inventor of the bipolar ionization technology. Warren will update us on the Black Star and then increasing damage of Biblical proportions for 9.29.26.
After the Interview:
For more information on any of the products Weston Scientific sells, feel free to call the company by phone at 573-469-5013.


