OCT 20/GOLD CLOSED DOWN $41.05 TO $4164.90 WITH SILVER UP $0.68 TO $57.85//PLATINUM WAS UP $XZXX TO $25.50 WHILE PALLADIUM WAS DOWN $10.50 TO $1107.00/GOLD COMMENTARY TONIGHT COURTESY OF ALASDAIR MACLEOD//COMMENTARY TONIGHT ON GOLD ITSELF//ASIAN REPORTS TONIGHT FROM CHINA WITH EUROPEAN REPORTS ON EUROPE ITSELF AND OF COURSE FRANCE// UK AND GERMANY/UPDATES ON ISRAEL AND USA VS IRAN//ISRAEL TBN AND TOUSI IRAN//SAUDI ARABIA VS HOUTHIS UPDATES// OIL UPDATES/UPDATES ON THE REFERENDUM IN CANADA//USA DATA RELEASES/USA ECONOMIC REPORTS/KING NEWS//
190 H BMO CAPITAL MARKETS 7 363 H WELLS FARGO SECURITI 2 905 C ADM 5
TOTAL: 7 7 MONTH TO DAY 13,079
JPMORGAN STOPPED 0/7
OCT 20
GOLD: NUMBER OF NOTICES FILED FOR OCT./2026: 7 CONTRACTs NOTICES FOR 700 OZ or 0.02177 TONNES
total notices so far: 13,079 contracts FOR 1,307,900 OZ OR 40.6811 TONNES
SILVER NOTICES: 231 NOTICE(S) FILED FOR 1,155,000 OZ /
total number of notices filed so far this month : 3511 CONTRACTS (NOTICES) for 17.555 million oz
Click here if you wish to send a donation. I sincerely appreciate it as this site takes a lot of preparation
GLD AND SLV
BOTH GLD AND SLV ARE FRAUDULENT VEHICLES//THEY ARE NOW RAIDING GLD AND SLV FOR PHYSICAL
GLD
THE CROOKS ARE STEALING GOLD AND SILVER FROM THE GLD/SLV AND REPLACING THE PHYSICAL WITH PAPER DOLLARS.
WITH GOLD DOWN $41.05 INVESTORS SWITCHING TO SPROTT PHYSICAL (PHYS) INSTEAD OF THE FRAUDULENT GLD//NO CHANGES IN GOLD INVENTORY AT THE GLD:///
INVENTORY RESTS AT 1053.91 TONNES
SLV/
WITH NO SILVER AROUND AND SILVER UP $0.68 AT THE SLV: NO CHANGES IN SILVER INVENTORY AT THE SLV:
CLOSING INVENTORY: 497.650 MILLION
SILVER//OUTLINE
SILVER COMEX OI ROSE BY A FAIR 341 CONTRACTS TO AN OI OF 112,392 STILL HIGHER FROM ITS NEW RECORD LOW OF 95,999 SET MAY 1/2026. THE RECORD HIGH OI FOR SILVER IS 244,710, SET FEB 25/2020, AND THIS FAIR GAIN IN COMEX OI WAS ACCOMPLISHED DESPITE OUR LOSS OF $0.04 IN SILVER PRICING AT THE COMEX WITH RESPECT TO MONDAY’S TRADING. ON THE FIRST OF MAY, WE REACHED OUR RECORD LOW OI OF 95,999 SURPASSING EVERY DAY NEW OI LOWS SET DURING THE LAST WEEK OF APRIL 2026.
NOW ON A NET BASIS OUR SPECULATORS HAVE REVERTED BACK TO GOING SHORT. THE FRBNY ON A NET BASIS IS PROVIDING THE NECESSARY PAPER TO OUR LONG BANKERS AND THEN TENDER FOR PHYSICAL AT 4 PM EACH NIGHT. BECAUSE OF THE HUGE SHORTFALL IN PHYSICAL SILVER IN LONDON THERE IS A LOTTERY TO SEE WHO GETS ANY OF THE PHYSICAL SILVER AVAILABLE THAT WHICH THEY ARE OBLIGATED TO DELIVER. THEY WAIT PATIENTLY FOR THEIR PHYSICAL METAL AND IF NOBODY GETS ANY THEY THEN COME BACK THE NEXT DAY AND SO ON. THIS IS IN LONDON, THE HOME OF PHYSICAL SILVER!! THE FACT THAT WE ARE WITNESSING MANY EXCHANGE FOR PHYSICAL TRANSFERS TO LONDON HIGHLIGHTS THE FACT THAT THE COMEX IS OUT OF SILVER AS WELL.
WE ARE NOW MOVING TO A MUCH LOWER BASE IN SILVER PRICING BREAKING MAJOR SUPPORT LEVEL OF $70.00. SHORTLY WE WILL REVERT BACK TO NUMBERS GREATER THAN 70 DOLLARS PER OZ.
WE HAVE A FAIR GAIN OF 329 TOTAL CONTRACTS ON OUR TWO EXCHANGES AS THE CME NOTIFIED US OF A ZERO SIZED ISSUANCE OF 0 CONTRACTS EXCHANGE FOR PHYSICAL ISSUANCE , WE HAD SOME LIQUIDATION OF T.A.S. CONTRACTS IN COMEX TRADING WITH RESPECT TO MONDAY TRADING// WE HAD A HUGE SIZED 461 CONTRACT T.A.S. ISSUANCE!! / THEY DESPERATELY AGAIN TODAY TRYING TO CONTAIN SILVER’S PRICE GAIN FOR THE PAST SEVERAL WEEKS (WHERE RAIDS ARE CALLED UPON AGAIN AND AGAIN TRYING TO STOP THE RISE IN SILVER’S PRICE TO ABOVE $100.00 AND TO QUELL ADDITIONAL DERIVATIVE LOSSES TO OUR BANKERS’ MASSIVE TOTALS).THEY SUCCEEDED ON MONDAY WITH SILVER’S LOSE IN PRICE.
THE PRICE STILL FINISHED BELOW THE MAGIC NUMBER OF $70.00 SILVER SPOT PRICE AND STILL WELL BELOW THE $100.00 MARK CLOSING AT $57.18 DOWN $0.04 WE ARE NOW WITNESSING HAVING MANY HUGE T.A.S ISSUANCES // TODAY’S WE HAD A HUGE SIZED 461 T.A.S. CONTRACTS !!. THE CROOKS ARE BECOMING MORE DESPERATE TO STOP SILVER BREAKING ABOVE THE 100.00 DOLLAR MARK!! AND NOW THE HUGE SUPPORT LEVEL OF 70 DOLLARS HAS BEEN BROKEN// //.MAMMOTH SIZE T.A.S ISSUANCES ARE BECOMING THE NORM AT THE COMEX NOW!!
THERE IS NO NEXT LINE IN THE SAND ONCE THE 100.00 DOLLAR SILVER IS PIERCED AGAIN. WE HAD A ZERO SIZED 0 CONTRACT EXCHANGE FOR PHYSICAL ISSUANCE ACCOMPANIED BY OUR HUGE SIZED 556 CONTRACT T.A.S ISSUANCE WHICH WILL BE USED FOR RAID PURPOSES //AS THEY PLAY AN INTEGRAL PART IN OUR COMEX TRADING TRYING TO CONTAIN ANY SILVER PRICE RISE
IN ESSENCE WE HAD A FAIR SIZED GAIN OF 329 CONTRACTS ON OUR TWO EXCHANGES DESPITE OUR LOSS IN PRICE OF $0.04. WE HAD CONSIDERABLE GOVERNMENT (FRBY) COMEX CONTRACTS TRADING ALL WEEK AND A MAJOR PORTION WILL BE REMOVED BY DAYS END. (I RECORD THIS FOR YOU ON A DAILY BASIS). THE STICKY SPECULATOR LONGS STILL REMAIN STOIC. OUR SILVER SHORT SPECS GOT SLAUGHTERED TO BITS THIS PAST WEEK.
CRAIG HEMKE HAS POINTED OUT THAT THE CROOKS USE THE MID MONTH FOR MANIPULATION AS THEY SELL THEIR BUY SIDE OF THE CALENDAR SPREAD FIRST AND THEN KEEP THE SELL SIDE TO LIQUIDATE AT A LATER DATE.
THUS WE HAVE TWO VEHICLES THE CROOKS USE FOR MANIPULATION AND BOTH ARE SPREADERS: 1)MONTH’S END/SPREADERS COMEX AND 2/ TAS SPREADERS, THROUGHOUT MONTH. TOTAL TAS ISSUED ON MONDAY NIGHT//TUESDAY MORNING: A HUGE SIZED 461 CONTRACTS. DESPITE MANY COMPLAINTS THAT THESE CROOKS HAVE VIOLATED POSITION LIMITS DUE TO THE FACT THAT THE TAS ISSUED HAVE A VALUE OF ZERO (AS TO POSITION LIMITS FOR OUR CROOKED FRBNY BANKERS).
THE PROBLEM OF COURSE IS THAT THE CROOKS DO NOT LIQUIDATE THE TAS AS ONE UNIT, BUT SELL THE SHORT SIDE FIRST AND THEN LIQUIDATE THE LONG SIDE TWO MONTHS HENCE. IT IS OBVIOUS MANIPULATION TO THE HIGHEST DEGREE BUT IT NATURALLY FELL ON DEAF EARS WITH OUR REGULATORS (OCC) WHEN THEY RECEIVED OUR COMPLAINTS. IT NOW SEEMS THAT THE OCC HAS NOW ORDERED THE BANKS TO REDUCE ITS NEW LEVEL OF 1.1 TRILLION DOLLDOLLARS IN GOLD/SILVER DERIVATIVES.
THUS:
INITIAL STANDING FOR JANUARY: 22.915 MILLION OZ FOLLOWED BY TODAY’S 1.185 MILLION OZ QUEUE JUMP//NEW NORMAL STANDING ADVANCES TO 49.445 MILLION OZ// TO WHICH WE ADD OUR FIRST EXCHANGE FOR RISK FOR .100 MILLION OZ//NEW STANDING ADVANCES TO 49.545 MILLION OZ!!
INTIAL STANDING FOR FEBRUARY/SILVER: 13.505 MILLION OZ FOLLOWED BY TODAY’S HUGE 0.005 MILLION OZ QUEUE JUMP / : NEW STANDING FOR SILVER AT THE COMEX ADVANCES TO 25.180 MILLION OZ. BUT WE MUST ADD OUR FIRST EXCHANGE FOR RISK OF 25 CONTRACTS FOR .125 MILLION OZ AND THEN OUR SECOND EXCHANGE FOR RISK OF .0600 MILLION OZ TO OUR THIRD HUGE 2.825 MILLION OZ EXCHANGE FOR RISK!!
INITIAL STANDING FOR MARCH: A SURPRISINGLY LOW 31.076 MILLION OZ/ FOLLOWED BY A TINY QUEUE JUMP OF XX CONTRACTS OR XXX OZ/NEW STANDING ADVANCES TO 46.060 MILLION OZ
INITIAL STANDING FOR APRIL: 7.120 MILLION OZ FOLLOWED BY TODAY’S 1 CONTRACT QUEUE JUMP WHERE 5,000 OZ WILL TAKE DELIVERY OVER ON THIS SIDE OF THE POND. NEW STANDING FOR SILVER AT THE COMEX THUS ADVANCES SLIGHTLY TO 16.565 MILLION OZ PLUS WE MUST ADD OUR 4TH EXCHANGE FOR RISK ISSUANCE OF 17 CONTRACTS OR 0.085 MILLION OZ. THESE WILL BE ADDED TO OUR OTHER 3 ISSUANCES //NEW TOTAL EXCHANGE FOR RISK//1.165 MILLION OZ// NEW TOTAL SILVER STANDING 17.730 MILLION OZ//
INITIAL STANDING FOR MAY: 31.495 MILLION OZ FOLLOWED BY ANOTHER 3 CONTRACT EXCHANGE FOR PHYSICAL JUMP TO LONDON FOR 0.015 MILLION OZ// AND THEN TO BOOT WE HAD OUR FIRST EXCHANGE FOR RISK ISSUANCE FOR 51 CONTRACTS OR 255,000 OZ MAY 21./STANDING BEFORE EXCHANGE FOR RISK: 32.070 MILLION OZ/NEW STANDING THUS REDUCES TO 32.325 MILLION OZ/.//(32.070 MILLION OZ NORMAL STANDING PLUS .255 MILLION OZ EXCHANGE FOR RISK = 32.325 MILLION OZ)
JUNE INITIAL STANDING FOR SILVER:10.935 MILLION OZ TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 10,000 OZ//NEW STANDING ADVANCES TO 12.970 MILLION OZ// TO WHICH WE ADD OUR FIRST EXCHANGE FOR RISK OF 20 CONTRACTS FOR 100,000 OZ//NEW STANDING ADVANCES TO 13.070 MILLION OZ. (IN EXCHANGE FOR RISK THE BUYER ASSUMES THE RISK AND ONLY A CENTRAL BANK WOULD TAKE THAT RISK. THE BUYER IS PROBABLY THE CENTRAL BANK OF INDIA.)
JULY INITIAL STANDING: 37.110 MILLION OZ FOLLOWED BY A 3 CONTRACT QUEUE JUMP OR 0.015MILLION STANDING ADVANCES TO 45.875 MILLION OZ///
AUGUST INITIAL STANDING 6.240 MILLION OZ FOLLOWED BY TODAY’S 9 CONTRACT QUEUE JUMP FOR 45,000 OZ//NEW STANDING ADVANCES TO 8.760 MILLION OZ/
SEPT: INITIAL STANDING: 24.172 MILLION OZ//FOLLOWED BY TODAY’S STRONG 70 CONTRACT OR 350,000 OZ QUEUE JUMP//STANDING ADVANCES TO 33.865 MILLION OZ//
OCT: INITIAL STANDING: 16.355 MILLION OZ FOLLOWED BY TODAY’S 2 CONTRACT OR 10,000 OZ EXCHANGE FOR PHYSICAL TRANSFER JUMP TO LONDON TO WHICH WE ADD OUR 2ND EXCHANGE FOR RISK, 250 CONTRACTS FOR 1.25 MILLION OZ/ EXCHANGE FOR RISK TOTALS FOR THE MONTH: 2.25 MILLION OZ///NEW STANDING REDUCES AT 19.895 MILLION OZ//
SUMMARY OF OUR JULY 2026 COMEX CONTRACT MONTH
WE HAD:
/ STRONG COMEX LOSS+// A ZERO SIZED EFP ISSUANCE CONTRACTS AT 0 CONTRACTS // A HUGE NUMBER OF T.A.S. CONTRACT ISSUANCE CONTRACTS (556 CONTRACTFS)
I AM NOW RECORDING THE DIFFERENTIAL IN OI FROM PRELIMINARY TO FINAL: ADDED 12 CONTRACTS OF OI SILVER //
HISTORICAL ACCUMULATION OF EXCHANGE FOR PHYSICALS OCT.. ACCUMULATION
TOTAL CONTRACTS for 15 DAY(S), total 7017 contracts: OR 35.085 MILLION OZ (467 CONTRACTS PER DAY)
TOTAL EFP’S FOR THE MONTH SO FAR:35.085 MILLION OZ
LAST 48 MONTHS TOTAL EFP CONTRACTS ISSUED IN MILLIONS OF OZ:
MAY 137.83 MILLION
JUNE 149.91 MILLION OZ
JULY 129.445 MILLION OZ
AUGUST: MILLION OZ 140.120
SEPT. 28.230 MILLION OZ//
OCT: 94.595 MILLION OZ
NOV: 131.925 MILLION OZ
DEC: 100.615 MILLION OZ
YEAR 2022
JAN 2022-DEC 2022
JAN 2022// 90.460 MILLION OZ
FEB 2022: 72.39 MILLION OZ//
MARCH 2022: 207.140 MILLION OZ//A NEW RECORD FOR EFP ISSUANCE
APRIL: 114.52 MILLION OZ FINAL//LOW ISSUANCE
MAY: 105.635 MILLION OZ//
JUNE: 94.470 MILLION OZ
JULY : 87.110 MILLION OZ
AUGUST: 65.025 MILLION OZ
SEPT. 74.025 MILLION OZ///FINAL
OCT. 29.017 MILLION OZ FINAL
NOV: 134.290 MILLION OZ//FINAL
DEC, 61.395 MILLION OZ FINAL
TOTALS YR 2022: 1135.767 MILLION OZ (1.1356 BILLION OZ)
JAN 2023/// 53.070 MILLION OZ //FINAL
FEB: 2023: 100.105 MILLION OZ/FINAL//MUCH STRONGER ISSUANCE VS THE LATTER TWO MONTHS.
MARCH 2023: 112.58 MILLION OZ//FINAL//STRONG ISSUANCE
APRIL 111.035 MILLION OZ(SLIGHTLY GREATER THAN THAN LAST MONTH)
MAY 66.120 MILLION OZ/INITIAL (MUCH SMALLER THIS MONTH)
JUNE: 110.395 MILLION OZ//MUCH LARGER THAN LAST MONTH
JULY 85.745 MILLION OZ (SMALLER THAN LAST MONTH)
AUGUST: 171.43 MILLION OZ (THIS MONTH IS GOING TO BE HUGE //2ND HIGHEST ON RECORD
SEPT: 72.705 MILLION OZ (SMALLER THIS MONTH)
OCT: 97.455 MILLION OZ
NOV. 50.050 MILLION OZ
DEC. 66.140 MILLION OZ//
TOTAL 2023: 1,104.10 MILLION OZ/
JAN ’24 : 78.655 MILLION OZ//
FEB /2024 : 66.135 MILLION OZ./FINAL
MARCH: 143.750 MILLION OZ// 4TH HIGHEST ON RECORD.
APRIL: 161.770 MILLION OZ (THIS MONTH WILL BE A WHOPPER OF ISSUANCE OF EFPS//3RD HIGHEST EVER RECORDED FOR A MONTH)
MAY: 135.995 MILLION OZ //WILL BE A STRONG MONTH FOR EXCHANGE FOR PHYSICAL ISSUANCE
JUNE 110.575 MILLION OZ ( WILL BE ANOTHER STRONG MONTH ISSUANCE)
JULY: 108.870 MILLION OZ (WILL BE A STRONG ISSUANCE MONTH/ A TOUCH OVER 100 MILLION OZ/)
AUGUST; 99.740 MILLION OZ//THIS MONTH WILL BE STRONG FOR ISSUANCE BUT LESS THAN JULY.
SEPT: 112.415 MILLION OZ//WILL BE A HUGE MONTH FOR EXCHANGE FOR PHYSICAL ISSUANCE
OCT; 97.485 MILLION OZ (WILL BE SMALLER ISSUANCE THIS MONTH )
NOV. 115.970 MILLION OZ ( HUGE THIS MONTH)
DEC: 132.54 MILLION OZ (THIS MONTH WILL BE A HUMDINGER FOR ISSUANCE BUT ISSUANCE SLOWED DRAMATICALLY THESE PAST FIVE DAYS/// WILL NOT EXCEED MARCH 2022 RECORD OF 209 MILLION OZ
YEAR 2024 TOTAL: 1363.84 MILLION OR 1.363 BILLION OZ
JANUARY 2025: 67.230 MILLION OZ///(THIS MONTH’S ISSUANCE OF EXCHANGE FOR PHYSICAL WILL BE SMALL)
FEB. 58.260 MILLION OZ//EXCHANGE FOR PHYSICAL ISSUANCE/FINAL
MARCH: 67.020 MILLION OZ///QUITE SMALL AND BECOMING SMALLER EACH AND EVERY MONTH.
APRIL: 100.895 MILLION OZ///AVERAGE SIZE ISSUANCE
MAY: 28.975 MILLION OZ (ISSUANCE WILL BE QUITE SMALL THIS MONTH)
JUNE: 81.065 MILLION OZ
JULY: 50.925 MILLION OZ (QUITE SMALL)
AUGUST: 59.455 MILLION OZ (QUITE SMALL)
SEPT. 50.510 MILLION OZ.(QUITE SMALL)
OCT; 82.020 MILLION OZ (WILL BE STRONG THIS MONTH)/ OCC WANTS TO REIN IN THESE ISSUANCES!
NOVEMBER: 36.425 MILLION OZ
DEC: 45.765 MILLION OZ
2026:
JANUARY 2026: 134.270 MILLION OZ (WILL BE A VERY STRONG MONTH FOR EXCHANGE FOR PHYSICAL!)
FEB : 82.130 MILLION OZ
MARCH: 56.075 MILLION OZ
APRIL; 44.44 MILLION OZ//FINAL.. SMALL THIS MONTH.
MAY 59.79 MILLION OZ
JUNE. 64.065 MILLION OZ//FINAL AND FAIR SIZED THIS MONTH.
JULY: 38.335 MILLION OZ
OCT : 35.085 MILLION OZ.
RESULT: WE HAD A FAIR SIZED INCREASE IN COMEX OI SILVER COMEX CONTRACTS OF 329 CONTRACTS DESPITE OUR LOSS IN PRICEOF $0.04 IN SILVER PRICING AT THE COMEX// FRIDAY THE CME NOTIFIED US THAT WE HAD A ZERO SIZED CONTRACT EFP ISSUANCE OF 0 CONTRACTS ISSUED FOR DEC, AND 0 CONTRACTS ISSUED FOR ALL OTHER MONTHS).
INITIAL STANDING: 16.355 MILLLION OZ FOLLOWED BY TODAY’S 10,000 OZ EXCHANGE FOR PHYSICAL JUMP TO LONDON TO WHICH WE ADD OUR TWO EXCHANGE FOR RISK ISSUANCE:/: NEW EXCHANGE FOR RISK 2.25 MILLION OZ/// STANDING LOWERS 19.895 MILLION OZ
LAST 17 MONTHS OF SILVER DELIVERIES
WE FINISHED APRIL WITH A STRONG SILVER OZ STANDING OF 16.050 MILLION OZ NORMAL DELIVERY , PLUS OUR 4.00 MILLION EX FOR RISK
FINAL STANDING APRIL: 19.965 MILLION OZ
AND MAY:
NEW STANDING FOR MAY FINISHES AT: 75.615 MILLION OZ. (INCLUDES 5,000 OZ EFP TRANSFER TO LONDON + 12.93 MILLION OZ EXCHANGE FOR RISK ISSUANCE/PRIOR.//NEW TOTAL STANDING 88.540 MILLION OZ
AND JUNE: FINAL 16.995 MILLION OZ
AND JULY: 46.720 MILLION OZ//
AUGUST: 4.70 MILLION OZ INITIAL STANDING PLUS TODAY;S 5,000 OZ QUEUE JUMP //NEW STANDING ADVANCES TO 10.960 MILLION OZ
SEPTEMBER: 68.040 MILLION OZ NORMAL DELIVERY(INCLUDES ALL QUEUE JUMPING AND EXCHANGE FOR PHYSICAL TRANSFERS) PLUS 3.0 MILLION OZ EX FOR RISK = 71.040 MILLION OZ. (THIS IS THE FIRST AND ONLY ISSUANCE OF EXCHANGE FOR RISK FOR SILVER SINCE MAY.)
OCTOBER: 39.565 MILLION OZ OF NORMAL DELIVERY INCLUDES ALL QUEUE JUMPING
PLUS
2.110 MILLION OZ EXCHANGE FOR RISK//TOTAL OZ STANDING IN OCT ADVAN
NOVEMBER: INITIAL STANDING AT 11.575 MILLION OZ FOLLOWED BY TODAY’S 195,000 OZ QUEUE JUMP WHICH FOLLOWS ALL OTHER QUEUE JUMPS OF 9.155 MILLION OZ//STANDING ADVANCES TO 19.670 MILLION OZ/
DECEMBER: INITIAL AMOUNT STANDING FOR DELIVERY: 49.33 MILLION OZ// FOLLOWED BY ANOTHER STRONG 835,000OZ QUEUE JUMP+ DEC. FIRST EXCHANGE FOR RISK 0F .850 MILLION OZ + LAST WEEK.S 495,000 OZ EXCHANGE FOR RISK AND THEN A 3RD ISSUANCE IF 1.00MILLION OZ THEN FINALLY DEC 249ISSUANCE OF 1.35 MILLION OZ EXCHANGE FOR RISK//NEW TOTAL EX FOR RIS IS 3.685 MILLION OZ // STANDING ADVANCES TO 68.415 MILLION OZ//
JANUARY: INITIAL STANDING 22.915 MILLION OZ FOLLOWED BY TODAY’S 1.185 MILLION OZ QUEUE JUMP//NORMAL STANDING ADVANCES TO 49.445 MILLION OZ// TO WHICH WE ADD OUR FIRST EXCHANGE FOR RISK OF 0.100 MILLLION OZ//NEW STANDING ADVANCES TO 49.545 MILLION OZ
FEB: 13.399 MILLION OZ IS OUR INITIAL STANDING FOR SILVER! TO WHICH WE ADD OUR NEXT QUEUE JUMP FOR 5,000 OZ AND THEN ADD OUR 3 EXCHANGE FOR RISK FOR 3.010 MILLION OZ STANDING ADVANCES TO 28.190 MILLION OZ!!
MARCH: INITIAL AMOUNT OF SILVER STANDING IS 31.076 MILLION OZ FOLLOWED BY A FINAL 0.210 MILLION OZ QUEUE JUMP //NEW TOTAL STANDING ADVANCES TO 46.060 MILLION OZ
APRIL 2026: INITITAL AMOUNT OF SILVER STANDING 7.120 MILLION OZ FOLLOWED BY TODAY’S 5,000 OZ QUUE JUMP //NEW STANDING ADVANCES TO 16.565MILLION OZ PLUS 1.165 MILLION OZ EXCHANGE FOR RISK.NEW TOTALS 17.730 MILLION OZ
MAY: INITIAL AMOUNT OF SILVER WILLING TO STAND; 31.495 MILLION OZ/ TO WHICH WE ADD OUR NEXT EXCHANGE FOR PHYSICAL JUMP OF 15,000 OZ//NEW STANDING REDUCES TO 32.070 MILLION OZ//(FOLLOWING MANY EXCHANGE FOR PHYSICAL TRANSFERS TO LONDON DURING THIS MAY DELIVERY MONTH). THERE SEEMS TO BE A SCARCITY OF SILVER OVER AT THE COMEX). THEN WE ADD OUR FIRST EXCHANGE FOR RISK OF 51 CONTRACTS FOR 255,000 OZ//STANDING ADVANCES TO 32.325 MILLION OZ//
JUNE: INITIAL AMOUNT OF SILVER WILLING TO STAND: 10.935 MILLION OZ PLUS OUR NEXT QUEUE JUMP OF 10,000 OZ//NEW STANDING ADVANCES TO 12.960 MILLION OZ TO WHICH WE ADD OUR FIRST EXCHANGE FOR RISK OF 20 CONTRACTS FOR 100,000 OZ//NEW STANDING ADVANCES TO 13.070 MILLION OZ
JULY : INITIAL STANDING: 37.110 MILLION OZ FOLLOWED BY TODAY’S 15,000 OZ QUEUE JUMP //STANDING THUS ADVANCES TO 45.875 MILLION OZ//
AUGUST 6.240 MILLION OZ FOLLOWED BY TODAY’S 45,000 OZ QUEUE JUMP//STANDING ADVANCES TO 8.805 MILLION OZ/
SEPT: INITIAL STANDING 8.756 MILLION OZ//FOLLOWED BY TODAY’S 350,000 OZ QUEUE JUMP//STANDING ADVANCES TO 33.865 MILLION OZ
OCT: INITIAL STANDING: 16.355 MILLION OZ//FOLLOWED BY TODAY’S 10,000 OZ EXCHANGE FOR PHYSICAL TRANSFER JUMP TO LONDON TO WHICH WE ADD OUR NEXT EXCHANGE FOR RISK ISSUANCE OF 1.25 MILLION OZ TO OUR FIRST EXCHANGE FOR RISK AT 1.0 MILLION OZ//STANDING REDUCES TO 19.895 MILLION OZ/
THE NEW TAS ISSUANCE FOR TODAY (461)WILL BE PUT INTO “THE BANK” TO BE COLLUSIVELY USED NO DOUBT WITH FUTURE TRADING//.
WE HAD 231 NOTICE(S) FILED TODAY FOR 1.155 MILLION OZ
GOLD COMEX OUTLINE;
IN GOLD, THE COMEX OPEN INTEREST ROSE BY A SMALL SIZED 520 OI CONTRACTS UP TO 400,499 CONTRACT OI AND THIS OI STILL SURPASSES BY A CONSIDERABLE MARGIN THE ALL TIME LOW AT 326,052 SET JUNE3/2026 AND THIS OI IS MUCH FURTHER FROM THE RECORD HIGH (SET JAN 24/2020) AT 799,105 AND PREVIOUS TO THAT: (SET JAN 6/2020) AT 797,110. WE HAVE NOW ADVANCED PAST THE PREVIOUS ALL TIME LOWS OF 357,136 SET APRIL 2/.2026AND 354,581 SET AT THE END OF APRIL 2026. WE ARE STILL QUITE A WAY FROM OUR TWO DECADES OLD: 390,000 CONTRACTS LOW SET IN THE YEAR OF 2001 WITH TRADING FOR GOLD AT $260.00. THUS DURING EARLY APRIL WE HAD A PRESENT TIME LOW OI IN COMEX (354,531) BUT WITH AN EXTREMELY HIGH PRICE OF GOLD. IN MAY: RECORD LOW OI OF 326,052 WITH A GOLD PRICE OF $4,460 THE SHORT RATS ARE ABANDONING THE COMEX SHIP, NOBODY WANT TO PLAY IN THIS CROOKED CASINO!!
THE DIFFERENTIAL FROM PRELIMINARY OI TO FINAL OI IN GOLD TODAY: REMOVED 1399 OI CONTRACTS //.
WE HAD A FAIR GAIN OF CONTRACTS ON OUR TWO EXCHANGES OF 5485 CONTRACTS DESPITE THE LOSS IN PRICE OF $19.65.
LAST 17 MONTHS OF GOLD DELIVERIES: (MAY 2025 THROUGH TO /AUGUST 2026)
1.MAY SUMMARY FOR MAY TONNES WHICH STOOD FOR DELIVERY:
FINAL STANDING FOR MAY: 70.174 TONNES OF GOLD TO WHICH WE ADD 1. MONDAY’S (MAY 19) 6.221 TONNES EXCHANGE FOR RISK , 2. THEN WE ADD: 1.35 TONNES TO LAST WEEK”S. THEN WE ADD 3. 1.55 TONNES TO EQUAL 9.591 TONNES// NEW EXCHANGE FOR RISK = 9.591 TONNES WHICH MUST BE ADDED TO OUR NORMAL DELIVERY SCHEDULE OF 80.644 TONNES. THUS STANDING FOR MAY INCREASES TO 90.235 TONNES OF GOLD
2 JUNE CONTRACT MONTH: 93.085 TONNES OF GOLD (WHICH INCLUDES ALL QUEUE JUMPING AND 0 EX FOR RISK)
3.JULY INITIIAL STANDING FIRST DAY NOTICE: 17.847 TONNES. PLUS TODAY’S 0 TONNES QUEUE JUMP + 1.555 TONNES EX FOR RISK + 2.195 TONNES EX FOR RISK TODAY = 41.106 TONNES STANDING
4. AUGUST: 60.547 TONNES OF INITIAL GOLD FIRST DAY NOTICE FOLLOWED BY THE NET MONTH’S QUEUE JUMP OF 47.2312 TONNES TO WHICH WE ADD THE FOLLOWING EXCHANGE FOR RISK ISSUANCE RECEIVED FOR THE MONTH: 5.4432 TONNES EX FOR RISK/AUG 7 , AUG 11: 2.413 TONNES EX FOR RISK AND AUG. 12 OF 2.
5.SEPT: INITIAL 8.093 TONNES OF GOLD PLUS TODAY’S QUEUE JUMP OF 0.4883 TONNES PLUS 2.2827 TONNES OF EXCHANGE FOR RISK TODAY//NEW TOTAL EX. FOR RISK/MONTH = 22.923//NEW TOTAL STANDING FOR GOLD SEPT ADVANCES TO = 48.801 TONNES!!
6.OCTOBER: 90.012 TONNES OF INITIAL GOLD STANDING WITH TODAY’S SMALL 0.03 TONNES QUEUE JUMP WHICH FOLLOWS ALL OTHER QUEUE JUMPS DURING OCT OF 76.1656 TONNES
THEN WE MUST ADD OUR 14.553 TONNES OF OUR ISSUANCE OF EXCHANGE FOR RISK/6 OCCASIONS//NEW TOTAL OF GOLD STANDING ADVANCES TO 197.5141 TONNES OF GOLD.
7.NOVEMBER BEGINS WITH 15.651 TONNES INITIALLY STANDING FOR DELIVERY FOLLOWED BY TODAY’S QUEUE JUMP OF 2.323 TONNES FOLLOWED BY ALL PREVIOUS QUEUE JUMPS IN OF OF 21.3775 TONNES TO WHICH WE ADD OUR TWO EXCHANGE FOR RISK ISSUANCE OF 4.5596 TONNES//NEW STANDING ADVANCES TO 43.9716 TONNES OF GOLD.
8. DECEMBER BEGINS WITH INITIAL STANDING OF 83.813 TONNES OF GOLD FOLLOWED BY TODAY’S 0.0TONNE QUEUE JUMP WHICH FOLLOWS ALL OTHER QUEUE JUMPS OF: 37.163 TONNES//NEW STANDING ADVANCES TO 115.390 TONNES TO WHICH WE ADD OUR 4 EXCHANGE FOR RISK FOR DECEMBER OF 6.587 TONNES/NEW STANDING ADVANCES TO 121.977 TONNES
9. JANUARY: INITITAL STANDING: 13.785 TONNES TO WHICH WE ADD OUR FIRST EXCHANGE FOR PHYSICAL TRANSFER OF 0.08709 TONNES WHICH FOLLOWS ALL OTHER QUEUE JUMPS OF 30.7117TONNES //NEW TOTAL QUEUE JUMPS 30.7117//NORMAL DELIVERY OF GOLD ADVANCES TO 36.8958 TONNES TO WHICH WE ADD OUR SIX EXCHANGE FOR RISK OF 22.315 TONNES//NEW STANDING ADVANCES TO 59.2108 TONNES.
FEB; INITIAL AMOUNT OF GOLD STANDING FOR DELIVERY: 93.567 TONNES OF GOLD TO WHICH WE ADD OUR NEXT 0.0248 TONNES 0.1555 TONNES QUEUE JUMP TO 41.2082 TONNES/ NEW NET QUEUE JUMP INCREASES TO 41.233 TONNES// AND THEN WE ADD OUR SIX EXCHANGE FOR RISK: 10,080 CONTRACTS OR 31.251 TONNES//NEW STANDING REDUCES TO 157.878 TONNES
MARCH:: INITIAL AMOUNT OF GOLD STANDING FOR DELIVERY: 8.099 TONNES TO WHICH WE ADD TODAY’S FAIR 4600 OZ QUEUE JUMP (0.2320 TONNES) AND THEN WE ADD OUR THREE EXCHANGE FOR RISK OF 22.3818 TONNES //NEW STANDING ADVANCES TO 67.6648 TONNES/
APRIL: INITIAL AMOUNT OF GOLD STANDING FOR DELIVERY: 52.600 TONNES FOLLOWED BY OUR 345 CONTRACT QUEUE JUMP FOR 34,500 OZ/ (1.073 TONNES)/NEW STANDING ADVANCES TO 70.286 TONNES TO WHICH WE ADD OUR 2ND EXCHANGE FOR RISK OF 1498 CONTRACTS FOR 149800 OZ OR 4.659 TONNES. THE NEW TOTAL EXCHANGE FOR RISK FOR THE MONTH OF APRIL IS 2239 CONTRACTS OR 223900 OZ OR 6.964 TONNES AND THIS WILL BE ADDED TO OUR NORMAL DELIVERY TOTALS (70.762 TONNES) TO GIVE US WHAT WILL STAND IN APRIL (77.726 TONNES)
MAY: INITIAL AMOUNT OF GOLD WILLING TO STAND: 12.24 TONNES OF GOLD TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 345 CONTRACTS OR 34500 OZ (1.073 TONNES) TO WHICH WE ADD OUR FIVE EXCHANGE FOR RISK ISSUANCES FOR 24.635 TONNES/STANDING NOW ADVANCES TO 51.554 TONNES OF GOLD.
JUNE; INITIAL AMOUNT OF GOLD WILLING TO STAND; 64.496 TONNES.(CME CORRECTED) TO WHICH WE ADD OUR NEXT EXCHANGE FOR PHYSICAL TRANSFER OF 0.0186 TONNES/NEW STANDING REDUCES TO 127.03 TONNES
JULY: INITIAL AMOUNT OF GOLD WILLING TO STAND: 23.306 TONNES TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 0.000 TONNES/ TO WHICH WE ADD OUR FIRST EXCHANGE FOR RISK 0F 0.0062 TONNES/NEW STANDING ADVANCES TO 40.824TONNES
AUGUST INITIAL STANDING 48.687 TONNES TO WHICH WE ADD OUR 5TH EXCHANGE FOR RISK OF 5 CONTRACTS FOR 500 OZ OR 0.0155 TONNESS TO OUR 4TH EXCHANGE FOR RISK OF 200 CONTRACTS OR 20,000 OZ OR 6.220 TONNES TO OUR 3RD EXCHANGE FOR RISK OF 1.7045 TONNES TO OUR 2ND EXCHANGE FOR RISK OF 1.552 TONNES TO OUR FIRST 0.0715 TONNES EXCHANGE FOR RISK//NEW TOTAL EXCHANGE FOR RISK: 3.9688 AND THEN ADD OUR NEXT QUEUE JUMP OF 39 CONTRACTS FOR 3,900 OZ OR 0.1213 TONNES//STANDING THUS ADVANCES TO 67.2441 TONNES
SEPT: INITIAL STANDING: 8.756 TONNES OF GOLD FOLLOWED BY TODAY’S XX CONTRACTS OR XXX OZ QUEUE JUMP (0.01866 TONNES) TO WHICH WE ADD OUR TWO, 2000 CONTRACT EXCHANGE FOR RISK FOR 200,000 OZ OR 6.2208 TONNES//// // NEW STANDING REMAINS AT 19.2308 TONNES..
OCT: INITIAL STANDING: 38.345 TONNES OF GOLD FOLLOWED BY TODAY’S QUEUE JUMP OF 10,000 OZ (1.617 TONNES) TO WHICH WE ADD TO OUR 2ND EXCHANGE FOR RISK AT 1 CONTRACT TO OUR FIRST 836 CONTRACTS// NEW TOTALS(83,700 OZ//2.60346 TONNES)//STANDING THUS SLIGHTLY ADVANCES TO 43.4304 TONNES./
E.F.P. ISSUANCE/FOR OPENING OCT GOLD CONTRACT
THE CME RELEASED THE DATA FOR EFP ISSUANCE AND IT TOTALED A HUGE SIZED 4965 CONTRACTS:
The NEW COMEX OI FOR THE GOLD COMPLEX RESTS AT 400,499 SURPASSING THE PREVIOUS ALL TIME LOW OF 326,052 SET JUNE 3 AND RISING FROM OUR PREVIOUS RECORD LOW//MAY 28.2026 WE HAVE THUS RECORD LOW COMEX OI WITH A HIGH PRICE OF GOLD
SILVER ALSO HAS AN ULTRA SMALL SIZED AND EXTREMELY LOW COMEX OI OF 112,392 CONTRACTS// STILL ABOVE FROM PREVIOUS ALL TIME LOWS SET DURING THE MONTH OF APRIL AND MAY FIRST.
IN ESSENCE WE HAVE A STRONG SIZED GAIN IN TOTAL CONTRACTS IN GOLD ON THE TWO EXCHANGES OF 5,485 CONTRACTS WITH 520 CONTRACTS INCREASED AT THE COMEX// AND A HUGE SIZED 4965 EXCHANGE FOR PHYSICAL OI CONTRACT ISSUANCE WHICH NAVIGATED OVER TO LONDON.
THUS TOTAL OI GAIN ON THE TWO EXCHANGES OF 5,485 CONTRACTS.. WE HAD THE FOLLOWING TAS CONTRACTS INITIATED (ISSUED): A FAIR SIZED AND CRIMINAL 4965 CONTRACTS AND THESE ISSUANCES ARE GENERALLY USED TO INITIATE A RAID WHEN CALLED UPON .
GOLD PRICE LOSS BY $19.65
CALCULATIONS ON GAIN/LOSS ON OUR TWO EXCHANGES
WE HAD A HUGE SIZED ISSUANCE IN EXCHANGE FOR PHYSICALSCONTRACT (4965) ACCOMPANYING THE SMALL GAIN IN COMEX OI OF 520 CONTRACTS/TOTAL GAIN FOR OUR THE TWO EXCHANGES 5,485 CONTRACTS WITH THE GAIN IN PRICE.
WE HAVE 1) NOW REVERTED TO OUR FORMAT OF BANKER (FRBNY) GOING ON THE LONG SIDE AND HUGE NUMBERS OF NEWBIE SPECULATORS GOING TO THE SHORT SIDE LED BY THE NOSE BY OUR HIGH FREQUENCY TRADERS.. IT WAS OUR SHORT SPECULATORS THAT WILL BE BRUTALIZED WHEN OUR CENTRAL BANKS TENDER FOR PHYSICAL GOLD WITH THEIR NEWLY BOUGHT GOLD FROM THE SPECS THIS MORNING. THE SPECS WILL BE SCRAMBLING LOOKING FOR PHYSICAL GOLD TO DELIVER TO OUR LONG CENTRAL BANKS.
STANDING FOR THE LAST 10 MONTHS JANUARY TO OCT:
FINAL STANDING FOR GOLD, JANUARY CONTRACT AT 59.08 TONNES OF GOLD
FEBRUARY: INITIAL STANDING FOR GOLD: 157.878 TONNES!! WHICH INCLUDES ALL QUEUE JUMPING, THREE EXCHANGE FOR PHYSICAL TRANSFERS TO LONDON AND OUR SIX ISSUANCES EXCHANGE FOR RISK!!
MARCH: INITIAL STANDING AT 8.099 TONNES TO WHICH WE ADD OUR FINAL DAY: 0.2320 TONNES QUEUE JUMP AND THEN ADD +22.3818 TONNES EXCHANGE FOR RISK//NEW STANDING ADVANCES TO 67.6648 TONNES
APRIL: INITIAL STANDING 52.600 TONNES PLUS 27,800 OZ QUEUE JUMP (0.8648TONNES): NEW STANDING ADVANCES TO 70.286 TONNES PLUS OUR TWO EXCHANGE FOR RISK FOR 223,900 OZ OR 6.964 TONNES/NEW FINAL STANDING: 77.726 TONNES
MAY: INITIAL AMOUNT OF GOLD WILLING TO STAND; 12.24 TONNES TO WHICH WE ADD OUR NEXT QUEUE JUMP FOR 345 CONTRACTS/34,500 OZ// 1.073 TONNES/ THEN WE MUST ADD OUR EXCHANGE FOR RISK ISSUANCE: TOTAL EXCHANGE FOR RISK MAY// 5 OCCASIONS: 24.635 TONNES///NEW FINAL STANDING NOW ADVANCES TO 51.554 TONNES
JUNE: INITIAL AMOUNT OF GOLD WILLING TO STAND: 64.496 TONNES TO WHICH WE ADD OUR NEXT EXCHANGE FOR PHYSICAL TRANSFER JUMP OF 0.0186 TONNES//NEW STANDING 127.03 TONNES//FINAL
JULY: INITIAL AMOUNT OF GOLD WILLING TO STAND: 23.306 TONNES OF GOLD TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 0.0000 TONNES/ PLUS 0.0062 TONNES EX FOR RISK///NEW STANDING FOR GOLD REMAINS AT 40.824TONNES.
AUGUST INITIAL STANDING 48.687 TONNES TO WHICH WE ADD OUR FIRST 0.0715 TONNES EXCHANGE TO OUR 2ND EXCHANGE FOR RISK = 1.552 TONNES TO OUR 3RD EXCHANGE FOR RISK OF: 1.7045//TOTAL FOR EXCHANGE FOR RISK 3.3312 TONNES TO OUR 4TH EXCHANGE FOR RISK OF 200 CONTRACTS FOR 0.6220 TONNES/TO OUR 5TH EXCHANGE FOR RISK OF 0.0155 TONNES//TOTALL EXCHANGE FOR RISK: 3.9688 TONNES TO OUR NEXT QUEUE JUMP OF 0.1213 TONNES//STANDING ADVANCES TO 67.2441 TONNES
SEPT: INITIAL STANDING FOR GOLD: 8.756 TONNES FOLLOWED BY TODAY’S 0 OZ QUEUE JUMP (0.0000TONNES) TO WHICH WE ADD OUR SECOND 1000 CONTRACT EXCHANGE FOR RISK TO OUR FIRST: THUS// NEW EXCHANGE FOR RISK: 6.2208 TONNES// NEW STANDING REMAINS AT 19.2308 TONNES.
OCT: INITIAL STANDING FOR GOLD: 38.345 TONNES FOLLOWED BY TODAY’S 600 OZ QUEUE JUMP (0.01886 TONNES)// TO WHICH WE ADD OUR SECOND EXCHANGE FOR RISK OF ONE CONTRACT TO OUR FIRST EXCHANGE FOR RISK AT 836 CONTRACTS/ NEW TOTAL/83,700 OZ OR 2.60345 TONNES// //STANDING THUS ADVANCES TO 43.4304 TONNES//
3)SOME T.A.S. LIQUIDATION IN THE COMEX SESSION/,MONDAY// A HUGE GOVT LIQUIDATION // WITH A STRONG LOSS OF EQUITY SHARES/OCT 19 HAVING 1)A COMEX GOLD PRICE LOSS OF $19.95 AND WE HAD 2) SPEC PILING HUGELY ON THE SHORT SIDE // /// +3. EASTERN CENTRAL BANKERS ALSO PILING INTO THE LONG SIDE. WE HAD A STRONG GAIN OF 6,884 CONTRACTS ON OUR TWO EXCHANGES AND AS WELL A STRONG AMOUNT OF GOLD WILL STILL STAND FOR DELIVERY IN OCT (43.4304 TONNES). THE SHORT SPECS CONTINUED TO PILE INTO THE SHORT SIDE AND WERE SLAUGHTERED.//, CENTRAL BANKERS THE LONG SIDE AND THEY THEN TENDERED FOR PHYSICAL WITH THEIR PURCHASES OF CONTRACTS../ ALSO, 3)STICKY GOLD’S LONGS WERE REWARDED MONDAY EVENING AS THEY EXERCISED EFP’S FROM LONDON TO TAKE DELIVERY OF BADLY NEEDED PHYSICAL
4)A FAIR SIZED COMEX OI GAIN 5) V) A HUGE SIZED ISSUANCE OF EXCHANGE FOR PHYSICAL GOLD(4965) AND 6. A FAIR T.A.S. ISSUANCE (1014) FOR RAID PURPOSES.!!!
ACCUMULATION OF EFP’S GOLD AT J.P. MORGAN’S HOUSE OF BRIBES: (EXCHANGE FOR PHYSICAL) FOR THE MONTH OF OCT :
TOTAL EFP CONTRACTS ISSUED:25,297 CONTRACTS OR 2,529,700 OZOR 78.684 TONNES IN 14 TRADING DAY(S) AND THUS AVERAGING:1806 EFP CONTRACTS PER TRADING DAY
TO GIVE YOU AN IDEA AS TO THE SIZE OF THESE EFP TRANSFERS : THIS MONTH IN 14 TRADING DAY(S) IN TONNES: 63.24 TONNES
TOTAL ANNUAL GOLD PRODUCTION, 2025, THROUGHOUT THE WORLD EX CHINA EX RUSSIA: 3555 TONNES
THUS EFP TRANSFERS REPRESENTS 78.684 TONNES DIVIDED BY 3550 x 100% TONNES= 2.225% OF GLOBAL ANNUAL PRODUCTION
SEPT 142.12 TONNES FINAL ISSUANCE ( LOW ISSUANCE)_
OCT: 141.13 TONNES FINAL ISSUANCE (LOW ISSUANCE)
NOV: 312.46 TONNES FINAL ISSUANCE//NEW RECORD!! (INCREASING DRAMATICALLY)//SIGN OF REAL STRESS//SURPASSING THE MARCH 2021 RECORD OF 276.50 TONNES OF EFP
DEC. 175.62 TONNES//FINAL ISSUANCE//
TOTALS: 2,578.08 TONNES/2021
JAN:2023 247.25 TONNES //FINAL
FEB: 196.04 TONNES//FINAL
MARCH/2022: 409.30 TONNES //FINAL( THIS IS NOW A RECORD EFP ISSUANCE FOR MARCH AND FOR ANY MONTH.
APRIL: 169.55 TONNES (FINAL VERY LOW ISSUANCE MONTH)
MAY: 247.44 TONNES FINAL//
JUNE: 238.13 TONNES FINAL
JULY: 378.43 TONNES FINAL/SECOND HIGHEST ON RECORD
AUGUST: 180.81 TONNES FINAL
SEPT. 193.16 TONNES FINAL
OCT: 177.57 TONNES FINAL ( MUCH SMALLER THAN LAST MONTH)
NOV. 223.98 TONNES//FINAL ( MUCH LARGER THAN PREVIOUS MONTHS//comex running out of physical)
DEC: 185.59 tonnes // FINAL
TOTAL: 2,847,25 TONNES/2022
JAN 2024: 228.49 TONNES FINAL//HUGE AMOUNT OF EFP’S ISSUED THIS MONTH!!
FEB: 151.61 TONNES/FINAL
MARCH: 280.09 TONNES/INITIAL (ANOTHER STRONG MONTH FOR EFP ISSUANCE)
APRIL: 197.42 TONNES
MAY: 236.67 TONNES (A VERY STRONG ISSUANCE FOR THIS MONTH)
JUNE: 172.667 TONNES (WEAKER ISSUANCE THIS MONTH)
JULY: 151.69 TONNES (WEAKER THAN LAST MONTH)
AUGUST: 195.28 TONNES (A STRONGER MONTH)//FINAL
SEPT: 254.709 TONNES (WILL BE LARGER THAN LAST MONTH AND A STRONG MONTH)
OCT. 248.09 TONNES. LIKE SILVER, THIS MONTH IS GOING TO BE A STRONG E.F.P. ISSUANCE.
NOV. 239.16 TONNES//WILL BE STRONG THIS MONTH,
DEC. 213.704 TONNES. A STRONG MONTH//
TOTAL FOR YEAR 2023: 2,569.57 TONNES
2025: AND NOW 2026
JAN. 2025: 257.919 TONNES (ISSUANCE WILL BE PRETTY GOOD THIS MONTH BUT MUCH LOWER THAN LAST MONTH)
FEB: 207.21 TONNES//EX FOR PHYSICAL ISSUANCE (WILL BE A FAIR SIZED ISSUANCE THIS MONTH)
MARCH 130.84 TONNES//QUITE SMALL THIS MONTH.
APRIL; 208.57 TONNES. STRONG THIS MONTH
MAY: 113.499 TONNES OF GOLD EFP ISSUANCE//QUITE SMALL THIS MONTH
JUNE: 97.79 TONNES OF GOLD EFP ISSUANCE/EXTREMELY SMALL
JULY : 150.877 TONNES// QUITE SMALL
AUGUST: 175.86 TONNES A LOT LARGER THIS MONTH.
SEPT. 116.13 TONNES VERY SMALL
OCT. 252.72 TONNES//CERTAINLY MUCH LARGER THIS MONTH/VERY STRONG
NOV: 124.74 TONNES
DEC: 190.04 TONNES//GOOD SIZED THIS MONTH FINAL.
TOTAL EXCHANGE FOR PHYSICAL ISSUED FOR YEAR 2025: 2,026.20 TONNES (LOWER THAN LAST YR 2,569.00 TONNES
YEAR 2026:
JANUARY: 209.08 TONNES ( (WILL BE A STRONG MONTH FOR EXCHANGE FOR PHYSICAL)
FEB. 176.35 TONNES (WHICH IS A FAIR ISSUANCE)
MARCH: 214.67 TONNES//WILL BE STRONG ISSUANCE THIS MONTH
APRIL; 88.00 TONNES// WILL BE VERY SMALL THIS MONTH
MAY 118.430 TONNES
JUNE: 142.053 TONNES
JULY: 163.82 TONNES
AUGUST: 151.107 TONNES
SEPT: 99.458 TONNES
OCT: 78.684 TONNES
XXXXXXXXXXXXXXXXXXXXXXXXXX
ASIA TRADING CLOSING OCT 20
SHANGHAI CLOSED UP 4.45 PTS OR 0.12%
HANG SENG CLOSED DOWN 315.09 PTS OR 1.32%
Nikkei CLOSED DOWN 752.70 PTS OR 1.166%
//Australia’s all ordinaries CLOSED UP 0.28%
//Chinese yuan (ONSHORE) CLOSED UP AT 6.6781
/ OFFSHORE CLOSED UP AT 6.6772 Oil UP TO 108.00 dollars per barrel for WTI and BRENT UP TO 111.18 Stocks in Europe OPENED ALL RED
ONSHORE USA/ YUAN// WITH YUAN TRADING 6.6781 OFFSHORE YUAN TRADING UP TO 6.6772 ONSHORE YUAN TRADING BELOW LEVEL // OFF SHORE AND UP ON THE DOLLAR)// / AND THUS STRONGER/OFF SHORE YUAN TRADING UP AGAINST US DOLLAR/ AND THUS STRONGER
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
ONSHORE YUAN: CLOSED UP TO 6.6874
SPREADERS:
HERE IS A BRIEF SYNOPSIS OF HOW THE CROOKS FLEECE UNSUSPECTING LONGS
YOU WILL ALSO NOTICE THAT THE COMEX OPEN INTEREST STARTS TO RISE BUT SO IS THE OPEN INTEREST OF SPREADERS. THE OPEN INTEREST IN WILL CONTINUE TO RISE UNTIL ONE WEEK BEFORE FIRST DAY NOTICE OF AN UPCOMING ACTIVE DELIVERY MONTH (OCT), AND THAT IS WHEN THE CROOKS SELL THEIR SPREAD POSITIONS BUT NOT AT THE SAME TIME OF THE DAY. THEY WILL USE THE SELL SIDE OF THE EQUATION TO CREATE THE CASCADE (ALONG WITH THEIR COLLUSIVE FRIENDS) AND THEN COVER ON THE BUY SIDE OF THE SPREAD SITUATION AT THE END OF THE DAY. THEY DO THIS TO AVOID POSITION LIMITS
WHAT IS ALARMING TO ME, ACCORDING TO OUR LONDON EXPERT ANDREW MAGUIRE IS THAT THESE EFP’S ARE BEING TRANSFERRED TO WHAT ARE CALLED SERIAL FORWARD CONTRACT OBLIGATIONS AND THESE CONTRACTS ARE LESS THAN 14 DAYS. ANYTHING GREATER THAN 14 DAYS, THESE MUST BE RECORDED AND SENT TO THE COMPTROLLER, GREAT BRITAIN TO MONITOR RISK TO THE BANKING SYSTEM. IF THIS IS INDEED TRUE, THEN THIS IS A MASSIVE CONSPIRACY TO DEFRAUD AS WE NOW WITNESS A MONSTROUS TOTAL EFP’S ISSUANCE AS IT HEADS INTO THE STRATOSPHERE.
The crooks also use the spread in the TAS account (trade at settlement). They buy the spot TAS (e.g. June) and sell the future TAS two months out (e.g. August). Then they unload the front month (i.e. unload the buy side first so the price of gold/silver falls. This occurs in the middle of the front delivery month cycle. They unload the sell side of the equation, two months down the road. The crooks violate position limits as the OCC refuse to hear our complaints.
First, here is an outline of what will be discussed tonight:
SILVER:
1.TODAY WE HAD THE OPEN INTEREST AT THE COMEX IN SILVER ROSE BY A FAIR 341 CONTRACTS TO AN OI OF 112,392
EFP ISSUANCE 0 CONTRACTS
OUR CUSTOMARY MIGRATION OF COMEX LONGS CONTINUE TO MORPH INTO LONDON FORWARDS AS OUR BANKERS USED THEIR EMERGENCY PROCEDURE TO ISSUE:
DEC 0 CONTRACTS and 0 ALL OTHER MONTHS: ZERO. TOTAL EFP ISSUANCE: 0 CONTRACTS. EFP’S GIVE OUR COMEX LONGS A FIAT BONUS PLUS A DELIVERABLE PRODUCT OVER IN LONDON. IF WE TAKE THE COMEX OI GAIN OF 341 CONTRACTSAND ADD TO THE 0 E.FP. ISSUED
WE OBTAIN A FAIR GAIN OF 341 OI OPEN INTEREST CONTRACTS FROM OUR TWO EXCHANGES DESPITE OUR LOSS OF $0.04
THUS IN OUNCES, THE GAIN ON THE TWO EXCHANGES TOTAL 1.705 MILLION PAPER OZ
STANDING OCT AT 19.895 MILLION OZ
SILVER PRICE LOSS OF $0.04
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
GOLD
LET US BEGIN:
THE TOTAL COMEX GOLD OPEN INTEREST ROSE BY A SMALL 520 CONTRACTS TO 400,499 STILL WELL ABOVE ITS NEW LOW OF 326,052 OI SET JUNE 3/2026, CLOSE TO THE PREVIOUS ALL TIME LOW OF 345,705 SET (MAY 28/2026) AND CLOSE TO THE PREVIOUS ALL TIME LOW IN OI OF 353,490 SET MAY 27.. PREVIOUS TO THAT THE ALL TIME LOW IN OI WAS 390,000 SET IN THE YEAR 2001 WHEN GOLD WAS TRADING $260.00. THE CME SHOULD BE PROUD OF THEMSELVES AS MANY HAVE ABANDONED THIS CROOKED ARENA!!THUS OUR NEW ALL TIME LOW OF COMEX OI HAS NOW BEEN SET AT 326,052 //JUNE 3 2026 WITH GOLD AT AN EXTREMELY HIGH $4,450.00 WHICH MAKES ABSOLUTELY NO SENSE!!!
WE HAD SOME T.A.S. LIQUIDATION DURING MONDAY’S COMEX TRADING HOURS// . IT SEEMS THAT MANY OF THE SPECULATORS THAT HAVE NOW CONTINUED AGAIN TO BE ON THE SHORT SIDE WITH BANKERS ON THE LONG SIDE AND THESE GUYS WERE AGAIN OBLITERATED YESTERDAY WHEN THE LONGS TENDERED FOR DELIVERY:
CENTRAL BANKS TENDERED THEIR NEW LONG CONTRACTS AT THE END OF THE DAY FOR PHYSICAL GOLD. YOU CAN VISUALIZE THIS WITH THE STRONG AMOUNT OF GOLD STANDING AT THE COMEX FOR THIS OCTOBER CONTRACT MONTH!!
WE HAD A FAIR SIZED GAIN ON OUR TWO EXCHANGES (5,485 CONTRACTS) OCCURRED DESPITE OUR LOSS IN PRICE IN GOLD (DOWN $19.65) WITH MONDAY’S TRADING!
WE THUS HAD A FAIR GAIN IN OI ON BOTH OF OUR EXCHANGES (5,485 CONTRACTS), DESPITE OUR LOSS IN PRICE, AS WE WERE INFORMED OF A HUGE SIZED CONTRACT EXCHANGE FOR PHYSICAL ISSUANCE EQUATING TO 4,965 CONTRACTS.
THEN WE WERE NOTIFIED TODAY OF A ONE CONTRACT FOR RISK ISSUANCE IN GOLD CONTRACTS FOR 100 OZ OR 0.00311 TONNES OF GOLD. TOTAL THUS SO FAR THIS MONTH: 837 CONTRACTS//83,700 OZ OR 2.60342 TONNES (2 OCCASIONS)
MONTH OF MAY RECORD ISSUANCE OF EXCHANGE FOR RISK: THE HIGHEST EVER ISSUANCE!!
MAY 22 RECORDS THE HIGHEST EVER EXCHANGE FOR RISK AT 12.4416 TONNES. WE HAD OUR FIRST ISSUANCE FOR EXCHANGE FOR RISK IN THE MONTH OF MAY ON MAY 7, THEN OUR 2ND ISSUANCE FOR OUR MAY GOLD MONTH ON MAY 12. THE THIRD ON MAY 18 , THEN MAY 21 OUR 4TH ISSUANCE AND THEN FINALLY FRIDAY, OUR 5TH ISSUANCE. THIS GOLD WILL BE ADDED TO OUR NORMAL MAY DELIVERIES TO GIVE US OUR FINAL AMOUNT OF GOLD WILLING TO STAND AT THE COMEX..
HISTORY OF EXCHANGE FOR RISK ISSUANCE THIS YEAR: FEBRUARY THROUGH JULY AND AUGUST
FEBRUARY:
DURING THE MIDDLE OF THE FEBRUARY CONTRACT MONTH, WE HAD TWO IDENTICAL MONSTER 3,000 CONTRACT ISSUED FOR THE SAME 9.33 TONNES OF GOLD, AND THESE WERE THE HIGHEST EVER IN TONNAGE EVER ISSUED BY THE COMEX. ALTOGETHER THE TOTAL ISSUANCE FOR FEB TOTALLED SIX.(31.251 TONNES).
MARCH:
THURSDAY MARCH 17 WE RECEIVED ITS INITIAL 2000 CONTRACT EXCHANGE FOR RISK ISSUANCE FOR 6.22 TONNES. LAST FRIDAY: 0 ISSUANCE OF EXCHANGE FOR RISK. BUT ON MONDAY MARCH 23 WE RECEIVED NOTICE OF OUR SECOND EXCHANGE FOR RISK ISSUANCE FOR 2,200 CONTRACTS (220,000 OZ OR 6.843 TONNES) AND NOW FRIDAY WITH A MONSTER 2996 CONTRACTS FOR 9.3138 TONNES. THESE THREE ISSUANCES WILL NOW BE ADDED TO THE REGULAR AMOUNT OF GOLD STANDING, I.E. 22.3818 TONNES TO OUR NORMAL GOLD STANDING TO GIVE US WHAT WILL STAND FOR PHYSICAL GOLD FOR MARCH!
APRIL;: 2 EXCHANGE FOR RISK SO FAR, I.E. 2239 CONTRACTS FOR 223,900 OZ OR 6.964 TONNES AND THIS TOTAL TONNES WILL BE ADDED TO OUR NORMAL DELIVERY TO GIVE US WHAT WILL STAND IN APRIL
MAY: FIVE ISSUANCES SO FAR FOR 7920 CONTRACTS OR 792,000 OZ OR 24.635 TONNES.
JUNE: 0 IN GOLD. THUS FOR THE ENTIRE MONTH IN GOLD ZERO NOTICES WERE FILED.
JULY: 2 FOR 200 OZ OR 0.00622 TONNES
AUGUST: 1276 CONTRACTS FOR 127,600 OZ OR 3.9688 TONNES (5 OCCASIONS THIS MONTH)
SEPT: SO FAR: 2000 CONTRACTS FOR 200,000 OZ OR 6.2208 TONNESS (TWO OCCASIONS)
OCT: 2 SO FAR//837 CONTRACTS FOR 83700 OZ OR 2.60342 TONNES/ONE OCCASION
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
A LITTLE HISTORY OF EXCHANGE FOR RISK DECEMBER THROUGH TO OCT:
IN DECEMBER WE HAVE RECORDED 5 ISSUANCES OF EXCHANGE FOR RISK/4 FOR DEC AND THE LAST ONE ON DEC 31 FOR JANUARY. WE NOW HAVE 3 CHOICES FOR THE RECIPIENT OF THIS ISSUANCE AND IT MUST BE A CENTRAL BANK. YOU WILL RECALL THAT THE BUYER ASSUMES THE RISK OF THAT DELIVERY. (THUS TOTAL EXCHANGE FOR RISK FOR THE MONTH OF DECEMBER IS 6.56 TONNES/4 OCCASIONS.
MONTH OF JANUARY/EXCHANGE FOR RISK
IN JANUARY THEY HAVE 6 TOTAL ISSUANCE : 3.446 TONNES EARLY, THEN JAN 9 ISSUANCE OF 9,331 TONNES AND THEN JAN 16: 0.1996 TONNES JAN 26: 1.499 TONNES, JAN 27: 3.160 AND FINALLY JAN 29: 4.659 TONNES TONNES//TOTAL EXCHANGE FOR RISK JANUARY 22.315 TONNES WHICH WAS ADDED TO OUR NORMAL DELVERIES.
AND FEBRUARY:
FEB EXCHANGE FOR RISK: NOW 6 ISSUANCES: 10,080 CONTRACTS FOR 1,008,000 OZ OR 31.251 TONNES!
HERE ARE THE CHOICES FOR THE RECIPIENT OF THOSE ISSUANCES:
1 THE CENTRAL BANK OF ENGLAND. BUT THEY RECEIVED CLEARANCE THAT THEIR GOLD IS BACK SO IT IS NOT LIKELY THAT THEY WOULD LIKE TO ADD TO THEIR RESERVES.
2. THE CENTRAL BANK OF THE USA: THE FED. LOGICAL CHOICE AS THEY CLAMOUR TRYING TO REDUCE THEIR 141+ TONNES OF SHORTAGE. HOWEVER THEY SEEM NOT TO BE IN A HURRY TO COVER THEIR HUGE SHORTFALL
3. THE CENTRAL BANK OF CHINA AS THEY BATTLE WITS WITH THE USA.
TOTAL EXCHANGE FOR RISK FOR DECEMBER IS 6.56 TONNES AND THIS WAS ADDED TO OUR NORMAL DELIVERY TOTALS..
THE JANUARY ISSUANCE OF 17.656 TONNES WAS ADDED TO OUR DAILY DELIVERY TOTALS!!
FEBRUARY ISSUANCES 6 FOR; 31.251 TONNES !! AND THIS WAS ADDED TO OUR DELIVERY TOTALS FOR THIS MONTH.
MARCH: CME ANNOUNCES ITS FIRST EXCHANGE FOR RISK FOR 2000 CONTRACTS FOR 200,000 OZ OR 6.22 TONNES OF GOLD DURING THE FIRST WEEK OF MARCH, AND THEN MONDAY, MARCH 22, WE RECEIVED ITS SECOND NOTICE ISSUANCE OF 2200 CONTRACTS OR 220000 OZ (6.843 TONNES). THEN FINALLY WE RECEIVED NOTICE OF OUR THIRD EXCHANGE FOR RISK OF 2996 CONTRACTS OR 9.3188 TONNES. TOGETHER ALL 3 ISSUANCES TOTAL 22.3818 TONNES WHICH WILL BE ADDED TO OUR NORMAL DELIVERY SCHEDULE.
APRIL: 2 EXCHANGE FOR RISK SO FAR FOR 223,900 OZ OR 6.964 TONNES. AND THIS TOTAL WILL BE ADDED TO OUR NORMAL DELIVERY TO GIVE US WHAT WILL STAND FOR APRIL!!
MAY: FIVE ISSUANCES SO FAR FOR 7920 CONTRACTS, 792,000 OZ OR 24.635 TONNES OF GOLD. THIS TOTAL WILL BE ADDED TO OUR NORMAL DELIVERIES IN MAY TO GIVE US WHAT WILL STAND IN MAY.
JUNE: ZERO
JULY 2 FOR 200 OZ OR 0.00622 TONNES. I DOUBT VERY MUCH THAT THIS IS A CENTRAL BANK
AUGUST: 1276 CONTRACTS FOR 127,600 OZ OR 3.9688 TONNES//5 OCCASIONS
SEPT: SO FAR: 2000 CONTRACTS FOR 200,000 OZ OR 6.2208 TONNES/TWO OCCASIONS
OCT: 2 SO FAR// 837 CONTRACTS FOR 83,700 OZ OR 2.60342 TONNES
DETAILS ON OUR NEW OCT COMEX CONTRACT MONTH//
IN TOTAL WE HAD A FAIR GAIN ON OUR TWO EXCHANGES OF 5,485 CONTRACTS DESPITE OUR LOSS IN PRICE(DOWN $19.65). HOWEVER, OUR FRIENDLY PHYSICAL LONDON BOYS HAD ANOTHER FIELD DAY AGAIN THROUGHOUT THIS WEEK AS THEY WERE READY FOR THE FRBNY.S CONTINUED ORCHESTRATED ATTACKS VERY EARLY IN THE COMEX SESSIONS AS THEY TRIED TO ABSORB EVERYTHING IN SIGHT FROM THEIR DAILY ATTACKS. LONDONERS EXERCISED THEIR BOUGHT CONTRACTS FOR PHYSICAL GOLD VIA THE EXCHANGE FOR PHYSICAL ROUTE AND THANKED THE FRBNY AND OUR SHORT SPECULATORS FOR THEIR THOUGHTFULNESS.
LONDON ANNOUNCED EARLY IN THE YEAR (AND SCARCITY CONTINUES TO THIS DAY) THAT THEY WERE OUT OF GOLD. WRONGLY IT WAS ATTRIBUTED TO THEIR SHIPPING PHYSICAL GOLD TO COMEX FOR STORAGE DUE TO TRUMP’S INITIATION OF TARIFFS. THE TRUTH OF THE MATTER IS THAT THIS GOLD LEFT LONDON TO OTHER CENTRAL BANKS, AND COMEX BANKS HAVE BEEN PAPERING THEIR LOSSES (DERIVATIVE) WITH KILOBAR ENTRIES. BOTH COMEX AND LBMA ARE WITNESSING MASSIVE AMOUNTS OF GOLD LEAVING THEIR VAULTS.
THE LIQUIDATION OF T.A.S. CONTRACTS THROUGHOUT THE MONTHS OF JUNE THROUGH OCT. CONTINUES TO DISTORT OPEN INTEREST NUMBERS GREATLY ALTHOUGH THE T.A.S. ISSUANCES IN GOLD HAVE GENERALLY BEEN ON THE LOW SIDE COMPARED TO SILVER WHICH HAVE BEEN HUGE. TODAY’S NUMBER HOWEVER IS A FAIR SIZED T.A.S ISSUANCE CONTRACTS .THE CME NOTIFIES US THAT THEY HAVE ISSUED 1014 T.A.S CONTRACTS. THESE ARE GENERALLY USED FOR RAID PURPOSES TO STOP GOLD’S RISE AND TO TEMPER HUGE LOSSES IN OTC DERIVATIVE BETS.
IT SURE LOOKS LIKE THE BIS HAS SOMEHOW LOOKED THE OTHER WAY WITH ITS GOLD SWAPS WITH THE FRBNY AS THIS ENTITY FOR THE FED REFUSES THE BIS MARCHING ORDERS TO COVER AND THAT MAY EXPLAIN THE STRONG NUMBER OF T.A.S. ISSUANCES IN DECEMBER , JANUARY AND THROUGHOUT FEBRUARY TO GO ALONG WITH OUR HUGE NUMBER OF EXCHANGE FOR RISK ISSUED DURING THESE MONTHS INCLUDING FEBRUARY’S 6 EXCHANGE FOR RISK WHICH ALSO INCLUDED TWO MONSTER 9.3312 TONNE ISSUANCE (FEB 10 AND FEB 12). TOTAL EXCHANGE FOR RISK/FEB EQUALS 31.251 TONNES!! AND MARCH’S THREE ISSUANCES FOR 22.3818 TONNES! OTHER CENTRAL BANKS ARE PAYING ATTENTION AS THEY TAKE DELIVERY OF HUGE AMOUNTS OF PHYSICAL GOLD. APRIL HAD 2 EXCHANGE FOR RISK ISSUANCES FOR 6.694 TONNES. AND MAY WITH ITS 5TH ISSUANCE FOR 12.4436 TONNES///TOTAL EXCHANGE FOR RISK FOR MAY: 24.635 TONNES ISSUED MAY 6 ,MAY 12, MAY 18 MAY 21 AND NOW MAY 22..
THEN IT SLOWS DOWN!
JUNE: ZERO FOR THE MONTH
JULY: 2 SO FAR FOR 200 IZ IR 0.00622 TONNES
AUGUST: 1276 CONTRACTS FOR 127,600 OZ OR 3.9688 TONNES
SEPT: 2000 CONTRACTS SO FAR FOR 200,000 OZ OR 6.2208 TONNES (TWO OCCASIONS)
OCT: 2 SO FAR//837 CONTRACTS FOR 83700 OZ OR 2.60342 TONNES (TWO OCCASIONS)
WE MUST ALSO REMEMBER THAT THE FRBNY IS SHORT 141+ TONNES OF GOLD, THIS COMMENCED ON JAN 2 2023 AS THEY REFUSE TO COVER DESPITE THE BIS’S PLEA TO DO SO.
HERE IS A SUMMARY OF GOLD STANDING FOR DELIVERY ON OUR LAST 16 MONTHS:
1.APRIL AT 209 TONNES
2. AND THIS CONTINUED INTO MAY WITH FINAL STANDING AT 90.23 TONNES.
3. JUNE WHICH IS A HUGE DELIVERY MONTH , FINAL STANDING WAS RECORDED AT A STRONG 93.085 TONNES. //(TOTAL NET QUEUE JUMPING FOR THE JUNE MONTH: 31.027 TONNES.)
4. IN JULY WE HAD HUGE DELIVERY NOTICES ESPECIALLY FOR A NON ACTIVE DELIVERY MONTH WITH INITIAL STANDING AT 17.947 TONNES PLUS MANY QUEUE JUMPS + 3.75 TONNES EX FOR RISK = 41.106 TONNES OF GOLD // FINAL TOTAL TONNES STANDING JULY: 41.106 TONNES
5. FOR THE MONTH OF AUGUST 2025
INITIAL AMOUNT OF GOLD STANDING FOR AUGUST: 60.547 TONNES PLUS THE MONTHS HUGE QUEUE JUMPS OF 47.2312 TONNES +44.696 TONNES EX FOR RISK (7 ISSUANCES) //NEW STANDING 152.208 TONNES WHICH IS MONSTROUS!!!
6. FINAL AMOUNT OF GOLD STANDING FOR SEPT; INITIAL STANDING; 2,602 CONTRACTS OR 260,200 OZ FOR 8.093 TONNES OF GOLD FOLLOWED BY TODAY’S 0.4883 TONNES QUEUE JUMP TO GO ALONG WITH TODAY’S 1.244 TONNES OF EXCHANGE FOR RISK ISSUANCE TODAY AND // TOTAL EXCHANGE FOR RISK ISSUANCE SEPT: 22.923 TONNES//NEW TOTALS STANDING ADVANCES TO 48.801 TONNES OF GOLD!!!
7. OCTOBER:
OCTOBER: INITIAL STANDING FOR GOLD: 90.164 TONNES TO WHICH WE ADD OUR LATEST OCT 30 QUEUE JUMP OF 0.00311 TONNES WHICH FOLLOWS OCT 29 QUEUE JUMP OF .4096 WHICH FOLLOWS; OCT 28 QUEUE JUMP OF .5069 TONNES WHICH FOLLOWS OCT 27 OF 0.3048 TONNES WHICH FOLLOWS: OCT 24 OF 0.8615 TONNES, FOLLOWING OCT 23 QUEUE JUMP OF 1.695 TONNES OCT 22 JUMP OF 8.622 TONNES WHICH FOLLOWS OCT 21: 3.8600 TONNES TO OCT 20 QUEUE JUMP OF 7.695 TONNE
SUMMARY FOR OCTOBER STANDING: LAST 12 MONTHS
NOVEMBER WHERE INITIAL AMOUNT OF GOLD STANDING IS REGISTERED AT 15.651 TONNES OF GOLD FOLLOWED BY TODAY’S QUEUE JUMP OF 2 TONNES AND FOLLOWED BY ALL OTHER NOV QUEUE JUMPS OF 21.3775 TONNES TO WHICH WE ADD OUR TWO EXCHANGE FOR RISK ISSUANCE FOR 4.5596 TONNES.
/STANDING ADVANCES TO 43.9716 TONNES OF GOLD.
DECEMBER: INITIAL AMOUNT OF GOLD STANDING FOR DELIVERY IN THIS ACTIVE MONTH IS 83.813 TONNES FOLLOWED BY TODAY’S 0.05 TONNES QUEUE JUMP. THIS FOLLOWS ALL OTHER QUEUE JUMPING: 37.163 TONNES//NEW STANDING ADVANCES TO 115.390 TONNES TO WHICH WE ADD OUR FOUR EXCHANGE FOR RISK ISSUANCE OF 6.559 TONNES//NEW STANDING THUS INCREASES TO 121.977 TONNES
JANUARY: INITITAL STANDING: 13.785 TONNES TO WHICH WE ADD OUR QUEUE JUMP OF 0.000 TONNES WHICH FOLLOWS ALL OTHER QUEUE JUMPS OF 30.7117TONNES //NEW TOTAL QUEUE JUMPS 30.7117//NORMAL DELIVERY OF GOLD ADVANCES TO 36.8958 TONNES TO WHICH WE ADD OUR SIX EXCHANGE FOR RISK OF 22.315 TONNES//NEW STANDING ADVANCES TO 59.2108 TONNES.
FEBRUARY: . FEBRUARY: INITIAL STANDING: 93.566 TONNES TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 0.0248 TONNES WHICH MUST BE ADDED ALL OTHER QUEUE JUMPS OF 41.2087 TONNES QUEUE JUMP//TOTAL QUEUE JUMP FOR FEB::ADVANCES TO 41.233 TONNES///STANDING ADVANCES TO 126.628 TONNES TO WHICH WE ADD OUR SIX EXCHANGE FOR RISK OF 31.251 TONNES/NEW STANDING FINALIZES AT 157.879 TONNES, ITS HIGHEST STANDING RECORDED IN OVER 4 YEARS.
MARCH: INITIAL STANDING FOR GOLD: 8.099 TONNES TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 0.2320 TONNES AND THEN WE ADD OUR THREE EXCHANGE FOR RISK OF 22.3818 TONNES////NEW STANDING FOR GOLD ADVANCES TO: 67.6648TONNES WHICH IS ABSOLUTELY HUGE FOR A NON ACTIVE DELIVERY MONTH!!
APRIL 2026: INITIAL STANDING FOR GOLD: 52.20 TONNES FOLLOWED BY TODAY’S SMALL 500 OZ QUEUE JUMP/ TO WHICH WE ADD OUR TWO EXCHANGE FOR RISK ISSUANCES TOTALLING 223,900 OZ OR 6.964 TONNES//STANDING ADVANCES TO 77.726 TONNES WHICH IS ABSOLUTELY HUGE
MAY: INITIAL AMOUNT OF GOLD WILLING TO STAND: 12.24 TONNES OF GOLD TO WHICH WE ADD OUR NEXT HUGE QUEUE JUMP OF 34,500 OZ (1.073 TONNES) TO WHICH WE ADD OUR FIVE EXCHANGE FOR RISK ISSUANCE FOR 792,000 OZ OR 24.635 TONNES////NEW TOTALS STANDING FOR GOLD ADVANCES TO 51.554 TONNESS
JUNE: INITIAL AMOUNT OF GOLD WILLING TO STAND: 64.496 TONNES TO WHICH WE SUBTRACT AN EXCHANGE FOR PHYSICAL TRANSFER TO LONDON OF 0.0186 TONNES//NEW STANDING REDUCES TO 127.03 TONNES// TOTAL QUEUE JUMPING FOR THE MONTH FINALIZES AT 62.4217 TONNES OR AVERAGING 3.285 TONNES PER DAY IN JUNE.
JULY: INITIAL AMOUNT OF GOLD WILLING TO STAND: 749,300 OZ OR 23.306 TONNES OF GOLD TO WHICH WE ADD OUR NEXT QUEUE JUMP OF 0.000TONNES//NEW STANDING REMAINS AT 40.818TONNES PLUS 0.00622 TONNES EXHANGE FOR RISK// NEW TOTAL 40.824 TONNES . TOTAL QUEUE JUMPING SO FAR: 17.5802 TONNES OR 0.8790 TONNES ON EACH TRADING DAY LEAVING COMEX FOR EASTERN SHORES.
AUGUST INITIAL; INITIAL AMOUNT OF GOLD WILLING TO STANDS: 48.687 TONNES TO WHICH WE ADD OUR 5TH EXCHANGE FOR RISK OF 5 CONTRACTS FOR 500 OZ OR 0.0155 TONNES TO OUR 4TH EXCHANGE FOR RISK OF 220 CONTRACTS FOR 20,000 OZ OR 0.6220 TONNES TO OUR 3RD EXCHANGE FOR RISK AT 1.7045 TONNES TO OUR 2ND EXCHANGE FOR RISK AT 1.552 TONNES TO OUR FIRST: 0.0715 NEW TOTAL EXCHANGE FOR RISK = 3.9688 TONNES AND THEN ADD OUR NEXT QUEUE JUMP OF 39 CONTRACTS OR 3900 OZ (0.1213 TONNES)//STANDING, IN TOTAL, THUS ADVANCES HUGELY TO 67.2441 TONNES.
SEPT/2026. INITIAL STANDING : 8.756 TONNES//FOLLOWED BY TODAYS QUEUE JUMP OF 0 OZ OR 0.0000 TONNES TO WHICH WE ADD THIS TO OUR TWO EXCHANGE FOR RISK OF 2,000 CONTRACTS/200,000 OZ OR 6.2208 TONNES: /NEW STANDING ADVANCES TO 19.2316 TONNES
OCT: INITIAL AMOUNT OF GOLD STANDING: 38.345 TONNES! FOLLOWED BY OCT 5;S FIRST EXCHANGE FOR RISK CONTRACT AT 836 CONTRACTS AND THEN OCT 20’S ISSUANCE OF ONE CONTRACT FOR 100 OZ: NEW TOTAL: (83,700 OZ OR 2.60342 TONNES)// TO WHICH WE ADD OUR NEXT 6 CONTRACT QUEUE JUMP FOR 600 OZ OR 0.01806 TONNES//THUS WITH THESE TWO ADDITIONS, STANDING ADVANCES TO 43.4304 TONNES!!WE ARE NOW BACK TO BEING WELL ABOVE OUR INITIAL STANDING AFTER THE FIRST TWO TRADING DAYS OF OCTOBER HAVING EXCHANGE FOR PHYSICAL TRANSFERS TO LONDON
HERE ARE THE AMOUNTS THAT STOOD FOR DELIVERY IN THE 4 YEARS 2021-2024
DEC 2021: 112.217 TONNES
NOV. 8.074 TONNES
OCT. 57.707 TONNES
SEPT: 11.9160 TONNES
AUGUST: 80.489 TONNES
JULY 7.2814 TONNES
JUNE: 72.289 TONNES
MAY 5.77 TONNES
APRIL 95.331 TONNES
MARCH 30.205 TONNES
FEB ’21. 113.424 TONNES
JAN ’21: 6.500 TONNES.
TOTAL YEAR 2021 (JAN- DEC): 601.213 TONNES
YEAR 2022: STANDING FOR GOLD/COMEX
JANUARY 2022 17.79 TONNES
FEB 2022: 59.023 TONNES
MARCH: 36.678 TONNES
APRIL: 85.340 TONNES FINAL.
MAY: 20.11 TONNES FINAL
JUNE: 74.933 TONNES FINAL
JULY 29.987 TONNES FINAL
AUGUST:104.979 TONNES//FINAL
SEPT. 38.1158 TONNES
OCT: 77.390 TONNES/ FINAL
NOV 27.110 TONNES/FINAL
Dec. 64.000 tonnes
(TOTAL YEAR 656.076 TONNES)
2023:STANDING FOR GOLD/COMEX
JAN/2023: 20.559 tonnes
FEB 2023: 47.744 tonnes
MAR: 19.0637 TONNES
APRIL: 75.676 tonnes
MAY: 19.094 TONNES + 1.244 tonnes of exchange for risk = 20.338
JUNE: 64.354 TONNES
JULY: 10.2861 TONNES
AUGUST: 38.855 TONNES(INCLUDING .6842 EXCHANGE FOR RISK)
SEPT: 15.281 TONNES FINAL
OCT. 35.869 TONNES + 1.665 EXCHANGE FOR RISK =37.0355 tonnes
THE SPECS/HFT WERE SUCCESSFUL IN LOWERING GOLD’S PRICE ( IT FELL BY $19.65).
WE HAD SOME T.A.S. SPREADER LIQUIDATION MONDAY // COMEX SESSION// WITH OUR GAIN IN PRICE.
OTHER EASTERN CENTRAL BANKS TENDERED FOR PHYSICAL EVERY NIGHT WHICH ALSO EXPLAINS THE HUGE NUMBER OF TONNES OF GOLD THAT STOOD FOR GOLD DURING THESE PAST SEVERAL MONTHS
THE CROOKS COULD NOT STOP OTHER CENTRAL BANK LONGS, SEIZING THE MOMENT, THEY EXERCISED AGAIN FOR PHYSICAL IN A BIG WAY TENDERING FOR PHYSICAL MONDAY EVENING //TUESDAY MORNING AND THUS OUR HUGE NUMBER OF GOLD CONTRACTS STANDING FOR DELIVERY AT THE COMEX. CENTRAL BANKERS WAIT PATIENTLY FOR THE GOLD
ALL OF THIS WAS ACCOMPLISHED WITH OUR LOSS IN PRICE AT COMEX OF $19.65
WE HAD 1399 CONTRACTS REMOVED // PRELIMINARY NUMBERS TO FINAL COMEX NUMBERS.
NET GAIN ON THE TWO EXCHANGES: 5,485 CONTRACTS OR 548,500 OZ (17.06 TONNES)
Total monthly oz gold served (contracts) so far this month
13,079 notices 1,307,900 OZ
40.6811 TONNES
Total accumulative withdrawals of gold from the Dealers inventory this month
NIL oz
Total accumulative withdrawal of gold from the Customer inventory this month
dealer deposits: 0
xxxxxxxxxxxxxxxxxxx
DEPOSITS:CUSTOMER ACCT
ENTRIES: 1
1) Into Loomis 16,493.483 oz (513 kilobars)
xxxxxxxxxxxxxxxxxx
comex withdrawals
1 ENTRIES
i) Manfra: 257.208 oz
(8 kilobars)
total withdrawal: 257.208 oz
adjustments: 0
COMEX IS DRAINING GOLD
chaos inside the comex
THE FRONT MONTH OF OCT OI STANDS AT 54 CONTRACTS HAVING A LOSS OF 546 CONTRACTS.
MONDAY WE HAD A NORMAL DELIVERY OF 1,312,000 OZ ( 40.808 TONNES) OF GOLD STANDING FOR DELIVERY: TODAY: 1,312,600 OZ OR 40.827 TONNES FOR A GAIN OF 600 OZ (1.617 TONNES) OR 6 CONTRACTS UNDERWENT A SMALL QUEUE JUMP WHERE THESE BOYS WILL TRY THEIR LUCK BY TAKING DELIVERY ON THIS SIDE OF THE POND..
NOVEMBER LOST 9 CONTRACTS FALLING TO 3630
DECEMBER, THE LARGEST DELIVERY MONTH IN THE CALENDAR, ITS OI FALLS BY 2482 CONTRACTS DOWN TO 314,509.
.
We had 7 contracts filed for today representing 700 oz
Today, 0 notice(s) were issued from J.P.Morgan dealer and 0 notices issued from their client or customer account. The total of all issuance by all participants equate to 7 contract(s) of which 0 notices were stopped (received) by j.P. Morgan dealer and 0 notice(s) was (were) stopped (received) by J.P.Morgan//customer account
To calculate the INITIAL total number of gold ounces standing for OCT /2026. contract month, we take the total number of notices filed so far for the month (13,079) to which we add the difference between the open interest for the front month of OCT (54 CONTRACTS) minus the number of notices served upon today 7 x 100 oz per contract) equals 1,312,600 OZ OR(40.827 Tonnes of gold) to which we add our two exchange for risk in Oct totalling 837 contracts for 83,700 oz or 2.60346 tonnes. Thus Oct standing for gold advances to 43.4296 tonnes
THUS: INITIAL total number of gold ounces standing for OCT. /2026. contract month,we take the total number of notices filed so far for the month (13,079) to which we add the difference between the open interest for the front month of OCT(54) contracts minus the number of notices served upon today 7 x 100 oz per contract) equals 1,312,600 OZ OR(40.824 Tonnes of gold) plus our first exchange for risk totalling 837 contracts//83700 oz//2.60346 tonnes//standing ADVANCES to 43.4296 tonnes
new total of gold standing in OCT becomes 43.4296 TONNES//
TOTAL COMEX GOLD STANDING FOR OCT.: 43.4296 TONNES WHICH IS NOW VERY STRONG FOR THIS NON ACTIVE DELIVERY MONTH OF OCT./
MONDAY VOLUME: 151,034 poor
COMEX GOLD INVENTORIES/CLASSIFICATION
NEW PLEDGED GOLD:
241,794.285 oz NOW PLEDGED /HSBC 5.94 TONNES
204,937.290 OZ PLEDGED MANFRA 3.08 TONNES
83,657.582 PLEDGED JPMorgan no 1 1.690 tonnes
265,999.054, oz JPM No 2
1,152,376.639 oz pledged Brinks/
Manfra: 33,758.550 oz
Delaware: 193.721 oz
International Delaware:: 11,188.542 oz
total pledged gold: 1,746,271.131 oz 54.31 tonnes pledged gold lowers
total inventories in gold declining rapidly
total pledged gold: 1,746,271.131 tonnes oz 54.31 tonnes
TOTAL OF ALL GOLD ELIGIBLE AND REGISTERED GOLD 23,425,905.336 oz//
TOTAL REGISTERED GOLD 14,816,969.006 tonnes (460.86 tonnes)
TOTAL OF ALL ELIGIBLE GOLD 8,608,936.330 oz.
REGISTERED GOLD THAT CAN BE SERVED UPON 13,070,698 oz ((REG GOLD- PLEDGED GOLD)=
406.553 Tonnes //
total inventories in gold declining rapidly
SILVER COMEX
OCT DELIVERY MONTH
OCT 20
Silver
Ounces
Withdrawals from Dealers Inventory
NIL oz
Withdrawals from Customer Inventory
0 entries
Deposits to the Dealer Inventory
1 ENTRY
i) Into dealer CNT 1,120,804.400 oz
total deposit: 1,120,804.400 oz
Deposits to the Customer Inventory
ENTRIES: 2
i) Into CNT 49,823.380 oz ii) Into HSBC 412,404.150 oz
total deposit: 492,227.530 oz
No of oz served today (contracts)
231 CONTRACT(S) ( 1.155 MILLION OZ)
No of oz to be served (notices)
18 Contracts (0.090 MILLION oz)
Total monthly oz silver served (contracts)
3511 contracts 17.555 MILLIONoz
Total accumulative withdrawal of silver from the Dealers inventory this month
NIL oz
Total accumulative withdrawal of silver from the Customer inventory this month
DEPOSITS INTO DEALER ACCOUNTS
ENTRY:1
i) Into dealer CNT 1,120,804.400 oz
total deposit: 1,120,804.400 oz
DEPOSIT ENTRIES/CUSTOMER ACCOUNT
2 ENTRIES:
i) Into CNT 49,823.380 oz ii) Into HSBC 412,404.150 oz
total deposit: 492,227.530 oz
xxxxxxxxxxxxxxxxxxxxxxxxx
withdrawals:
0 entries
adjustments : 0
xxxxxxxxxxxxxx
TOTAL REGISTERED SILVER: 104.238 MILLION OZ//.TOTAL REG + ELIGIBLE. 336.485 Million oz
registered silver dropping in numbers
CALCULATIONS FOR THE NEW STANDING FOR SILVER FOR OCT
FRONT MONTH: SILVER OPEN INTEREST CONTRACTS: 249 FOR A LOSS OF 20 CONTRACTS . MONDAY WE HAD 17.655 MILLION OZ STAND: TODAY: 17.645 MILLION OZ FOR A LOSS OF 10,000 OZ (2 CONTRACTS). THUS A 2 CONTRACT EXCHANGE FOR PHYSICAL TRANSFER JUMP TO LONDON WHERE THEY WILL TAKE DELIVERY ON THAT SIDE OF THE POND.
.
NOVEMBER LOST 30 CONTRACTS UP TO AN OI OF 1883
DECEMBER LOST 72 CONTRACTS UP TO AN OI OF 84,752
TOTAL NUMBER OF NOTICES FILED FOR TODAY: 231 or 1,155,000 oz
CONFIRMED volume MONDAY; 28,247 // poor/
AND NOW OCT. DELIVERIES:
To calculate the number of silver ounces that will stand for delivery in OCT. we take the total number of notices filed for the month so far at 3511 X5,000 oz = 17.555 MILLION oz.
Then we take the difference between the front month of OCT. and the number of notices filed for today x 5000 to give us our standing
Thus the standings for silver for the OCT 2026 contract month: (3511 )Notices served so far) x 5000 oz + OI for the front month of OCT (249) minus number of notices served upon today ( 231 x 5000 oz) equals silver standing for the OCT .contract month equating to 17.645 MILLION OZ to which we add silver’s TWO exchange for risk for 450 contracts (2.25 million oz).. total standing REDUCES to 19.895 million oz//. ( a very strong delivery month)
We must also keep in mind that there is considerable silver standing in London coming from our longs
There are ONLY 104.238 million oz of registered silver
JPMorgan as a percentage of total silver: 125.510/336.485 million: 37.20%
The record level of silver open interest is 234,787 contracts set on April 21./2017 with the price on that day at $18.42.
The previous record was 224,540 contracts with the price at that time of $20.44.
BOTH GLD AND SLV ARE MASSIVE FRAUD
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
OCT 20//2026/WITH GOLD DOWN $41.05 /NO CHANGES IN GOLD AT THE GLD. //:/INVENTORY RESTS AT 1059.04 TONNES
OCT 19//2026/WITH GOLD DOWN $19.65 /HUGE CHANGES IN GOLD AT THE GLD:A DEPOSIT OF 5.13 TONNES OF 0.29 TONNES OF GOLD INTO THE GLD/. //:/INVENTORY RESTS AT 1059.04 TONNES
OCT 16//2026/WITH GOLD UP $60.50 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 0.29 TONNES OF GOLD FROM THE GLD/. //:/INVENTORY RESTS AT 1053.91 TONNES
OCT 15//2026/WITH GOLD UP $60.50 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 1.21 TONNES OF GOLD FROM THE GLD/. //:/INVENTORY RESTS AT 1054.20 TONNES
OCT 14//2026/WITH GOLD DOWN $66.25 /NO CHANGES IN GOLD AT THE GLD: //:/INVENTORY RESTS AT 1055.41 TONNES
OCT 13//2026/WITH GOLD DOWN $13.25 /HUGE CHANGES IN GOLD AT THE GLD: A DEPOSIT OF OF 2.281TONNES OF GOLD INTO THE THE GLD//: //:/INVENTORY RESTS AT 1055.411 TONNES
OCT 12//2026/WITH GOLD DOWN $24.20 /HUGE CHANGES IN GOLD AT THE GLD: A WITHDRAWAL OF 2TONNES OF GOLD OUT OF THE GLD//: //:/INVENTORY RESTS AT 1053.13 TONNES
OCT 9//2026/WITH GOLD UP $60.00 /HUGE CHANGES IN GOLD AT THE GLD: A WITHDRAWAL OF 4.562 TONNES OF GOLD OUT OF THE GLD//: //:/INVENTORY RESTS AT 1055.411 TONNES
OCT 8//2026/WITH GOLD UP $16.85 /HUGE CHANGES IN GOLD AT THE GLD: A DEPOSIT OF 3.703 TONNES OF GOLD INTO THE GLD//: //:/INVENTORY RESTS AT 1059.873 TONNES
OCT 7//2026/WITH GOLD DOWN $46.70 /NO CHANGES IN GOLD AT THE GLD:: //:/INVENTORY RESTS AT 1056.27 TONNES
OCT 6//2026/WITH GOLD UP $30.60 /HUGE CHANGES IN GOLD AT THE GLD:: A DEPOSIT OF 0.754 TONNES OF GOLD INTO THE GLD// //:/INVENTORY RESTS AT 1056.27 TONNES
OCT 5//2026/WITH GOLD DOWN $2.20 /HUGE CHANGES IN GOLD AT THE GLD:: A WITHDRAWAL OF 0.854 TONNES OF GOLD INTO THE GLD// //:/INVENTORY RESTS AT 1055.696 TONNES
OCT 2//2026/WITH GOLD DOWN $43.00 /HUGE CHANGES IN GOLD AT THE GLD:: A DEPOSIT OF 0.854 TONNES OF GOLD INTO THE GLD// //:/INVENTORY RESTS AT 1056.55 TONNES
OCT 1//2026/WITH GOLD UP $19.55 /HUGE CHANGES IN GOLD AT THE GLD:: A WITHDRAWAL OF 1.711 TONNES OF GOLD OUT OF THE GLD// //:/INVENTORY RESTS AT 1055.696 TONNES
SEPT 30//2026/WITH GOLD UP $7.80 /HUGE CHANGES IN GOLD AT THE GLD:: A DEPOSIT OF 2.847 TONNES OF GOLD INTO THE GLD// //:/INVENTORY RESTS AT 1057.407 TONNES
SEPT 29//2026/WITH GOLD UP $11.75 /NO CHANGES IN GOLD AT THE GLD //:/INVENTORY RESTS AT 1054.56 TONNES
SEPT 28//2026/WITH GOLD DOWN $150.20 /NO CHANGES IN GOLD AT THE GLD //:/INVENTORY RESTS AT 1054.56 TONNES
SEPT 25//2026/WITH GOLD DOWN $150.20 /NO CHANGES IN GOLD AT THE GLD //:/INVENTORY RESTS AT 1054.56 TONNES
SEPT 24//2026/WITH GOLD DOWN $18.70 /HUGE CHANGES IN GOLD AT THE GLD A DEPOSIT OF 1.43 TONNES OF GOLD INTO THE GLD://:/INVENTORY RESTS AT 1056.84 TONNES
SEPT 23//2026/WITH GOLD DOWN $58.00 /HUGE CHANGES IN GOLD AT THE GLD://:/INVENTORY RESTS AT 1055.41 TONNES
SEPT 22//2026/WITH GOLD DOWN $6.30 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 0.31 TONNES OF GOLD INTO THE GLD/:/INVENTORY RESTS AT 1055.41 TONNES
SEPT 21//2026/WITH GOLD DOWN $41.20 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 2.26 TONNES OF GOLD INTO THE GLD/:/INVENTORY RESTS AT 1055.10 TONNES
SEPT 18//2026/WITH GOLD UP $26.45 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 0.85 TONNES OF GOLD INTO THE GLD/:/INVENTORY RESTS AT 1052.84 TONNES
SEPT 17//2026/WITH GOLD UP $14.05 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 1.71 TONNES OF GOLD INOT THE GLD/:/INVENTORY RESTS AT 1051.99 TONNES
SEPT 16//2026/WITH GOLD UP $53.40 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 2.86 TONNES OF GOLD INOT THE GLD/:/INVENTORY RESTS AT 1050.28 TONNES
SEPT 15//2026/WITH GOLD DOWN $19.45 /NO CHANGES IN GOLD AT THE GLD://A WITHDRAWAL OF 0.353 TONNES OF GOLD FROM THE GLD/:/INVENTORY RESTS AT 1047.420 TONNES
SEPT 14//2026/WITH GOLD DOWN $54.50 /SMALL CHANGES IN GOLD AT THE GLD://A WITHDRAWAL OF 0.353 TONNES OF GOLD FROM THE GLD/:/INVENTORY RESTS AT 1047.420 TONNES
SEPT 11//2026/WITH GOLD UP $1.05 /SMALL CHANGES IN GOLD AT THE GLD://A WITHDRAWAL OF 0.353 TONNES OF GOLD FROM THE GLD/:/INVENTORY RESTS AT 1050.277 TONNES
/SEPT 10//2026/WITH GOLD UP $50.60 /NO CHANGES IN GOLD AT THE GLD://:/INVENTORY RESTS AT 1050.63 TONNES
SEPT 9//2026/WITH GOLD UP $20.40 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 1.43 TONNES OF GOLD OUT OF THE GLD/ ////:/INVENTORY RESTS AT 1050.63 TONNES
SEPT 8//2026/WITH GOLD DOWN $34.20 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 1.42 TONNES OF GOLD OUT OF THE GLD/ ////:/INVENTORY RESTS AT 1052.06 TONNES
SEPT 4//2026/WITH GOLD DOWN $63.50 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 3.14 TONNES OF GOLD OUT OF THE GLD/ ////:/INVENTORY RESTS AT 1053.48 TONNES
SEPT 3//2026/WITH GOLD UP $141.55 /HUGE CHANGES IN GOLD AT THE GLD:A DEPOSIT OF 9.98 TONNES OF GOLD INTO THE GLD/ ////:/INVENTORY RESTS AT 1056.62 TONNES
SEPT 2//2026/WITH GOLD UP $19.25 /HUGE CHANGES IN GOLD AT THE GLD:A DEPOSIT OF 4.28 TONNES OF GOLD INTO THE GLD/ ////:/INVENTORY RESTS AT 1046.64 TONNES
SEPT 1//2026/WITH GOLD DOWN $80.25 /NO CHANGES IN GOLD AT THE GLD:// ////:/INVENTORY RESTS AT 1042.36 TONNES
GLD INVENTORY: 1059.04 TONNES, TONIGHTS TOTAL GOLD INVENTORY
SILVER
OCT 20 WITH SILVER UP $0.68 : :NO CHANGES A WITHDRAWAL OF 943,000 OZ INTO OUT OF SLV// // :INVENTORY RESTS AT 497.650 MILLION OZ
OCT 16 WITH SILVER UP $1.19 : :MEGA HUGE CHANGES A DEPOSIT OF 4.374 MILLION OZ INTO THE SLV// // :INVENTORY RESTS AT 498.593 MILLION OZ
OCT 15 WITH SILVER UP $1.19 : :SMALL CHANGES A DEPOSIT OF 406,000 OZ INTO THE SLV// // :INVENTORY RESTS AT 494.219 MILLION OZ
OCT 14 WITH SILVER DOWN $3.25 : :SMALL CHANGES A WITHDRAWAL OF 135,000 OZ OUT OF THE SLV// // :INVENTORY RESTS AT 493.948 MILLION OZ
OCT 13 WITH SILVER DOWN $0.97 : :HUGE CHANGES A DEPOSIT OF 722,000 OZ INTO THE SLV// // :INVENTORY RESTS AT 493.813 MILLION OZ
OCT 12 WITH SILVER DOWN $0.51 : :HUGE CHANGES A DEPOSIT OF 722,000 OZ INTO THE SLV// // :INVENTORY RESTS AT 493.948 MILLION OZ
OCT 9 WITH SILVER UP $0.62 : :SMALL CHANGES A DEPOSIT OF 948,000 OZ INTO THE SLV// // :INVENTORY RESTS AT 493.226 MILLION OZ
OCT 8 WITH SILVER DOWN $0.74 : :SMALL CHANGES IN INVENTORY AT THE SLV:A WITHDRAWAL OF 532,000 OZ FROM THE SLV// // :INVENTORY RESTS AT 492.278 MILLION OZ
OCT 7 WITH SILVER DOWN $1.36 : :SMALL CHANGES IN INVENTORY AT THE SLV:A WITHDRAWAL OF 451,000 OZ FROM THE SLV// // :INVENTORY RESTS AT 492.910 MILLION OZ
OCT 6 WITH SILVER UP $0.31 : :NO CHANGES IN INVENTORY AT THE SLV: // :INVENTORY RESTS AT 493.361 MILLION OZ
OCT 5 WITH SILVER UP $0.87 : :NO CHANGES IN INVENTORY AT THE SLV: // :INVENTORY RESTS AT 493.361 MILLION OZ
OCT 2 WITH SILVER DOWN $0.74 : :NO CHANGES IN INVENTORY AT THE SLV: // :INVENTORY RESTS AT 493.578 MILLION OZ
OCT 1 WITH SILVER UP $0.57 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 1.400 MILLION OZ OUT OF THE SLV// :INVENTORY RESTS AT 493.578 MILLION OZ
SEPT 30 WITH SILVER DOWN $0.55 : :HUGE CHANGES IN INVENTORY AT THE SLV: A DEPOSIT OF 994,000 OZ INTO THE SLV// :INVENTORY RESTS AT 494.978 MILLION OZ
SEPT 29 WITH SILVER DOWN $0.58 : :SMALL CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 566,000 OZ FROM THE SLV// :INVENTORY RESTS AT 493.984 MILLION OZ
SEPT 28 WITH SILVER DOWN $2.91 : :SMALL CHANGES IN INVENTORY AT THE SLV: A DEPOSIT OF 0.542 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 494.436 MILLION OZ
SEPT 25 WITH SILVER DOWN $2.91 : :SMALL CHANGES IN INVENTORY AT THE SLV: A DEPOSIT OF 0.542 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 494.436 MILLION OZ
SEPT 24 WITH SILVER DOWN $0.96 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 0.813 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 493.533 MILLION OZ
SEPT 23 WITH SILVER UP $1.58 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 1.716 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 494.346 MILLION OZ
SEPT 22 WITH SILVER UP $0.10 : :NO CHANGES IN INVENTORY AT THE SLV: :INVENTORY RESTS AT 496.062 MILLION OZ
SEPT 21 WITH SILVER UP $1.04 : :HUGE CHANGES IN INVENTORY AT THE SLV: :INVENTORY RESTS AT 489.558 MILLION OZ
SEPT 18 WITH SILVER UP $1.04 : :NO CHANGES IN INVENTORY AT THE SLV: :INVENTORY RESTS AT 489.558 MILLION OZ
SEPT 17 WITH SILVER UP $1.10 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 1.265 MILLION OZ FROM THE SLV/ :INVENTORY RESTS AT 489.558 MILLION OZ
SEPT 16 WITH SILVER UP $0.95 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 813,000 OZ FROM THE SLV/ :INVENTORY RESTS AT 490.823 MILLION OZ
SEPT 15 WITH SILVER DOWN $0.16 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 813,000 OZ FROM THE SLV/ :INVENTORY RESTS AT 491.636 MILLION OZ
SEPT 14 WITH SILVER DOWN $0.91 : :NO CHANGES IN INVENTORY AT THE SLV:/ :INVENTORY RESTS AT 492.449 MILLION OZ
SEPT 11 WITH SILVER DOWN $3.50 : :NO CHANGES IN INVENTORY AT THE SLV:/ :INVENTORY RESTS AT 492.449 MILLION OZ
SEPT 10 WITH SILVER DOWN $3.50 : :NO CHANGES IN INVENTORY AT THE SLV:// / :INVENTORY RESTS AT 493.171 MILLION OZ
SEPT 9 WITH SILVER UP $0.56 : :NO CHANGES IN INVENTORY AT THE SLV:// / :INVENTORY RESTS AT 493.171 MILLION OZ
SEPT 8 WITH SILVER UP $0.31 : :HUGE CHANGES IN INVENTORY AT THE SLV:/ A DEPOSIT OF 0.632 MILLION OZ INTO THE SLV// / :INVENTORY RESTS AT 493.171 MILLION OZ
SEPT 4 WITH SILVER UP $2.20 : :NO CHANGES IN INVENTORY AT THE SLV:/// / :INVENTORY RESTS AT 492.539 MILLION OZ
SEPT 3 WITH SILVER UP $2.20 : :HUGE CHANGES IN INVENTORY AT THE SLV:A WITHDRAWAL OF 1.293 MILLION OZ FROM THE SLV//// / :INVENTORY RESTS AT 492.539 MILLION OZ
SEPT2 WITH SILVER UP $0.15 : :NO CHANGES IN INVENTORY AT THE SLV:// / :INVENTORY RESTS AT 493.832 MILLION OZ
SEPT1 WITH SILVER DOWN $1.43 : :NO CHANGES IN INVENTORY AT THE SLV:// / :INVENTORY RESTS AT 493.832 MILLION OZ
CLOSING INVENTORY 497.650 MILLION OZ OF SILVER
GOLD COMMENTARIES:
1.PETER SCHIFF//JOHN RUBINO//RAVEN
1 B // JAMES RICKARDS/MATHEW PIEPENBURG/ALASDAIR MACLEOD..
ALASDAIR MACLEOD…
3. CHRIS POWELL AND HIS GATA DISPATCHES
4. ANDREW MAGUIRE//KINESIS LIVE FROM THE VAULT/293
5. COMMODITY REPORT //GOLD
Shelton’s Gold Bonds: The Plumbing Behind a Gold Deal With China
Over the last two weeks, Luke Gromen has been talking about how the gold market, the price of gold, could be used to facilitate or offset our debt and at the same time make peace in the trade wars with China.
We agree fully with him and we’d like to offer some insight into how the mechanics of that could be happening right now, how the plumbing for that could be being built right now, and how the plumbing for that will mesh or intermingle to make what he’s talking about happen.
The story this has to do with that describes the plumbing underlying what Luke is talking about is titled Judy Shelton’s Gold Bonds May Have Found Their Moment, which describes the bonds and how they would work for people who bought them and how they would work for the U.S. government.
Her proposal, 50-year zero-coupon bonds redeemable in the owner’s choice of either dollars or gold bullion, could become an instrument in negotiations with China.
Domestically, this idea is to use gold to make treasuries more attractive and reduce our borrowing costs. Investors get a treasury bond essentially with a gold option embedded in it.
Internationally, There’s another possibility. If Treasuries take Shelton’s proposal seriously, and they should, (and her hiring also suggests it deserves attention), Eric Yeung, Luke Gromen, and I, from different points of view, see an opening.
The U.S. could approach China and say, you want to make gold more liquid, correct? We can help by offering gold-linked Treasury bonds as collateral in your system.
That could help turn China’s initiative into a global system with the U.S. participating and gold playing the larger role that it should.
China would benefit if the arrangement supported higher gold prices, which it will. The U.S. would benefit by connecting gold’s appeal to the liquidity of the Treasury market.
That’s the potential bargain. China expands gold’s financial role while the U.S. strengthens demand for its debt.
I’m not saying this will happen. I’m saying that it’s feasible. And if we want to do this and we take what Judy Shelton is talking about seriously, something like that can be done.
This plays into something that Eric Young and I talked about specifically over the last several months, and that is the fact that China… China wants gold to be a repo-able asset.
China wants gold to be HQLA, a high quality liquid asset, internationally recognized, not just regionally recognized. And one of the ways to do that is for the U.S. to come in and say, well, we’ll let you make gold an internationally recognized high quality liquid asset if we bond it with the U.S. Treasury bond, because the U.S. Treasury bond is a high quality liquid asset.
And if you take our 50 years zero coupon gold bonds, In your system, or Judy Shelton’s TTBs, Then what you have is you have the best of both worlds and you basically can create a hybrid situation where using gold’s appeal makes treasuries more attractive.
Using gold, using treasuries liquidity makes gold more liquid. And you have a market that’s much more robust and internationally appealing it makes concepts like m-bridge obsolete.
YOUR EARLY CURRENCY VALUES/GOLD AND SILVER PRICING/ASIAN AND EUROPEAN BOURSE MOVEMENTS/AND INTEREST RATE SETTINGS TUESDAY MORNING.7:30 AM
SHANGHAI CLOSED UP 4.45 PTS OR 0.12%
HANG SENG CLOSED DOWN 315.09 PTS OR 1.32%
Nikkei CLOSED DOWN 752.70 PTS OR 1.166%
//Australia’s all ordinaries CLOSED UP 0.28%
//Chinese yuan (ONSHORE) CLOSED UP AT 6.6781
/ OFFSHORE CLOSED UP AT 6.6772 Oil UP TO 108.00 dollars per barrel for WTI and BRENT UP TO 111.18 Stocks in Europe OPENED ALL RED
ONSHORE USA/ YUAN// WITH YUAN TRADING 6.6781 OFFSHORE YUAN TRADING UP TO 6.6772 ONSHORE YUAN TRADING BELOW LEVEL // OFF SHORE AND UP ON THE DOLLAR)// / AND THUS STRONGER/OFF SHORE YUAN TRADING UP AGAINST US DOLLAR/ AND THUS STRONGER
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
ONSHORE YUAN: CLOSED UP TO 6.6781
OFFSHORE YUAN: UP TO 6.6772
1A.HANG SANG CLOSED DOWN 319.09 PTS OR 1.32%
1 B. SHANGHAI CLOSED UP 4.45 PTS OR 0.12%
2. Nikkei closed DOWN 752.70 PTS OR 1.16%
WEST TEXAS INTERMEDIATE OIL UP TO 108.00
BRENT; 111.18
3. Europe stocks SO FAR: ALL RED
USA dollar INDEX DOWN 11 BASIS PTS TO 101.67// EURO FALLS TO 1.1212 DOWN 2 BASIS PTS
3b Japan 10 YR bond yield:FALLS TO. +2.896 DOWN 2 FULL BASIS PTS/ VERY TROUBLESOME//Japan buying 100% of bond issuance)/Japanese YEN vs USA CROSS NOW AT 158.18… JAPANESE YEN NOW FALLING AS WE HAVE NOW REACHED THE ENDING OF THE YEN CARRY TRADE AGAIN AND THE REPATRIATION OF YEN DENOMINATED BONDS TRADING IN THE USA/EUROPE. JAPAN 30 YR BOND YIELD: 3.945 DOWN 4 FULL BASIS PTS
3c Nikkei now ABOVE 17,000
3d USA/Yen rate now well ABOVE the important 120 barrier this morning
3e Gold DOWN /JAPANESE Yen DOWN//CHINESE ONSHORE YUAN: UP (6.6781) AND OFFSHORE: UP AT 6.6772
3f Japan is to buy INFINITE TRILLION YEN worth of BONDS. Japan’s GDP equals 5 trillion USA. CENTRAL BANK OF JAPAN WILL NO LONGER DO QE.
Japan to buy 100% of all new Japanese debt and NOW they will have OVER 50% of all Japanese debt. GOVERMENT ASKED JAPAN PENSION FUNDS AND INSURANCE FUNDS TO BUY MORE JAPANESE BONDS AND REPATRIATE ALL FOREIGN BONDS.
3g Oil UP for WTI and UP for Brent this morning
3h European bond buying continues to push yields HIGHER on all fronts in the EU German 10yr bund YIELD UP TO +3.4312/ Italian 10 Yr bond yield UP AT 4.6013/ SPAIN 10 YR BOND YIELD UP TO 4.067%
3i Greek 10 year bond yield UP TO 4.421%
3j Gold at $4118.80 /Silver at: 57.11 1 am est) SILVER NEXT RESISTANCE LEVEL AT $100.00
3k USA vs Russian rouble;// Russian rouble UP 0 AND 13/ 100 roubles/82.61
3m oil (WTI) into the 108 dollar handle for WTI and 111 handle for Brent/
3n Higher foreign deposits moving out of China// huge risk of outflows and a currency depreciation. This can spell financial disaster for the rest of the world/
JAPAN ON JAN 29.2016 CONTINUES NIRP. THIS MORNING RAISES AMOUNT OF BONDS THAT THEY WILL PURCHASE UP TO .5% ON THE 10 YR BOND///YEN TRADES TO 158.18 // 10 YEAR YIELD AFTER FIRST BREAKING .54% LAST YEAR NOW EXCEEDS THAT LEVEL TO 2.896% DOWN 2 BASIS PTS STILL ON CENTRAL BANK (JAPAN) INTERVENTION//YEN CARRY TRADE NOW UNWINDING//YEN BOND TRADING OVERSEAS TO BE REPATRIATED.//JAPAN 30 YR: 3.945 DOWN 5 PTS..: USA/SF this 0.8250 as the Swiss Franc . Euro vs SF: 0.9252
USA 10 YR BOND YIELD: 5.123 DOWN 2 BASIS PTS…NOW ABOVE 5.00%
USA 30 YR BOND YIELD: 5.452 DOWN 2 BASIS PTS/
USA 2 YR BOND YIELD: 4.729 DOWN 1 BASIS PTS
USA DOLLAR VS TURKISH LIRA: 49.58 UP 3 BASIS PTS/LIRA GETTING KILLED//IDIOTS FOR SELLING GOLD AND USA DOLLAR RESERVES.
10 YR UK BOND YIELD: 5.4393 UP 3 PTS
30 YR UK BOND YIELD: 5.8882 UP 3 BASIS PTS
10 YEAR FRENCH BOND YIELD; 4.960 % //UP 4 BASIS PTS
10 YR CANADA BOND YIELD: 3.960 UP 2 BASIS PTS
5 YR CANADA BOND YIELD: 3.669 UP 2 BASIS PTS.
1a New York Opening report
Futures Slip As Korean Data Center IPO Faceplant Revives Tech Rout, French Spread Blows Out
Tuesday, Oct 20, 2026 – 08:30 AM
US futures are lower, led by the Nasdaq, as Monday’s AI relief bounce fizzled overnight after South Korean data-center firm Elice cratered more than 30% in its trading debut, reviving doubts about who exactly will earn a return on the AI capex binge, while OpenAI is reportedly rushing to raise about $30 billion ahead of Anthropic’s IPO and French stress returned with a vengeance; as a result the OAT-Bund spread widened to a 151bps peak, swiftly approaching the 152bps high from just after the draft budget was presented. As of 8:00am ET, S&P futures are 0.2% lower while Nasdaq futures are down 0.7%; Dow futures are flat, in a repeat of yesterday’s divergence when the S&P rose 0.41% and the Nasdaq jumped 1.11% while the Dow slipped 0.07% and almost two-thirds of S&P components fell (see our wrap of Monday’s session). In premarket trading, Mag 7 names are mostly lower (AAPL -0.9%, META -0.4%, NVDA -0.4%), while levered AI names like CoreWeave and Nebius give back some of Monday’s gains. The day’s driver is AI (again): The spectacular collapse of Korean neocloud Elice, which as we flagged last nightplunged 30% minutes after IPOing, hit chip-heavy Asian markets hardest with the Kospi tumbling 3.65% and Hynix slumping, and with the Fed in blackout ahead of the Oct. 28 FOMC, tech earnings are the only game in town this week. Treasuries are marginally firmer with the 10Y yield down 2bps at 5.12%, tracking a haven bid in Bunds even as French OATs underperform and Gilts lag after a hawkish UK jobs report. The dollar is modestly weaker, with the DXY in a 101.74-101.98 range and cable rising after UK unemployment unexpectedly fell to 4.7%. Brent holds above $110/bbl near a five-month high and European gas is back near €90/MWh, gold slips toward the bottom of its $4,116-4,147 range and copper hovers around $14,400/t. Bitcoin is choppy around $81-82k. US economic data slate includes ADP weekly employment (8:15am), September housing starts and building permits and the Philly Fed non-manufacturing survey (8:30am) and September pending home sales (10am). There are no Fed speakers as the Fed is in its blackout period ahead of next week’s FOMC.
In premarket trading, Magnificent Seven stocks are mostly lower: Apple (AAPL) slips 1% after after Loop Capital Markets downgraded the stock to hold, citing iPhone shipment reductions (Amazon (AMZN) -0.2%, Microsoft (MSFT) +0.4%, Tesla (TSLA) -0.4%, Alphabet (GOOGL) -0.3%, Nvidia (NVDA) -0.7%, Meta Platforms (META) -0.8%, Apple (AAPL) -1%)
3M (MMM) rises 1.4% higher after topping Wall Street’s profit estimates and raising its full-year outlook for the second straight quarter.
Alvotech (ALVO) jumps 7.4% after the US Food & Drug Administration approved a new manufacturing process for the drug Simlandi.
Arhaus (ARHS) rises 4% after Piper Sandler upgraded the furniture company to overweight, writing that “a positive business inflection appears to be underway.”
AST SpaceMobile (ASTS) falls more than 2% after Viasat petitioned the FCC to reject the company’s request for additional overseas spectrum authority
CoreWeave (CRWV) falls over 3% even after Cathie Wood’s ARK bought the dip on Monday; the stock had rallied yesterday after Goldman upgraded it to Buy
General Motors (GM) falls 7% after narrowing its full-year profit forecast.
Halliburton (HAL) rises 3.7% after the oilfield services company reported third-quarter adjusted earnings per share that beat the average analyst estimate as drilling and evaluation revenue was higher than expected. The company also forecast mid-single digit revenue growth for 2027.
Hertz (HTZ) climbs 7.1% after Oro Mobility, which is backed by the car rental company, secured an $80 million strategic equity investment from a consortium of investors, including Cohen Private Ventures.
MSCI Inc. (MSCI) gains 6.5% after the index provider reported adjusted earnings per share for the third quarter that beat the average analyst estimate.
Nebius (NBIS) drops more than 2%, tracking weakness across AI-related stocks
NuScale Power (SMR) falls 7.2% after Barclays cut its recommendation on the nuclear reactor company to underweight as it sees risks from a lack of contracts.
Rapport Therapeutics’ (RAPP) soars 34% after the drug developer said a mid-stage trial of its experimental therapy for acute bipolar mania met the primary endpoint. Shares have since pared gains to 28%.
Solstice Advanced Materials (SOLS) gains 2.9% after the Financial Times reports that activist hedge fund Starboard Value has built a stake in the Honeywell spinoff, citing unidentified people familiar with the matter.
3M (MMM) in focus after signing a deal with Amazon that includes a warrant for 3.2 million shares, vesting up to $6 billion
Analyst actions: BlackRock (BLK) raised to Buy at TD Cowen; TKO raised to Buy at Arete; Prologis (PLD) raised to Buy at Freedom Capital; Trex (TREX) raised to Buy at Stifel; Live Nation (LYV) cut to Sell at CFRA; Werner (WERN) cut to Neutral at Baird; nVent (NVT) initiated Overweight at JPMorgan
In other corporate news, OpenAI is reportedly rushing to lock in investor commitments for a roughly $30 billion private round, with SoftBank and MGX in talks, before rival Anthropic’s expected mid-November IPO; the raise could value OpenAI above $1.4 trillion and the company is pitching annualized revenue of $50 billion, which it expects to hit $70 billion by year-end (nothing says “no bubble here” like racing to get your round done before the competition lists). ByteDance, Alibaba and Tencent have ordered more than 3 million of Nvidia’s export-compliant RTX PRO 5500 GPUs worth over $35 billion. Amazon plans to invest €16 billion in Germany in 2027 after Chancellor Merz said Berlin aims to quadruple AI compute capacity by 2030, and Business Insider reports Amazon is buying billions of dollars of GPUs and parking them in inventory while it waits for data center capacity to come online. Broadcom signed a 10-year cloud infrastructure agreement with Japan’s NTT Docomo; Waymo reportedly plans a fleet of 20,000 vehicles by the end of 2027; and Micron’s Taiwan union may strike Thursday over a bonus dispute.
Monday’s tech bounce was always going to need confirmation, and overnight it got the opposite. Elice, a Korean neocloud whose KRW201bn IPO was, don’t laugh, “more than 400x subscribed”, fell as much as 33% on its debut, a reminder that the IPO was priced before the AI selloff and that the market’s appetite for levered AI infrastructure has not come back (as we discussed in The AI Canary, the buyers in Korea have disappeared). The result: de-rating of AI and crowded growth trades continued to dominate Asian price action, with the Kospi down 3.65% and back below 5,600, while Nasdaq futures handed back a chunk of yesterday’s gains.
“What they’re questioning is whether every dollar of AI capex earns more than it costs to finance,” said Ninghui Liu, head of investment strategy and research for APAC at State Street Investment Management.
“The weekend’s protests have further intensified concerns about French public finances,” said Pia Fromlet, an economist at SEB.
Under the surface, Monday was hardly a ringing endorsement either. JPM’s Market Intel desk notes that equities rebounded on muted volumes and with little sign of broad participation; equal weight lagged and most of tech’s gains came premarket with limited follow-through. JPM TMT trader Brian Heavey was blunter: “We are NOT seeing any real demand in the AI complex, this feels like a technical over sold bounce after last week’s wipeout,” pointing out that CRWV traded flat after indicating +8% on the Goldman upgrade. His punchline: “Capital markets hold the keys to capex levels going forward.” Andrew Tyler’s team nonetheless stays Tactically Bullish, preferring cyclicals outside tech and selectively buying Semis and Memory weakness via defined-risk options.
Goldman’s desks see the de-risking as largely done but the rotation as unfinished. Per GS Prime data relayed by the Asia sales desk, US L/S net leverage fell 3.2pts last week, the largest weekly drop since Liberation Day, with Info Tech seeing the largest net selling and de-grossing on record, while the HF VIP basket had its worst week since Covid. At the same time retail went the other way, with a record $7 billion pouring into SOXL, as we detailed over the weekend. Goldman’s Sam Dunn described Monday as a “calm start to the week with a relief rally … that felt like a cessation of the high-velocity supply,” with floor activity “a 3 on a 1-10 scale,” while the bank’s chart of the day shows the AI winners vs AI at risk pair is now flat on the year after rising some 100% in the first half. And with an early Q3 read showing only 53% of firms beating EPS by more than one standard deviation (vs a 64% four-quarter average), GS’s Dani Wojdyla notes “the next market move is largely dependent on earnings confirmation.”
Credit remains the pressure point. The FT reports investors are racing to buy credit default swaps to protect portfolios in case the AI boom unravels, CoreWeave CDS remains above 1,000bps per Newsquawk, and Goldman notes AI-related HY spreads widened 25bps vs just 2bps for non-AI issuers. Recall that Morgan Stanley warned that AI’s $1.6 trillion capex plan now lives or dies in the credit market, and Goldman quietly shifted its credit preference toward BBBs as AI debt floods every corner of the market.
In Europe, the French story is back. The 10Y OAT yield jumped 13.4bps to 4.93% on Monday, its highest close since 2002, and the OAT-Bund spread widened again today to a 156bps peak even after protests subsided following tighter security measures and curfews. Goldman’s Alexandre Stott expects the budget to be adopted this year, with Finance Minister Lescure saying the government would take “the unprecedented step of using ordinances to bypass Parliament altogether” if needed, but GS’s poll-based model still sees Le Pen as the clear favorite for 2027. Moody’s is expected to downgrade France on Friday; JPM’s EGB desk thinks it is priced in.
In Europe, the Stoxx 600 is down 0.6%, falling for a second day after nearly a 1% drop on Monday, not helped by the risk tone in Asia and several disappointing company updates. Health care tops the sector pile, followed by personal care and food & beverage, while industrials, tech and basic resources lag. Chip names are hit hardest, with ASML and ASMI each down more than 3% and JPM’s European Semis basket down 3.3%, alongside its Ceasefire, China Exposure and Software baskets among the worst performers. The DAX and Euro Stoxx 50 underperform after a weak ZEW, where the German expectations index dropped to 28.1 vs 30 expected, while German PPI surged 6.7% y/y.
Asian stocks were mostly lower despite the rebound on Wall Street, as the region failed to sustain the AI-led recovery. South Korea’s Kospi slumped 3.65% with roughly 86% of names lower, as foreigners net sold $255 million of tech including $296 million of SK Hynix, amid reports that US big tech is pushing for lower memory prices by citing Chinese suppliers. Japan’s Nikkei fell 1.3% and the Topix 1.4%, with SoftBank, Tokyo Electron and Advantest accounting for about 60% of the Nikkei’s decline; Goldman notes the Topix broke its CTA short-term threshold again, implying around $1.1 billion of CTA selling this week, while Japanese banks fell 4.3% after a strong 20-year JGB auction. The Hang Seng dropped 1.3% as it returned from holiday, with Lenovo down 10% and CATL down 6.6%, while the CSI 300 fell 0.5% after China held its loan prime rates for a 17th month. Taiwan’s Taiex fell 1.1% and Australia’s ASX 200 slipped 0.4%. The exception was Indonesia, where the JCI soared 5.3% after a two-day crash of about 15%, the steepest since 1989 (more here).
In FX, the dollar is modestly softer, with the DXY in a 101.74 to 101.98 range and the low of the day coinciding with its 21-DMA. Sterling is the story after a better than expected UK jobs report, with unemployment falling to 4.7% vs 4.9% expected, lifting cable from 1.3328 to 1.3358 and bolstering the case for a BoE hike in November. The kiwi and loonie outperform, the latter on bets the BoC hikes next week (about 80% priced, up from about 40% last week), while the euro is flat and the only G10 currency failing to gain against the dollar as the OAT-Bund spread widens. The yen is little changed after Reuters reported the BoJ will likely hold in October but could signal a December hike.
In rates, Treasuries are slightly firmer, holding within Monday’s ranges, with the 10Y yield about 2bps lower at 5.12% after Monday’s jump of nearly 7bps; JPM sees 2s flat and 5s, 10s and 30s about 1bp lower, with no overt flattening or steepening bias. Bunds outperform, rallying about 3bps on a modest haven bid from the tepid Asian risk tone, while French OATs lag as the OAT-Bund spread widens to 151bps ahead of Moody’s Friday review, and gilts slip after the hawkish jobs data. In Japan, a strong 20-year JGB auction (5.84x bid-to-cover vs 4.01x prior) boosted JGBs. With the Fed in blackout ahead of the Oct. 28 FOMC, the focus is on tech earnings and geopolitics (in a market where the 10Y sits above 5%, apparently that passes for calm).
In commodities, crude is choppy but holds near the top of its range: Brent trades above $111/bbl in a $109.00-111.75 range, near a five-month high, while WTI briefly topped $100 ($98.04-100.93). Iran’s IRGC said two oil tankers struck naval mines along the southern route of the Strait of Hormuz and that it downed a US MQ-9 drone, while Pakistan’s Army Chief arrived in Tehran for talks and the Iranian Foreign Ministry struck a conciliatory tone. IEA chief Birol said the agency will consider releasing more emergency stocks if needed. Dutch TTF gas is climbing again in a €87.60-89.80/MWh range. Spot gold is at the lower end of its $4,116-4,147/oz range, and LME copper briefly slipped below $14,300/t before rebounding to $14,410/t.
US economic data slate includes ADP weekly employment (8:15am), September housing starts and building permits and Philly Fed non-manufacturing activity (8:30am) and September pending home sales (10am). The Fed is in blackout. On the corporate calendar, GE Aerospace, RTX, GM, 3M, Northrop Grumman and Halliburton report before the open, Netflix, SpaceX, United Airlines, Capital One and Intuitive Surgical report after the close, and Nvidia’s GTC Berlin runs through Thursday.
Market Snapshot
Top Overnight News
Nasdaq futures fell as shares of South Korean data-center infrastructure company Elice plunged over 30% in their trading debut. BBG
ByteDance, Alibaba and Tencent have ordered more than 3 million of Nvidia’s new RTX PRO 5500 graphics cards with a collective sticker price of over $35 billion, two people familiar with the matter said, in a rush for a less powerful but export-compliant chip amid US restrictions on trade with China. RTRS
Investors are racing to buy credit default swaps to protect their portfolios in the event the AI boom unravels, sending trading volumes surging for an instrument that shot to prominence during the global financial crisis. FT
AMZN (Amazon) is buying billions in GPUs and putting them in inventory as it waits for the necessary data center capacity to come online and power them up. Business Insider
OpenAI is seeking to raise about $30 billion, including from SoftBank and MGX, ahead of Anthropic’s expected mid-November IPO, in a round that could value it above $1.4 trillion. RTRS
Netflix plans to cut about 6% of its workforce, or roughly 1,000 roles, its largest round of cuts since 2022, ahead of results after the close. RTRS
The French-German 10-year yield spread widened to 156 bps even after protests in France subsided following tighter security measures. Treasuries advanced and Brent climbed to a five-month high. BBG
The UK will fly defensive missions to protect Saudi Arabia from Houthi attacks, officials familiar with the matter said. Iran’s IRGC said two oil tankers struck naval mines along the southern route of the Strait of Hormuz, according to Tasnim. BBG
Ryanair Holdings Plc Chief Executive Officer Michael O’Leary predicted a record increase in European air fares next year due to the Middle East war driving up oil prices. BBG
Japan is months from running out of supplies of yttrium, a critical metal, and has asked the US to push China to ease rare earth export controls that threaten severe disruption to the global automotive, defense and chip industries. FT
President Trump said on Monday the US Department of Agriculture will launch what he called a new “harvest fuel relief program” that will provide farmers with $8 billion in support to offset diesel costs during the harvest season. RTRS
The BoJ is reportedly likely to keep rates unchanged in October, but could signal that a rate hike could come in December: Reuters
US President Trump posted that American incomes have reached record highs, employment and exports are at all-time highs, and the US is now the “hottest” country in the world. Newsquawk
UK Chancellor Healey has reportedly ruled out raising capital gains tax in the October 28th Budget amid concerns over growth and investment: The Times
The Trump administration has delayed approving transfers of Patriot interceptor missiles to Ukraine from partner countries: Washington Post
US L/S net leverage fell 3.2pts last week, the largest weekly drop since Liberation Day, with Info Tech seeing the largest net selling and de-grossing on record. GS Prime
JPM Positioning Intel: hedge funds are -2.1% MTD globally, but AI Core Revenue positioning is still at the 94th percentile; the setup resembles 3Q23 and a 4Q rally is seen as more likely than not. JPM
Goldman raised its copper forecasts to $14,700/t for end-2026 and $15,400/t for the 2027 average.
A more detailed look at global markets courtesy of Newsquawk
APAC stocks were mostly lower despite the rebound on Wall Street, as the region failed to sustain the AI-led recovery, with chip-heavy markets in South Korea and Japan underperforming but macro newsflow rather light. ASX 200 declined, with gold miners pressured following Monday’s pullback in the precious metal, while financials were in focus after S&P downgraded Bank of Queensland’s long-term rating to BBB+ from A-, and Westpac flagged an AUD 41mln notable item related to RAMS litigation. Nikkei 225 was subdued as tech names failed to benefit from the AI-led rebound stateside, although the index pared some of its earlier losses of over 1%. SoftBank was in focus following reports that it is in discussions to participate in OpenAI’s private funding round ahead of Anthropic’s IPO. KOSPI was the regional laggard, extending its October rout, with Samsung Electronics and SK Hynix pressured amid reports that US big tech firms are pushing for lower memory prices by citing Chinese suppliers as alternatives. Hang Seng and Shanghai Comp diverged, with Hong Kong lower as it returned from Monday’s Chung Yeung holiday, while the mainland was flat as Chinese LPRs were maintained, as expected.
Top Asian News
Japanese Finance Minister Katayama said no decisions have been made on funding defence spending increases, but measures to secure stable funding will be considered while maintaining fiscal sustainability.
China’s NDRC said it will introduce additional policy measures as needed to keep economic activity within a reasonable range.
European bourses (STOXX -0.6%) are lower again on Tuesday, not helped by the risk tone in Asian equities, while updates from several companies also disappointed. Focusing on South Korea, Elice had a poor debut, slumping as much as 30%. This can have a read-across for the tech space as Elice is a data-centre firm which provides AI cloud services as well as AI-based education and business software. To note, the IPO price was set before the recent sell-off in AI-related stocks, exacerbating the downside on debut day. Sectors highlight the negative bias. Health Care tops the sector pile, with Optimised Personal Care and Food, Beverages & Tobacco rounding out the top three. To the downside reside Industrials, with Tech and Basic Resources following closely behind. US equity futures are mixed, with the NQ underperforming as it gives back some of Monday’s gains. Plenty of earnings to keep an eye on today, which include RTX, GM, GE Aerospace and SpaceX.
Top European News
UK Chancellor Healey has reportedly ruled out raising capital gains tax in the October 28th Budget amid concerns over growth and investment, The Times reported. The Chancellor reportedly plans to increase taxes on banks, introduce targeted cost-of-living support and reduce fiscal headroom from GBP 23bln to around GBP 15bln in the October 28th Budget.
French President Macron and German Chancellor Merz got behind agreeing an EU budget before end-2026, Politico reported citing officials. However, a German source said no landing zones of specific numbers have been agreed.
German Chancellor Merz said they aim to quadruple AI compute capacity by 2030 with its data centre strategy. Following this, Amazon (AMZN) announced plans to invest EUR 16bln in Germany in 2027, pledging to build more sustainable infrastructure across Germany and to strengthen water-resource management.
US President Trump urged European countries to close their borders and deport migrants.
FX
G10s are stronger against the broadly softer USD, and to varying degrees. The Kiwi outperforms, followed closely by the Loonie. The EUR is flat, and is the mild underperformer this morning.
USD is under very mild pressure this morning, but has found some strength as it trades in a 101.74 to 101.98 range; the low of the day coincides with its 21-DMA. There is no specific driver for the pressure this morning, but perhaps as AI-concerns remain front of mind, particularly as the swap on CoreWeave CDS remains elevated beyond 1,000 points. With the data docket fairly light for the remainder of the week, and the Fed on blackout, markets will have to use geopolitical developments and/or tech earnings as a proxy for sentiment. Bar any debt-related concerns, the index should remain within familiar ranges into the FOMC next week.
Kiwi is the mild outperformer this morning, benefiting from slightly firmer copper prices. The Loonie has been lifted in the past few days amidst a recent hawkish repricing at the BoC; as it stands, money markets assign a c. 80% chance of a hike next week (vs c. 40% last week). To remind, BoC Governor Macklem recently stated that higher energy prices are lifting the inflation outlook, signalling that the Bank stands ready to raise rates.
The GBP benefits from a better-than-expected UK Jobs report. In brief, the Unemployment Rate fell to 4.7% vs expectations of it holding steady at 4.9%; Employment Change also jumped from the prior, and above consensus. As for the wage components, they remain benign, with little evidence of second-round effects filtering through so far. Overall, this report will provide confidence to the more hawkish members on the MPC, to deliver a rate hike in November. Following the data, Cable rose from 1.3328 to 1.3358, and currently holds at the upper end of the day’s 1.3302-1.3358 range.
EUR is flat vs the USD, and the only G10 currency failing to benefit from the softer Dollar. Pressure that stems from the ongoing widening of the OAT-Bund spread, which has now breached its recent peak of 151bps; a move which comes amidst ongoing civil unrest in France, and now several parts of Europe. Adding to the negative sentiment is a poor German/EZ ZEW Sentiment read, which fell from the prior and by more than expected.
Central Banks
The BoJ is reportedly likely to keep rates unchanged in October, but could signal that a rate hike could come in December, according to Reuters sources. The report added that the Bank may also raise its FY27 inflation forecast slightly.
Fixed Income
A contained start for fixed generally, USTs in a thin 105-05 to 105-12+ band, into a much busier docket than Monday, but one that is still generally awaiting events over the next few weeks; barring a significant geopolitical development, of course.
Currently, this leaves USTs entirely within Monday’s confines, by just a tick at the low-end and 12+ at the upper-end. Yields lower across the curve, though only marginally and with no overt flattening/steepening bias currently seen.
EGBs tracked USTs overnight, with a modest haven bid coming from the tepid APAC risk tone, but offset by energy upside, points that left the space near-enough flat in early trade. Thereafter, a hawkish UK job series pushed Bunds down by about five ticks, before this unwound and a 121.39 peak printed in the early morning.
Specifics for the bloc thus far a little light, we mainly await updates on the fiscal front, as Politico suggests that German Chancellor Merz and French President Macron are more aligned on the need to get the next framework done by end-2026. Albeit, the immediate focus is on the weekend’s unrest, with French curfews approved more widely, though the litmus test will be the coming weekend’s planned action; and then the demonstrations unions are calling for in early-November.
Reflecting the ongoing French political, and by extension, fiscal risk, the OAT-Bund 10yr yield spread has widened to a 151bps peak today, swiftly approaching the 152bps high from just after the draft budget was presented. Again, such widening does not bode well into Moody’s on Friday.
Finally, Gilts opened with some modest downside, but didn’t stray too far from the 84.00 handle. Thereafter, some slight choppiness was seen in 83.85 to 84.13 confines amid a number of factors being digested at once; since, it has slipped into the red and marginally lags.
Pressure that comes on the energy upside and hawkish jobs data, the latter being another factor in favour of a BoE hike in November, or at the very least by end-2026. Elsewhere, the discussed risk tone would have had a modest offsetting influence. While reports around the budget could be taken either way. Specifically, The Times reported that Chancellor Healey has abandoned plans to increase Capital Gains Tax, due to the likely growth hit. A point that reduces his revenue-raising avenues, and this means a lower headroom is likely to result; however, it factors well for confidence levels in domestic business.
Germany sells EUR 0.992bln vs Exp. EUR 1bln 2.10% 2029 Green Bobl and 1.80% 2053 Green Bund.
The UK sells GBP 4.25bln 4.875% 2036 Gilt: 3.61x (prev. 3.34x), Average Yield 5.418% (prev. 5.383%), Tail 0.2bps (prev. 0.5bps).
Japan sells JPY 700bln 20yr JGB; b/c 5.84x (prev. 4.01x). average yield 3.7230% (prev. 3.8560%), tail 0.07 (prev. 0.15).
Commodities
Crude benchmarks have been choppy at the start of Tuesday’s European session, but ultimately reside at the top end of their daily range. WTI briefly tops USD 100/bbl (USD 98.04-100.93/bbl) while Brent holds above USD 110/bbl (USD 109.00-USD 111.75/bbl).
Geopolitical headlines have been light thus far. Overnight, the IRGC said it downed a US MQ-9 drone over Hormuz. Elsewhere, Saudi Arabia and Houthis continue to strike each other, with reports this morning suggesting that Saudi intercepted missiles heading towards Riyadh.
As for the path to diplomacy, Pakistan’s Army Chief has arrived in Tehran, so focus will be on any updates following these talks. Recent comments from Iranian officials have suggested that he is yet to arrive in Tehran. This morning there were some updates from the Iranian Foreign Ministry spokesman who struck a conciliatory tone, but ultimately did not spur a reaction in the crude complex. He mentioned that Iran held several contacts and consultations, adding that if there is even the slightest chance that it may be able to prevent the escalation of tensions through diplomacy, it must definitely go this route. However, sticking points in negotiations remain on the Strait of Hormuz and nuclear issues.
Dutch TTF is back on the climb, and currently sits at the upper end of its EUR 87.60-89.80/MWh range, with the peak just above Monday’s peak of EUR 89.70/MWh.
Precious metals continue to gradually fall, with spot gold at the lower end of its USD 4116-4147/oz range, but remains well-contained within the wider USD 4067-4228/oz band. The yellow metal will continue to be driven by yields. The next level on the US 10yr that could spur upside in the precious metal is back below the 5% level.
3M LME Copper briefly slipped below USD 14.3k/t, falling to a trough of USD 14.27k/t before rebounding to a current peak of USD 14.41k/t. Traders highlight the risk of tariffs as a downside risk for the red metal. The metal benefited from the surge of copper being piled in the US, in anticipation of tariffs being placed on copper imports. However, this possibility is fading somewhat, according to a trader at Ningbo.
IEA Chief Birol said they will consider releasing more emergency stocks if needed.
US Energy Secretary Wright said no Russian Diesel has been released yet and yet to be seen if Russia will release diesel.
Saudi and the UAE have committed to provide 95k and 100k tonnes per month, respectively, of diesel to France. Deliveries to begin in the coming weeks.
Trade/Tariffs
The UK Treasury is expected to be asked to assess the economic benefits of closer ties with the EU, including a potential customs union, single market return or full EU membership, ahead of the November 20th Brussels summit, according to the FT.
Geopolitics: Middle East
US President Trump criticised Europe for failing to support the US over Iran and suggested Washington could reconsider its support for Europe.
Iran’s IRGC said it intercepted and destroyed a US MQ-9 drone over the Strait of Hormuz using its new advanced air defence system.
Iranian Foreign Ministry Spokesperson Baghaei said they have held several contacts and consultations and that if there is even the slightest chance that it may be able to prevent the escalation of tensions through diplomacy, they must definitely go this route. On talks with Russia, Baghaei said there was no discussion about nuclear negotiations with the US, and that Iran are not negotiating with the US in this regard.
Iranian Foreign Ministry said the US’ response to the proposal from Iran was incomplete and insufficient.
Iranian President Pezeshkian said US bases in the region provide no benefits and only fuel insecurity, Press TV reported.
Iranian Foreign Minister Araghchi said Iran-Russia cooperation is closer than ever, with talks covering regional developments and expanding economic and nuclear cooperation, IRNA reported.
Qatari Foreign Ministry spokesperson said “We are working with Washington and Tehran in partnership with other mediating countries to end the war in the region.”
Pakistan Army Chief Munir has arrived in Tehran to meet with senior officials of Iran.
Russian Foreign Minister met Iran’s President and Supreme National Security Council Secretary in Tehran, following earlier talks with his Iranian counterpart, Iran Nuances reported.
An explosion was reportedly heard in Iran’s southern city of Bandar Abbas, Sabereen News reported.
Yemeni forces reportedly targeted Saudi Arabia’s Dammam airport with missiles and drones, temporarily suspending operations, Tasnim reported, citing Al-Masirah.
Israeli PM Netanyahu said there are indications that Iran and its proxies want to challenge Israel before the elections.
US War Secretary Hegseth met Israeli PM Netanyahu during an unannounced visit to Israel on Monday, Axios reported.
Geopolitics: Ukraine
US President Trump’s envoys Kushner and Witkoff plan to travel to Norway this week for Ukraine talks and Ukraine President Zelensky is expected to join talks.
Ukrainian President Zelensky said he talked with US Secretary of State Rubio on the topics of ballistic interceptors and Starlinks. He later said that Ukraine supports a mutual energy ceasefire.
Ukraine’s DTEK said a Russian attack struck three of its energy facilities in the Odessa region.
The Trump administration has delayed approving transfers of Patriot interceptor missiles to Ukraine from partner countries, Washington Post reported.
Crypto
Bitcoin has been choppy, briefly topping USD 82k before returning to its session low of USD 81.1k.
US Event Calendar
8:15am: ADP Weekly Employment Change
8:30am: Sep Housing Starts, est. 1304.5k, prior 1275k
8:30am: Sep P Building Permits, est. 1385k, prior 1403k
8:30am: Oct Philadelphia Fed Non-Manufacturing Activity
10:00am: Sep Pending Home Sales MoM, est. -0.5%, prior 0.3%
Central Bank Speakers
No Fed speakers: the Fed is in its blackout period ahead of the Oct. 28 FOMC
BoE’s Greene and RBA’s Hauser speak
DB’s Jim Reid concludes the overnight wrap
I wanted to start by highlighting yesterday’s CoTD “Different Ways to Skin Capex”, partly as it took me a long time to do, and partly as the graphs may not have been easy to read on email. Hopefully with the link to the piece on the DBRI site here, they’re slightly easier to read. The key divide from the main chart is that over the last year the gap has increased between those writing the enormous AI capex cheques and those cashing them in. Many of the big spenders have gone sideways, while the physical bottlenecks in memory, storage, chip packaging and networking have been the big winners. There is a second striking split between “atoms” and “bits”, with Asian hardware names surging as software and Indian IT services have lagged, alongside sharp falls among some of the more leveraged AI build-outs. Apple and Alphabet are notable mega-cap exceptions, but for different reasons — Apple because it has largely avoided the data-centre capex arms race, and Alphabet because it is increasingly demonstrating that heavy AI spending can translate into revenue. The broader conclusion is that investors are no longer simply investing in Big Tech or AI in aggregate: they are investing in Big Tech’s budgets, while becoming much more discriminating about who ultimately earns an adequate return from them. See the short note for more. I think it breaks things down nicely.
It’s been another eventful 24 hours for markets, with a bunch of competing narratives for investors to grapple with. On the bright side, the AI selloff began to stabilise, with the Philly semiconductor index (+1.61%) finally breaking a run of 8 consecutive declines. So that helped to lift US equities in aggregate, and the S&P 500 (+0.41%) posted a recovery despite most of its constituents falling on the day. That said, tech stocks in Asia have weakened again so the volatility continues. There’s been considerable volatility elsewhere as well, as the stress around French assets returned after the weekend unrest. Indeed, the Franco-German 10yr spread (+10.3bps) hit a post-2012 high on a closing basis, ending the session at 148bps. And matters weren’t helped by another rise in European natural gas prices, which moved up to a post-2022 high of €88.04/MWh. So that fuelled the broader economic concerns around the continent, with equities including the STOXX 600 (-0.80%) posting sharp declines.
We’ll start with the French story, as that created the biggest market moves over the session, with the negativity clear from the open. The impact was most obvious for the country’s sovereign debt, with 10yr French OAT yields up +13.4bps on the day to 4.93%, their highest closing level since 2002. Moreover, because Germany’s 10yr bund yields were “only” up +2.9bps on the day to 3.45%, that pushed the 10yr OAT-bund spread up to 148bps by the close. Admittedly, it wasn’t quite as high as the intraday peak above 150bps earlier this month, so we haven’t returned to peak stress yet. But after two weeks when the spread had broadly stabilised, the concerns were clearly picking back up in yesterday’s session. Indeed, it was a similar story for the 2yr spread as well, which also jumped up +6.6bps on the day to 54bps.
Those market concerns around French debt cascaded across other countries and asset classes too. For instance, the Italian 10yr spread over bunds was also up +4.7bps on the day to 111bps, whilst Spain’s was up +1.2bps to 62bps. Meanwhile in equities, the STOXX Banks index (-2.07%) hit a 4-month low, and there were even bigger declines for the French banks, including Société Générale (-3.41%), Crédit Agricole (-2.64%) and BNP Paribas (-2.48%). And in turn, all that caused fresh pressure for the Euro itself, which weakened -0.23% against the US Dollar to close at $1.1213. The Euro is back up +0.17% this morning as the unrest in France didn’t continue overnight after strict curfews and other measures were implemented across the country.
Yesterday’s news out of Europe was exacerbated by the latest moves in energy prices, which added to concerns around inflation and further ECB rate hikes. Most strikingly, the front-end natural gas future (+0.56%) rose to €88.04/MWh, which is another post-2022 high, and now leaves it up +21.7% in October alone. So that led investors to price in more inflation, with the 1yr Euro inflation swap (+11.3bps) up to 3.80%, its highest since May.
Oil prices did stabilise but Brent crude (-0.28% top $109.55/bbl) still settled within touching distance of Friday’s 5-month high. Brent had pulled back towards $107/bbl early on Monday, helped by some talk on the wires that US and Iran had reached a breakthrough in mediations that would be announced later in the week. However, the fact that this got very little airtime reflects that markets have heard this story before and will take a lot to believe it. The respite indeed proved short-lived, with oil prices jumping higher around the European close as Iran’s First Vice President Mohammad Reza Aref said that Iran has “no choice but to exercise sovereignty over the Strait of Hormuz”. So that added to the sense that a deal before the US midterms in two weeks’ time is going to be challenging, while investors are also concerned that the US administration may be more likely to escalate against Iran after the midterms as Iran’s increased strikes in Hormuz have now slowed the increase in oil flows through Hormuz that had emerged over the previous couple of months. Perhaps reflecting that, the longer-dated futures continued to climb, with 12-month Brent futures (+0.14%) at another high for the year of $88.00/bbl, implying an extended period of high oil prices deep into 2027.
Whilst the European news was overwhelmingly negative, US equities put in a stronger performance, though the rally did lose some momentum as oil prices rebounded. The improvement was led by tech stocks, as the NASDAQ (+1.11%) had its best day in two weeks, and the Philly semiconductor index (+1.61%) finally ended a relentless run of 8 consecutive declines. So given the concentration of tech in the broader index, that actually helped the S&P 500 (+0.41%) to post a steady gain, even as almost two-thirds of components within the index lost ground on the day.
That AI stabilisation also pushed US Treasury yields higher, as it countered fears about an AI-related slowdown. Indeed, that was clear from the fact that higher real yields drove the bulk of the rise in Treasury yields yesterday, rather than inflation breakevens. So Treasury yields saw a consistent rise across the curve, with the 2yr yield (+6.5bps) up to 4.77%, whilst the 10yr yield (+6.6bps) rose to 5.14%. Moreover, that optimism on the growth side saw investors price in slightly more rate hikes for the months ahead. For instance, 74bps of hikes were priced in by the June 2027 meeting at the close, up +7.7bps relative to Friday.
As mentioned up top, the AI trade has reversed back again this morning with the KOSPI (-4.39%) leading the declines, dragged down by chip heavyweight SK hynix Inc. (-5.17%), which is on track for its lowest close since April. The Nikkei 225 (-1.08%) is also being weighed down by tech. Elsewhere, the Hang Seng (-0.95%) is also falling after reopening following a holiday, while China’s CSI 300 (-0.51%) is also soft. Additionally, the S&P/ASX 200 (-0.40%) is also edging lower with National Australia Bank (NAB) shares sliding around -3.0% after the lender announced restructuring charges and job cuts. Meanwhile, S&P 500 futures are up marginally (+0.06%), with Nasdaq 100 futures slipping (-0.20%) along with the overnight tech retreat. Stoxx (-0.60%) futures are continuing Europe’s recent declines and 10yr USTs are -2.1bps lower standing at 5.12% as we go to print.
On the monetary policy front, the PBOC held its one-year and five-year Loan Prime Rates (LPR) steady at 3.00% and 3.50%, respectively. This marks the 17th consecutive month of unchanged benchmark rates, as stronger-than-expected Q3 GDP growth reduced the immediate need for monetary stimulus. While the decision provides no fresh rate relief for borrowers, the PBOC is reportedly considering replacing its seven-day reverse repo rate with the overnight rate as its primary policy benchmark to enhance monetary transmission.
Finally yesterday, there was little data to speak of. However, Canada’s CPI came in slightly softer than expected, with headline CPI only up to +3.1% in September (vs. +3.2% expected). Moreover, both of the core measures followed by the Bank of Canada unexpectedly fell by a tenth. So the median core measure fell to +1.9% (vs. +2.0% expected), and the trim core measure fell to +1.8%. Elsewhere, the US NAHB’s housing market index fell more than expected to 29 in October (vs. 31 expected), its lowest level since 2012.
Looking at the day ahead now, and data releases include UK unemployment for August, US housing starts, building permits and German PPI for September, and the German ZEW survey for October. Otherwise, central bank speakers include the BoE’s Greene. Finally, today’s earnings releases include Netflix, United Airlines and General Motors.
1b) European opening report
Iran’s Foreign Ministry suggested that the country favours diplomacy, though crude benchmarks continued to move higher; GBP gains post-jobs data – Newsquawk US Market Open
Tuesday, Oct 20, 2026 – 06:18 AM
Iranian Foreign Ministry said that if there is even the slightest chance that it may be able to prevent the escalation of tensions through diplomacy, it must definitely go this route.
US equity futures mixed, NQ under pressure as tech resumes last week’s selloff.
DXY slightly lower; GBP firmer on an upbeat jobs report, while JPY unmoved following BoJ sources.
Fixed income benchmarks have a slight positive tilt; JGBs boosted by a strong 20-year auction.
Energy benchmarks are firmer despite the IEA head considering a further release of emergency stocks.
Looking ahead, highlights include US Building Permits (Sep), NBH Policy Announcement. Speakers include BoE’s Greene & RBA’s Hauser. Earnings from EssilorLuxottica, GE Aerospace, General Motors, Northrop Grumman, Netflix, SpaceX & United Airlines.
SNAPSHOT
EUROPEAN TRADE
EQUITIES
European bourses (STOXX -0.6%) are lower again on Tuesday, not helped by the risk tone in Asian equities, while updates from several companies also disappointed. Focusing on South Korea, Elice had a poor debut, slumping as much as 30%. This can have a read-across for the tech space as Elice is a data-centre firm which provides AI cloud services as well as AI-based education and business software. To note, the IPO price was set before the recent sell-off in AI-related stocks, exacerbating the downside on debut day.
Sectors highlight the negative bias. Health Care tops the sector pile, with Optimised Personal Care and Food, Beverages & Tobacco rounding out the top three. To the downside reside Industrials, with Tech and Basic Resources following closely behind.
US equity futures are mixed, with the NQ underperforming as it gives back some of Monday’s gains. Plenty of earnings to keep an eye on today, which include RTX, GM, GE Aerospace and SpaceX.
G10s are stronger against the broadly softer USD, and to varying degrees. The Kiwi outperforms, followed closely by the Loonie. The EUR is flat, and is the mild underperformer this morning.
USD is under very mild pressure this morning, but has found some strength as it trades in a 101.74 to 101.98 range; the low of the day coincides with its 21-DMA. There is no specific driver for the pressure this morning, but perhaps as AI-concerns remain front of mind, particularly as the swap on CoreWeave CDS remains elevated beyond 1,000 points. With the data docket fairly light for the remainder of the week, and the Fed on blackout, markets will have to use geopolitical developments and/or tech earnings as a proxy for sentiment. Bar any debt-related concerns, the index should remain within familiar ranges into the FOMC next week.
Kiwi is the mild outperformer this morning, benefiting from slightly firmer copper prices. The Loonie has been lifted in the past few days amidst a recent hawkish repricing at the BoC; as it stands, money markets assign a c. 80% chance of a hike next week (vs c. 40% last week). To remind, BoC Governor Macklem recently stated that higher energy prices are lifting the inflation outlook, signalling that the Bank stands ready to raise rates.
The GBP benefits from a better-than-expected UK Jobs report. In brief, the Unemployment Rate fell to 4.7% vs expectations of it holding steady at 4.9%; Employment Change also jumped from the prior, and above consensus. As for the wage components, they remain benign, with little evidence of second-round effects filtering through so far. Overall, this report will provide confidence to the more hawkish members on the MPC, to deliver a rate hike in November. Following the data, Cable rose from 1.3328 to 1.3358, and currently holds at the upper end of the day’s 1.3302-1.3358 range.
EUR is flat vs the USD, and the only G10 currency failing to benefit from the softer Dollar. Pressure that stems from the ongoing widening of the OAT-Bund spread, which has now breached its recent peak of 151bps; a move which comes amidst ongoing civil unrest in France, and now several parts of Europe. Adding to the negative sentiment is a poor German/EZ ZEW Sentiment read, which fell from the prior and by more than expected.
FIXED INCOME
A contained start for fixed generally, USTs in a thin 105-05 to 105-12+ band, into a much busier docket than Monday, but one that is still generally awaiting events over the next few weeks; barring a significant geopolitical development, of course.
Currently, this leaves USTs entirely within Monday’s confines, by just a tick at the low-end and 12+ at the upper-end. Yields lower across the curve, though only marginally and with no overt flattening/steepening bias currently seen.
EGBs tracked USTs overnight, with a modest haven bid coming from the tepid APAC risk tone, but offset by energy upside, points that left the space near-enough flat in early trade. Thereafter, a hawkish UK job series pushed Bunds down by about five ticks, before this unwound and a 121.39 peak printed in the early morning.
Specifics for the bloc thus far a little light, we mainly await updates on the fiscal front, as Politico suggests that German Chancellor Merz and French President Macron are more aligned on the need to get the next framework done by end-2026. Albeit, the immediate focus is on the weekend’s unrest, with French curfews approved more widely, though the litmus test will be the coming weekend’s planned action; and then the demonstrations unions are calling for in early-November.
Reflecting the ongoing French political, and by extension, fiscal risk, the OAT-Bund 10yr yield spread has widened to a 151bps peak today, swiftly approaching the 152bps high from just after the draft budget was presented. Again, such widening does not bode well into Moody’s on Friday.
Finally, Gilts opened with some modest downside, but didn’t stray too far from the 84.00 handle. Thereafter, some slight choppiness was seen in 83.85 to 84.13 confines amid a number of factors being digested at once; since, it has slipped into the red and marginally lags.
Pressure that comes on the energy upside and hawkish jobs data, the latter being another factor in favour of a BoE hike in November, or at the very least by end-2026. Elsewhere, the discussed risk tone would have had a modest offsetting influence. While reports around the budget could be taken either way. Specifically, The Times reported that Chancellor Healey has abandoned plans to increase Capital Gains Tax, due to the likely growth hit. A point that reduces his revenue-raising avenues, and this means a lower headroom is likely to result; however, it factors well for confidence levels in domestic business.
Germany sells EUR 0.992bln vs Exp. EUR 1bln 2.10% 2029 Green Bobl and 1.80% 2053 Green Bund.
The UK sells GBP 4.25bln 4.875% 2036 Gilt: 3.61x (prev. 3.34x), Average Yield 5.418% (prev. 5.383%), Tail 0.2bps (prev. 0.5bps).
Japan sells JPY 700bln 20yr JGB; b/c 5.84x (prev. 4.01x). average yield 3.7230% (prev. 3.8560%), tail 0.07 (prev. 0.15).
COMMODITIES
Crude benchmarks have been choppy at the start of Tuesday’s European session, but ultimately reside at the top end of their daily range. WTI briefly tops USD 100/bbl (USD 98.04-100.93/bbl) while Brent holds above USD 110/bbl (USD 109.00-USD 111.75/bbl).
Geopolitical headlines have been light thus far. Overnight, the IRGC said it downed a US MQ-9 drone over Hormuz. Elsewhere, Saudi Arabia and Houthis continue to strike each other, with reports this morning suggesting that Saudi intercepted missiles heading towards Riyadh.
As for the path to diplomacy, Pakistan’s Army Chief has arrived in Tehran, so focus will be on any updates following these talks. Recent comments from Iranian officials have suggested that he is yet to arrive in Tehran. This morning there were some updates from the Iranian Foreign Ministry spokesman who struck a conciliatory tone, but ultimately did not spur a reaction in the crude complex. He mentioned that Iran held several contacts and consultations, adding that if there is even the slightest chance that it may be able to prevent the escalation of tensions through diplomacy, it must definitely go this route. However, sticking points in negotiations remain on the Strait of Hormuz and nuclear issues.
Dutch TTF is back on the climb, and currently sits at the upper end of its EUR 87.60-89.80/MWh range, with the peak just above Monday’s peak of EUR 89.70/MWh.
Precious metals continue to gradually fall, with spot gold at the lower end of its USD 4116-4147/oz range, but remains well-contained within the wider USD 4067-4228/oz band. The yellow metal will continue to be driven by yields. The next level on the US 10yr that could spur upside in the precious metal is back below the 5% level.
3M LME Copper briefly slipped below USD 14.3k/t, falling to a trough of USD 14.27k/t before rebounding to a current peak of USD 14.41k/t. Traders highlight the risk of tariffs as a downside risk for the red metal. The metal benefited from the surge of copper being piled in the US, in anticipation of tariffs being placed on copper imports. However, this possibility is fading somewhat, according to a trader at Ningbo.
IEA Chief Birol said they will consider releasing more emergency stocks if needed.
US Energy Secretary Wright said no Russian Diesel has been released yet and yet to be seen if Russia will release diesel.
Saudi and the UAE have committed to provide 95k and 100k tonnes per month, respectively, of diesel to France. Deliveries to begin in the coming weeks.
TRADE/TARIFFS
The UK Treasury is expected to be asked to assess the economic benefits of closer ties with the EU, including a potential customs union, single market return or full EU membership, ahead of the November 20th Brussels summit, according to the FT.
NOTABLE EUROPEAN HEADLINES
UK Chancellor Healey has reportedly ruled out raising capital gains tax in the October 28th Budget amid concerns over growth and investment, The Times reported. The Chancellor reportedly plans to increase taxes on banks, introduce targeted cost-of-living support and reduce fiscal headroom from GBP 23bln to around GBP 15bln in the October 28th Budget.
French President Macron and German Chancellor Merz got behind agreeing an EU budget before end-2026, Politico reported citing officials. However, a German source said no landing zones of specific numbers have been agreed.
German Chancellor Merz said they aim to quadruple AI compute capacity by 2030 with its data centre strategy. Following this, Amazon (AMZN) announced plans to invest EUR 16bln in Germany in 2027, pledging to build more sustainable infrastructure across Germany and to strengthen water-resource management.
US President Trump urged European countries to close their borders and deport migrants.
NOTABLE EUROPEAN DATA RECAP
UK Unemployment Rate (Aug) 4.7% vs. Exp. 4.9% (Prev. 4.9%).
UK Employment Change (Aug) 102K vs. Exp. 20K (Prev. 67K).
UK Claimant Count Change (Sep) 30.3K vs. Exp. 19.4K (Prev. 7.0K).
UK HMRC Payrolls Change (Sep) 13K (Prev. 1K).
UK Average Earnings excl. Bonus (Aug 3MYr) 3.7% vs. Exp. 3.6% (Prev. 3.6%).
UK Average Earnings incl. Bonus (Aug 3MYr) 3.7% vs. Exp. 3.8% (Prev. 3.9%).
European ZEW Economic Sentiment Index (Oct) 18.5 vs. Exp. 23.6 (Prev. 25.8).
German ZEW Economic Sentiment Index (Oct) 28.1 vs. Exp. 30 (Prev. 34.7).
German ZEW Current Conditions (Oct) -35.9 vs. Exp. -45 (Prev. -47.1).
German PPI (Sep MM) 1.9% vs. Exp. 0.8% (Prev. 1.1%).
German PPI (Sep YY) 6.7% (Prev. 4.6%).
CENTRAL BANKS
The BoJ is reportedly likely to keep rates unchanged in October, but could signal that a rate hike could come in December, according to Reuters sources. The report added that the Bank may also raise its FY27 inflation forecast slightly.
NOTABLE US HEADLINES
US President Trump posted that American incomes have reached record highs, employment and exports are at all-time highs, and the US is now the “hottest” country in the world.
ByteDance, Alibaba (BABA) and Tencent (0700 HK) have reportedly ordered in excess of 3mln NVIDIA (NVDA) RTX Pro 5500 workstation GPUs, with a combined value of more than USD 35bln, sources suggested.
GEOPOLITICS
MIDDLE EAST
US President Trump criticised Europe for failing to support the US over Iran and suggested Washington could reconsider its support for Europe.
Iran’s IRGC said it intercepted and destroyed a US MQ-9 drone over the Strait of Hormuz using its new advanced air defence system.
Iranian Foreign Ministry Spokesperson Baghaei said they have held several contacts and consultations and that if there is even the slightest chance that it may be able to prevent the escalation of tensions through diplomacy, they must definitely go this route. On talks with Russia, Baghaei said there was no discussion about nuclear negotiations with the US, and that Iran are not negotiating with the US in this regard.
Iranian Foreign Ministry said the US’ response to the proposal from Iran was incomplete and insufficient.
Iranian President Pezeshkian said US bases in the region provide no benefits and only fuel insecurity, Press TV reported.
Iranian Foreign Minister Araghchi said Iran-Russia cooperation is closer than ever, with talks covering regional developments and expanding economic and nuclear cooperation, IRNA reported.
Qatari Foreign Ministry spokesperson said “We are working with Washington and Tehran in partnership with other mediating countries to end the war in the region.”
Pakistan Army Chief Munir has arrived in Tehran to meet with senior officials of Iran.
Russian Foreign Minister met Iran’s President and Supreme National Security Council Secretary in Tehran, following earlier talks with his Iranian counterpart, Iran Nuances reported.
An explosion was reportedly heard in Iran’s southern city of Bandar Abbas, Sabereen News reported.
Yemeni forces reportedly targeted Saudi Arabia’s Dammam airport with missiles and drones, temporarily suspending operations, Tasnim reported, citing Al-Masirah.
Israeli PM Netanyahu said there are indications that Iran and its proxies want to challenge Israel before the elections.
US War Secretary Hegseth met Israeli PM Netanyahu during an unannounced visit to Israel on Monday, Axios reported.
RUSSIA-UKRAINE
US President Trump’s envoys Kushner and Witkoff plan to travel to Norway this week for Ukraine talks and Ukraine President Zelensky is expected to join talks.
Ukrainian President Zelensky said he talked with US Secretary of State Rubio on the topics of ballistic interceptors and Starlinks. He later said that Ukraine supports a mutual energy ceasefire.
Ukraine’s DTEK said a Russian attack struck three of its energy facilities in the Odessa region.
The Trump administration has delayed approving transfers of Patriot interceptor missiles to Ukraine from partner countries, Washington Post reported.
CRYPTO
Bitcoin has been choppy, briefly topping USD 82k before returning to its session low of USD 81.1k.
APAC TRADE
APAC stocks were mostly lower despite the rebound on Wall Street, as the region failed to sustain the AI-led recovery, with chip-heavy markets in South Korea and Japan underperforming but macro newsflow rather light.
ASX 200 declined, with gold miners pressured following Monday’s pullback in the precious metal, while financials were in focus after S&P downgraded Bank of Queensland’s long-term rating to BBB+ from A-, and Westpac flagged an AUD 41mln notable item related to RAMS litigation.
Nikkei 225 was subdued as tech names failed to benefit from the AI-led rebound stateside, although the index pared some of its earlier losses of over 1%. SoftBank was in focus following reports that it is in discussions to participate in OpenAI’s private funding round ahead of Anthropic’s IPO.
KOSPI was the regional laggard, extending its October rout, with Samsung Electronics and SK Hynix pressured amid reports that US big tech firms are pushing for lower memory prices by citing Chinese suppliers as alternatives.
Hang Seng and Shanghai Comp diverged, with Hong Kong lower as it returned from Monday’s Chung Yeung holiday, while the mainland was flat as Chinese LPRs were maintained, as expected.
NOTABLE ASIA-PAC HEADLINES
Japanese Finance Minister Katayama said no decisions have been made on funding defence spending increases, but measures to secure stable funding will be considered while maintaining fiscal sustainability.
China’s NDRC said it will introduce additional policy measures as needed to keep economic activity within a reasonable range.
NOTABLE APAC DATA RECAP
Chinese Loan Prime Rate 1Y (Oct) 3.0% vs. Exp. 3.0% (Prev. 3.0%).
Chinese Loan Prime Rate 5Y (Oct) 3.5% vs. Exp. 3.5% (Prev. 3.5%).
APAC stocks were mostly lower, and European bourses set for a negative cash market open; DXY mildly pressured – Newsquawk EU Market Open
Tuesday, Oct 20, 2026 – 01:39 AM
Iran’s IRGC destroyed a US MQ-9 drone over the Strait of Hormuz; separately, Sabereen reported that explosions were heard in Bandar Abbas, though details were light.
Crude benchmarks are mildly firmer amidst the tense geopolitical environment; the Pakistani Army Chief is set to arrive in Tehran today.
APAC stocks were mostly lower; European equity futures are set for a lower open.
G10s are mildly firmer against the softer USD; the Kiwi marginally leads.
Fixed benchmarks are mixed; JGBs soar following a stellar 20-year auction.
Looking ahead, highlights include German PPI (Sep), UK Unemployment Rate (Aug), EU/German ZEW Survey (Oct), US Building Permits (Sep), NBH Policy Announcement. Speakers include BoE’s Greene & RBA’s Hauser, Supply from the UK & Germany. Earnings from EssilorLuxottica, ABB, GE Aerospace, General Motors, RTX, Northrop Grumman, Netflix & United Airlines.
SNAPSHOT
Highlights include German PPI (Sep), UK Unemployment Rate (Aug), EU/German ZEW Survey (Oct), US Building Permits (Sep), NBH Policy Announcement. Speakers include BoE’s Greene & RBA’s Hauser, Supply from Japan, UK & Germany. Earnings from EssilorLuxottica, ABB, GE Aerospace, General Motors, RTX, Northrop Grumman, Netflix & United Airlines.
US stocks rebounded to start the week as AI concerns eased over the weekend, although breadth was poor outside of AI names. Hyperscaler and mega-cap names drove gains within Tech and Consumer Discretionary (AMZN +5%, named a top pick at MS), while Utilities, Real Estate and Financials lagged (RSP -0.2% vs. SPX +0.6%). In the final hour, Bloomberg reported that Nscale is in talks with Anthropic for a USD 45bln cloud computing deal, which lifted neocloud names, although CoreWeave finished 0.4% lower despite positive sell-side commentary.
SPX +0.63% at 7,708, NDX +1.17% at 29,529, DJI +0.07% at 52,041, RUT +0.37% at 2,731.
US President Trump posted that American incomes have reached record highs, employment and exports are at all-time highs, and the US is now the “hottest” country in the world.
APAC TRADE
EQUITIES
APAC stocks were mostly lower despite the rebound on Wall Street, as the region failed to sustain the AI-led recovery, with chip-heavy markets in South Korea and Japan underperforming but macro newsflow rather light.
ASX 200 declined, with gold miners pressured following Monday’s pullback in the precious metal, while financials were in focus after S&P downgraded Bank of Queensland’s long-term rating to BBB+ from A-, and Westpac flagged an AUD 41mln notable item related to RAMS litigation.
Nikkei 225 was subdued as tech names failed to benefit from the AI-led rebound stateside, although the index pared some of its earlier losses of over 1%. SoftBank was in focus following reports that it is in discussions to participate in OpenAI’s private funding round ahead of Anthropic’s IPO.
KOSPI was the regional laggard, extending its October rout, with Samsung Electronics and SK Hynix pressured amid reports that US big tech firms are pushing for lower memory prices by citing Chinese suppliers as alternatives.
Hang Seng and Shanghai Comp diverged, with Hong Kong lower as it returned from Monday’s Chung Yeung holiday, while the mainland was flat as Chinese LPRs were maintained, as expected.
US equity futures were modestly firmer, with ES and YM edging higher following Monday’s AI-led gains, while NQ was little changed.
European equity futures indicate a negative cash market open, with Euro Stoxx 50 futures down 0.5% after the cash market closed with losses of 0.9% on Monday.
FX
DXY drifted lower to fresh APAC session lows beneath 101.90 despite a lack of fresh newsflow, as G10 peers edged to session highs. There is no tier-1 US data scheduled this week and the Fed is in its blackout period ahead of next week’s meeting, leaving geopolitics and the AI trade as the main drivers.
EUR/USD edged higher within a 1.1211-1.1230 range, benefiting from the softer dollar, though remains close to the 1.1200 handle after the single currency underperformed on Monday amid civil unrest in France and other European cities. Focus is also on Moody’s review of France on Friday.
GBP/USD was firmer and reclaimed the 1.3300 handle to trade in a 1.3304-1.3330 range, with attention on UK unemployment data later today. The Times reported that Chancellor Healey has ruled out raising capital gains tax in the 28th October Budget.
USD/JPY was marginally lower within a 158.36-158.60 range, with markets on watch for potential jawboning as the pair holds above 158.00. Japanese Finance Minister Katayama said no decisions have been made on funding defence spending increases, while Economy Minister Kiuchi said he hopes to attend this month’s BoJ policy meeting.
Antipodeans edged higher alongside G10 peers amid the softer dollar.
PBoC set USD/CNY midpoint at 6.7200 vs exp. 6.6813 (prev. 6.7208).
FIXED INCOME
10yr UST futures were little changed within a 105-05 to 105-09+ range, following Monday’s decline as the easing of AI concerns prompted a return of the Treasury sell-off, alongside gains in front-month crude futures on unconfirmed Houthi attacks on Saudi oil facilities.
Bund futures were marginally firmer in quiet overnight trade within a 121.07-121.23 range, following Monday’s pressure across European fixed income amid the civil unrest in France, which saw the OAT-Bund 10yr spread widen to around 145bps ahead of Moody’s review on Friday. German PPI and the ZEW survey are due later.
10yr JGB futures reversed earlier losses to trade flat amid a strong 20yr JGB auction which saw the strongest demand for the line on record.
Japan sold JPY 700bln 20yr JGB; b/c 5.84x (prev. 4.01x), average yield 3.7230% (prev. 3.8560%), tail 0.07 (prev. 0.15).
COMMODITIES
Crude futures were modestly firmer, with WTI Dec just under USD 99.00/bbl (98.04-99.00 range) and Brent Dec around USD 110.00/bbl (109.00-110.17 range), supported by continued geopolitics, as the IRGC said it intercepted and destroyed a US MQ-9 drone over the Strait of Hormuz, an explosion was reportedly heard in Bandar Abbas, and Yemeni forces reportedly targeted Saudi Arabia’s Dammam airport. Meanwhile, Pakistani Army Chief Munir is due to arrive in Tehran today.
Spot gold was modestly firmer around USD 4,150/oz, recovering from an earlier low of USD 4,116/oz as the dollar softened; spot silver outperformed with gains of 0.7%.
Copper futures were marginally firmer but then succumbed to selling pressure, with 3M LME copper around USD 14,325/t.
US Energy Secretary Wright said no Russian Diesel has been released yet and yet to be seen if Russia will release diesel.
Ukrainian President Zelensky said Ukraine could stop striking Russian refineries in return for the US helping with patriot missiles for this period; Decisions taken by the US side are “hard to explain”.
US Energy Secretary Wright said talks with the UK on diesel stock releases are continuing; The US is converting sanctioned tankers to legitimate tankers. Dozens to hundreds of dark tankers could be converted.
CRYPTO
Bitcoin was slightly lower around USD 81,800, with price action contained in quiet overnight trade.
CENTRAL BANKS
Japan’s Economy Minister Kiuchi said he hopes to attend this month’s BoJ policy meeting if his schedule allows.
PBoC will conduct overnight reverse repos from October 21st to November 2nd via fixed-rate, quantity-based tenders, capped at CNY 1tln daily, and will include foreign-invested RMB settlement banks among eligible counterparties.
Chinese Loan Prime Rate 5Y (Oct) 3.5% vs. Exp. 3.5% (Prev. 3.5%).
Chinese Loan Prime Rate 1Y (Oct) 3.0% vs. Exp. 3.0% (Prev. 3.0%).
NOTABLE ASIA-PAC HEADLINES
China’s NDRC said it will introduce additional policy measures as needed to keep economic activity within a reasonable range.
Japanese Finance Minister Katayama said no decisions have been made on funding defence spending increases, but measures to secure stable funding will be considered while maintaining fiscal sustainability.
GEOPOLITICS
RUSSIA-UKRAINE
Trump administration has delayed approving transfers of Patriot interceptor missiles to Ukraine from partner countries, Washington Post reported.
US President Trump’s envoys Kushner and Witkoff plan to travel to Norway this week for Ukraine talks and Ukraine President Zelensky is expected to join talks.
MIDDLE EAST
Iran’s IRGC said it intercepted and destroyed a US MQ-9 drone over the Strait of Hormuz using its new advanced air defence system.
An explosion was reportedly heard in Iran’s southern city of Bandar Abbas, Sabereen News reported [Details light].
US President Trump urged European countries to close their borders and deport migrants; Trump criticised Europe for failing to support the US over Iran and suggested Washington could reconsider its support for Europe, via Truth Social.
Iranian President Pezeshkian said US bases in the region provide no benefits and only fuel insecurity, Press TV reported.
Two Pakistani soldiers were reportedly killed in the Wadi al-Miftah area near the Saudi-Yemeni border, IRNA reported, citing Yemeni media.
US War Secretary Hegseth met Israeli PM Netanyahu during an unannounced visit to Israel on Monday, Axios reported.
Yemeni forces reportedly targeted Saudi Arabia’s Dammam airport with missiles and drones, temporarily suspending operations, Tasnim reported, citing Al-Masirah.
Russian Foreign Minister met Iran’s President and Supreme National Security Council Secretary in Tehran, following earlier talks with his Iranian counterpart, Iran Nuances reported.
US President Trump said good situation with respect to Iran; negotiating with Russian President Putin on Ukraine; negotiating on Iran and with diesel with Russia; Russia has been fine on Ukraine. Ukraine’s President Zelensky is not helping matters much. Time for someone else to negotiate on behalf of Ukraine.
IRGC spokesperson said 7 major cables have passed under the Strait of Hormuz, on which all the world’s internet and commercial data depends; we remind the enemy of this so that they know.
US Official said Iran’s claim that the US struck an Iranian naval base is inaccurate, reported CNN.
Houthis target Marib city with ballistic missiles, reported Sky News Arabia.
Iranian President Pezeshkian said Iran has no fundamental differences with regional countries and is ready to resolve existing issues through dialogue.
Pakistani Army Chief Asim Munir arrives in Tehran today (20th Oct) to meet with Iranian officials, Al Jazeera reported.
The operation to neutralize and destroy unexploded ordnance left over from the imposed war has begun in the north of Bandar Abbas and, according to Hormozgan officials, Nour News reported; will continue for the next two days.
IRGC Spokesperson: In the new phase of the war, new weapons and targets will be unveiled, Fars reported.
Houthis claim six attacks on Saudi Arabia in 48 hours; strikes include Yanbu Aramco facility, Shaybah oilfield, Riyadh and Abha airports.
Iranian Foreign Minister Araghchi said Iran-Russia cooperation is closer than ever, with talks covering regional developments and expanding economic and nuclear cooperation, IRNA reported.
EU/UK
NOTABLE HEADLINES
UK Chancellor Healey has reportedly ruled out raising capital gains tax in the October 28th Budget amid concerns over growth and investment, The Times reported. The Chancellor reportedly plans to increase taxes on banks, introduce targeted cost-of-living support and reduce fiscal headroom from GBP 23bln to around GBP 15bln in the October 28th Budget.
Germany Chancellor Merz said Germany needs to overhaul social security system; No need for a fast decision on ECB positions, but a quick decision can be reached on ECB jobs if needed. Nvidia (NVDA) plans to invest “billions” in Germany.
US State Department approved a potential sale of general infrared countermeasure systems to the Netherlands.
NOTABLE GLOBAL EQUITY HEADLINES
OpenAI is reportedly rushing to secure investor commitments for a private funding round ahead of Anthropic’s IPO, with SoftBank (9984 JT) and MGX in discussions to participate, according to sources.
2.NORTH AND SOUTH KOREA/
NORTH KOREA
SOUTH KOREA/USA
THIS SAYS A MOUTHFUL ON TECH!!
Another Day, Another Data Center Faceplant: Korea’s Biggest IPO Of The Year Craters 32% Within Seconds
Monday, Oct 19, 2026 – 09:22 PM
Another day, another data center faceplant.
This time the venue is Seoul, where data-center infrastructure company Elice (0158S0 KS) plunged in its trading debut on South Korea’s tech-heavy Kosdaq after raising 201 billion won ($151 million) in the bourse’s biggest (and probably worst) initial public offering of the year. According to Bloomberg, the self-described “neocloud” priced at 90,500 won, the top of its marketed range, for a post-listing market cap of just over 1 trillion won (roughly $750 million). Shares then fell as much as 32% instantly to 61,400 won in early trading on Tuesday, after a brief opening pop to around 78,000 won which, for those keeping score, was itself still 14% below the offer price.
At last check the stock was hovering around 62,900 won, or about 30% below where the IPO priced, wiping out roughly 300 billion won of paper value in under half an hour.
Bloomberg politely frames the debut as “a test of investor appetite for the sector after a series of setbacks around the world.”
Well, consider it tested. Regular readers know we have been keeping a running tally of these now daily faceplants since Firmus slashed and then pulled its ASX float on Oct 8, and we have been warning since last October that the AI buildout was running on borrowed money. What Elice adds to the story is a new and rather uncomfortable data point: even the cheap, profitable one can’t trade.
400x Oversubscribed, 32% Underwater
The demand was certainly there… on paper… according to the underwriters… who would never lie… right? Korean retail investors poured roughly 10.3 trillion won (about $7.7 billion) into subscription deposits for a shot at the shares, with the retail book oversubscribed more than 400 times (or so they claim). Put differently, mom-and-pop Seoul parked about 51 times the size of the entire deal in escrow to get an allocation. Then they got one.
Some context on just how fast it went wrong: under Korea’s IPO rules, a stock can trade anywhere between 60% and 400% of the offer price on day one. Elice’s floor was therefore 54,300 won. At the low, it was about 13% above the floor and 83% below the ceiling, which is probably not how the subscription ads pitched it.
None of this should shock anyone who has watched Korean flows this month. When the KOSPI tripped circuit breakers on Oct 15 for the first time since July (in its 7th straight down day), Goldman’s Korea desk reported that foreigners dumped $2.7 billion of stock while Korean retail bought about $1 billion of it, as we noted in “Goldman: Demand For Compute Can Grow Exponentially, But The Capital To Finance It Cannot.” Institutions selling, retail buying. Today the retail crowd just got to do it at the IPO price instead of the secondary market. Not that the volatility is anything new for what we have long called…
And it’s not like the official bid has been there to catch anything: as we warned earlier this month, the KOSPI’s only buyer had left the building (Oct 7). Overnight, Goldman’s Seoul desk flagged in its Korea Open note (available to pro subs) that President Lee now says a correction “was inevitable after its rapid ascent,” while insisting that domestic stocks “remain undervalued.” Elice’s new shareholders would probably agree with at least half of that sentence.
The Cheap One Still Puked
Here’s what makes the Elice debut more interesting than just another frothy deal getting its comeuppance. Unlike pretty much all of its peers, Elice actually makes money. Per its prospectus, first-half revenue surged 200% to 34.4 billion won, the company swung to an operating profit of 10.3 billion won, and EBITDA jumped more than 11-fold to 23.2 billion won. Smartkarma’s Douglas Kim expects an 83% sales jump in 2026 and an operating margin of about 33%.
Do the math and the IPO valued the company at about 14.5x annualized revenue, falling to roughly 10x moments after actually opening for trading on Tuesday. Compare that to Nscale, which, as we detailed on Sunday, was asking public investors for $30 billion, or about 107x sales, while losing $1.02 billion in the first half. Even the “realistic” $16-19 billion range Nscale’s would-be buyers are floating works out to some 57-68x.
Which is why the local fund managers quoted by Bloomberg sound a bit bewildered. Zian Investment Management CEO Kim Dojoon argued that “investor sentiment may have weakened due to CoreWeave, but its financial structure is quite different from CoreWeave so I don’t think investors need to view the company as particularly risky.” Petra Capital’s Albert Yong added that sentiment toward AI infrastructure has been “highly volatile and often disconnected from underlying fundamentals.”
“I think the market is discovering that demand for compute can grow exponentially, but the capital available to finance it cannot. I’ve learned to respect the credit market, and the widening across the AI vertical is a warning.”
In other words, the question now is how much capital a neocloud will need tomorrow and at what price – in other words, who is the greatest fool (that would be life insurers according to the CoreWeave founder) – and today’s multiple says very little about that. And Elice’s CEO Jae Won Kim was refreshingly candid on that front: the IPO proceeds go toward building more AI data centers in Korea and abroad. “We’re going all-in on becoming a full-stack AI infrastructure leader globally,” Kim told Bloomberg. “This IPO is about giving ourselves the financial firepower to execute.“
That is precisely the business model Privorotsky warned about: an equilibrium that “increasingly favors those with powered capacity and strong balance sheets over the leveraged middlemen.” Or as he put it, “Perhaps this was always how crowding out would manifest itself… through the marginal borrower.“
Or in this case marginal momentum-chasing sucker, which South Korea has plenty of.
And Korea is hardly the place where capital is getting cheaper. Goldman’s economists expect the Bank of Korea to deliver a “hawkish hold” this week after back-to-back hikes in Q3, with another 25bp hike most likely in Q1 2027. Meanwhile power, the other input every data center needs, is about to get pricier: state utility KEPCO, sitting on 210 trillion won (c. $148 billion) of debt, wants to open talks on raising electricity tariffs, per the same Goldman Korea Open note. Higher rates plus higher power bills, for a company whose pitch is “high-density power systems” for AI chip clusters. (Yet another reason we keep saying behind-the-meter generation should be mandatory for these projects.)
The Casualty List Grows Faster Than The Data Centers
Elice is just the latest name on a list that is getting long enough to need its own table of contents. In roughly four weeks:
SB Energy: SoftBank’s unit delayed the IPO meant to fund the world’s largest data center (Sep 22).
Firmus: the Nvidia-backed Australian operator cut its IPO price by 25%, then pulled it (Oct 8), after asking for A$43.7 billion, nearly 3x its August private mark, on the back of a valuation metric best described as creative.
AirTrunk / Vitro: Blackstone’s AirTrunk pushed its $1.5 billion Singapore REIT to 2027 (Oct 14) even after sweetening the yield to 6%, while PLDT’s Vitro deferred its own data center REIT.
CoreWeave: shares have more than halved since their May peak, and its bonds traded into distressed territory last week, with CDS implying roughly 63% odds of default within five years.
Here is the full scorecard, now with a Korean entry:
Our verdict on the Firmus fiasco at the time still applies:
Then there’s Gartner, which last week predicted that by 2030 “cost pressure and a lack of a differentiating business model will force over 80% of neocloud providers to cease independent operations,” with AI data center owners needing a cumulative $8.5 trillion in revenue through 2030 against no more than $3.6 trillion that can actually be attributed to them. Elice just volunteered for the stress test.
Meanwhile, Over At Goldman…
The timing of all this is, well, exquisite. On Monday morning, roughly 12 hours before Elice opened for trading, Goldman’s Gabriela Borges upgraded CoreWeave to Buy, while cutting her price target to $106 from $139. Her reasoning, per the bank’s “CoreWeave – Contract Economics Datapoints to Outperform” note (also available to pro subs):
“We think investors are currently overestimating upward revisions to WACC and underestimating unlevered IRR; despite raising our blended debt cost assumption to 1,000bps, we expect the company to successfully finance its expansion through asset-backed delayed draw term loans.”
Read that again: the bull case now explicitly assumes the company borrows at around 10%, and Borges thinks new long-term contracts can “comfortably clear a 15% unlevered IRR” because she sees AI compute supply-demand constraints persisting “for at least the next 24 months.” No wonder the market made an immediate mockery of her ridiculous analysis, with CRWV stock kneejerking higher only to close near the Friday lows.
To be fair, nobody really disputes the demand (well, some do). The question is the funding, and on that front Morgan Stanley offered a far less cheerful view in its latest AI capex work, which we highlighted on Sunday: combined hyperscaler and neocloud free cash flow hits its most negative point in 2027, with the hole just shy of $600 billion once lease payments are included.
Translation: the year with the biggest capex bill is also the year with the biggest funding gap, and every dollar of it has to come from somewhere. The public equity market, judging by Firmus, AirTrunk, Nscale and now Elice, is increasingly unwilling to be that somewhere, at least at the prices sponsors want. That leaves debt, and that window is rapidly closing too.
Firepower, Meet The Cost Of Capital
“This IPO is about giving ourselves the financial firepower to execute,” Elice’s CEO said. And to be fair, he got the firepower: the 201 billion won is in the bank regardless of where the stock trades. The bill went to Korean retail, which handed over $7.7 billion in deposits for the privilege of buying a profitable, reasonably priced neocloud at the exact moment the market decided it doesn’t want to own neoclouds at any price.
Which brings us to what Elice really tells us. Firmus could be dismissed as a frothy outlier with a made-up multiple, and Nscale as a 107x-sales loss machine. Elice was neither, and it still lost a third of its value before most of Seoul had finished its first coffee. The problem, then, is the asset class and the cost of the capital needed to keep building it, and with global rates at their highest since 2007 (per Goldman’s economists) and Korea’s central bank still leaning hawkish, that cost is not coming down any time soon. Goldman can raise its debt cost assumption to 1,000bps and still call it a Buy; the public market, apparently, would rather not be the one lending at those rates.
Next up: DayOne, Firmus’ partner in Batam, which still wants to raise up to $5 billion in a US listing and could start marketing as soon as Wednesday. We’ll check back then… if the deal is still on.
DeepSeek Is Now Designing Huawei’s AI Chips… Just As DHS Orders It Ripped Out Of Federal Systems
by Tyler Durden
Monday, Oct 19, 2026 – 11:00 PM
Two DeepSeek headlines landed within hours of each other on Monday, and read side by side they tell you pretty much everything about where the US-China AI race is heading: two separate stacks, built by two separate camps, with less and less overlap every month.
Let’s start in Hangzhou. According to The Information, DeepSeek has gone well beyond being a Huawei customer and is now effectively a co-designer of Huawei’s next-gen silicon. Huawei engineers have reportedly been stationed at DeepSeek’s offices for an extended period, folding the AI lab’s requests and suggestions directly into chip design decisions. In return, Huawei plans to hand DeepSeek most of the supply of its Ascend 960DT training chip when it launches next year. And on the software side, both companies have been using the open-source programming language TileLang as an alternative to Nvidia’s CUDA, with DeepSeek’s models now largely handled by TileLang running on Huawei chips.
None of this should come as a surprise. Back in September, when DeepSeek said it aimed to deploy over 160,000 Huawei AI chips, we wrote that DeepSeek’s 160,000 Huawei Order Is A Real Threat To Nvidia In 2027. A few weeks later, on Sept 30, DeepSeek open-sourced an Ascend port of TileLang along with Ascend versions of its DeepGEMM and DeepEP libraries, explicitly crediting Huawei and touting a jointly optimized 128-chip Ascend 950 “supernode.” Meanwhile Huawei pulled the launch of the Ascend 960DT forward to the first quarter of 2027, three quarters ahead of schedule.
What’s new in Monday’s report is the depth of the co-design. Nvidia spent two decades building its moat by tuning hardware and CUDA in lockstep with its biggest customers; China is now attempting the same trick with the lab and the chipmaker sitting, quite literally, in the same building. TileLang is still early and nobody serious thinks Ascend matches Blackwell (let alone Rubin) chip-for-chip, but the trajectory matters more than the snapshot. Which brings us back to a question we asked in August, and which nobody in Washington seems to have answered yet:
The US response arrived the same morning, and it was, well, a procurement notice. The Department of Homeland Security published an order directing federal civilian agencies to remove DeepSeek products, and any third-party services built on the Chinese model, from their IT systems,and banned agencies from acquiring them going forward.
A few details worth flagging:
The order (Exclusion and Removal Order #2026-01) was issued under the 2018 Federal Acquisition Supply Chain Security Act and was actually signed back on July 24; it only became public Monday via a Federal Register filing. So agencies have presumably been quietly scrubbing DeepSeek for three months already.
It covers civilian executive branch agencies such as Treasury, State and Justice. The Pentagon and the intel community are carved out, mostly because the Pentagon already banned DeepSeek and High-Flyer AI via the FY2026 NDAA.
DHS argues DeepSeek’s models pose “multiple threat vectors” and that government use may result in the transfer of sensitive data to the PRC, pointing to China-based servers, PII collection at sign-up and possible user fingerprinting.
The order doesn’t lay out the underlying evidence and stops well short of an Entity List designation, so purely commercial use of DeepSeek is untouched… for now.
Step One Toward Banning All Chinese Open-Source AI?
Probably not step one… more like step four or five, and the important part is hiding in the fine print. The order reaches beyond DeepSeek’s own app to third-party products “developed using DeepSeek implementations,” which in plain English means any vendor tool built on a fine-tune or distillation of DeepSeek’s open weights. And because federal acquisition rules bind prime contractors and subcontractors to these exclusion orders, the provenance of a model’s weights has just become a procurement criterion for anyone selling software to Uncle Sam. That is a much bigger deal than banning a chatbot app nobody at the State Department was supposed to be using in the first place.
Look at the sequence so far: NASA, the Navy and roughly 17 states blocked DeepSeek on government devices in early 2025; the FY2026 NDAA booted it from the Pentagon and its contractors; now civilian agencies. And the pipeline behind it is already full:
The Senate Armed Services Committee’s version of the FY2027 defense bill would extend the Pentagon ban beyond DeepSeek to AI from ten other Chinese companies and their derivative models.
In July, after Moonshot’s Kimi K3 dropped (and sparked what we called another “DeepSeek moment” for US AI stocks), Axios reported the administration was reviving plans for de facto bans on Chinese open models, with Kimi and Alibaba’s Qwen in the crosshairs via procurement rules, Entity List threats and security advisories. Scott Bessent added a sanctions threat over distillation a day later.
And in August, The Information reported the US was mulling a self-regulatory organization for AI companies, which we flagged at the time for what it likely was:
If all of this feels familiar, it should: it’s the TikTok playbook. TikTok was banned on federal devices in December 2022; the divest-or-ban law followed in April 2024. Government devices first, everyone else later.
That said, an outright ban on Chinese open weights would be a much harder lift than TikTok. The weights are already sitting on Hugging Face and on millions of hard drives, a weights-level ban runs into obvious First Amendment problems, and a lot of US startups (and, reportedly, at least one very large software company in Redmond) have built on Chinese open models precisely because they are cheap and nearly as good. As we laid out in Answering The “Trillion Dollar Question” back in June, the cost gap is enormous. So the more likely path is the de facto one: procurement bans that widen to every Chinese lab, then to contractors, then “advisories” that let enterprise compliance departments do the rest. No law required.
Decoupling, Courtesy Of Both Sides
The irony is that Beijing may get there first. Just last week China’s commerce ministry floated export controls that would, for the first time, cover AI model weights and source code above certain performance thresholds (models trained with more than 1026 FLOPs, over 2 trillion parameters, or ranking in the global top 10), even if it promises a fast-track license for open-source releases. Chinese AI commentators immediately took it to mean the next Kimi, GLM and DeepSeek flagships may never be open-sourced at all. So the free lunch of frontier-grade Chinese open weights could end from both directions at once.
And every step Washington takes to wall off DeepSeek pushes it deeper into Huawei’s arms, which is exactly what Monday’s Information report describes. The US is cutting DeepSeek out of its government while Beijing cuts DeepSeek off from Nvidia, and the result is two fully separate AI stacks: CUDA, Nvidia and closed US frontier models on one side; TileLang, Ascend and (maybe, for a while longer) open Chinese models on the other. Jensen Huang has been warning for years that export controls would hand Huawei the Chinese market on a silver platter. Turns out they also handed it a very motivated design partner.
end
4. EUROPEAN AND SCANDINAVIAN COMMENTARIES PLUS NATO
FRANCE/
Zemmour: French Riots Show “True Face Of The Great Replacement”
French right-wing politician Éric Zemmour said Sunday that violent protests and looting the previous day revealed “the true face of the Great Replacement,” citing Palestinian, Algerian and Moroccan flags among demonstrators and alleging ties to antifascist groups and left-wing lawmakers.
During an appearance on French news network LCI, Zemmour said: “What we saw yesterday is the true face of the Great Replacement. It has an appearance: hordes of North African and African barbarians who rampage through cities.”
It has its flags: Palestinian, Algerian and Moroccan. It has its allies, Antifa militias. It has its legal backing, the LFI deputies. It has a mode of operation: looting, raids. And finally, I would say it has an ideological, historical engine: hatred of France and revenge for colonization.”
Zemmour, a former journalist and author who leads the Reconquête party, has long promoted the “Great Replacement,” which he uses to describe native European populations being demographically supplanted by non-European immigrants, particularly from Muslim-majority countries, Africa, and Asia. The topic is openly discussed in France, including among intellectuals, academics, politicians, and even Michel Houellebecq, arguably the country’s most celebrated living author.
Zemmour’s remarks referred to massive riots on Oct. 17 that occurred in French cities across the country, where protests over the cost of living and public services turned into some of the country’s most violent demonstrations in years. Videos of burning buildings, looted stores, and violent clashes with police were spread across social media.
Zemmour’s remarks came at a time when U.S. officials, including Donald Trump, have remarked on the riots as well.
“France is burning! The immigration of people from an entirely different world, people with hatred in their hearts, has shattered that once great country. Close your Borders and take control, before it is too late!” wrote Trump.
Vice President JD Vance also wrote on X: “Western liberals imported the third world into France and other countries in the name of diversity and compassion. They ignored fundamental questions of assimilation and compatibility. They were told it would lead to this and they didn’t listen.”
Zemmour, who finished fourth in the 2022 presidential election, has remained a prominent voice on immigration ahead of France’s next national vote, but his right-wing rival, Le Pen, is heavily favored to win the presidency. Zemmour typically polls around 5 percent in the first round.
END
France Slaps Curfews On Riot-Plagued Cities As Report Links Unrest To Communists
Tuesday, Oct 20, 2026 – 07:10 AM
An 11 p.m. curfew took effect in parts of the Paris metro area on Monday, along with curfew restrictions in other cities, after the Macron government embarrassingly struggled for weeks to contain far-left social unrest and chaos that had spiraled out of control. Prime Minister Sébastien Lecornu said the measures helped restore calm overnight and will put new curfews in place where needed today.
Lefty corporate media continue to push the narrative that looting luxury stores, burning government buildings, torching vehicles, and clashing with police were merely the actions of a bunch of angry kids about the deteriorating state-funded education system. That narrative has largely gone bust as globalists lose control of their role as gatekeepers of “information.”
In fact, Fox News’ Asra Nomani published a new investigation into the far-left riot ecosystem behind the French turmoil, in which her team identified:
54 organizations and movements in France’s October student protests and their wider network of supporters and international amplifiers, including communist parties, revolutionary socialist groups, labor unions, environmental activists, Muslim student advocates, Palestinian-solidarity organizations and international media outlets.
Of the 54 organizations identified in the October protest ecosystem, 16, or only about one in three, are student or youth organizations, including communist youth groups and a Muslim student association. The remaining 38 include adult-led communist groups, labor unions, political parties, revolutionary-left organizations, advocacy groups and international propaganda outlets.
In other words, some of the riot participants were part of highly coordinated far-left groups that seek to destroy the West and capitalism. The blowback has already begun as law-abiding citizens saw their cities and towns burn and mom-and-pop stores looted by radical revolutionaries. This has only provided tailwinds for National Rally leader Marine Le Pen, who is gaining in the polls ahead of next April’s presidential election. Her Polymarket odds of winning the presidential election currently stand at 46%.
Morningstar DBRS insurance analyst Marcos Alvarez said riot-related damage could reach 1.2 billion euros. Assuming violence does not escalate from here, losses should be manageable through major insurers’ earnings without threatening their capital positions, he said.
“Assuming no further violence, we expect the latest French riots to be a manageable earnings event rather than a capital event for the country’s major insurers,” Alvarez wrote in a note.
French government bonds rallied, outperforming euro-area peers today. The 10-year yield fell two basis points, narrowing the premium over German debt to 147 basis points, though the spread remained near its widest levels in weeks.
The extra yield investors demand to hold French debt comes as the Macron government faces mounting crises, including a budget deficit, a failing welfare system, unfettered mass migration, social unrest, and overall economic gloom.
France’s problem, with debt that exceeds its gross domestic product, is that in a high-rate environment, with a welfare system imploding and services degrading, throwing more money at voters in the form of handouts to keep them calm simply doesn’t work. That’s because bond investors will penalize the country with higher and higher rates – and good luck funding the progressive experiment.
And that’s the point at which France has entered the endgame. One of the driving reasons behind the riots is that the socialist agenda of promising more and more handouts simply runs into a brick wall – and really that’s why the left is rioting, because their days of free money and not working could come to an abrupt end under a Le Pen government if she wins next year.
The unrest has already spread well beyond France and is absolutely embarrassing for lefty Brussels elites who have allowed the far left to fester and radicalize kids into useful purple-haired idiots.
Meanwhile, in the US, the Trump administration’s NGO task force in the Treasury Department, along with coordination with other agencies to ensure that far-left revolutionaries don’t repeat the Marxist BLM riots of 2020, has likely been one of the main reasons there were no riots this past summer. Think about it: That’s probably because the big family foundations were put on notice that their 501(c) tax-exempt status could be stripped.
But House Speaker Mike Johnson, R-La., warned on Monday that France’s “descending into chaos” at the hands of socialist lefty radicals is a wake-up call for America: “What we are witnessing is a chilling warning for all Americans of what happens if the radical Marxist insurgent left gets their way.”
END
FRANCE
As France Burns, Media Insists It’s ‘Mostly Peaceful’; Blames Right-Wing Influencers
Historic buildings torched, thousands of shops looted, streets turned into war zones, firefighters attacked, and police overwhelmed. The official line from Macron’s government, the BBC, and the rest of the compliant media is that this is about “education reform,” teacher shortages, and the cost of living.
The footage tells a different story: organized packs of masked young men from the banlieues, waving Palestinian, Algerian, and Moroccan flags, smashing, looting, and burning while the native French clean up the mess afterward.
This is the predictable result of decades of open borders and failed assimilation. The “protesters” smashing shops and attacking police are not legitimate demonstrators seeking better classrooms. They are the product of the mass migration France allowed to flood the country.
The scale is staggering. Interior Minister Laurent Núñez reported roughly 1,800 to more than 2,400 arrests over the weekend. Nearly 1,000 police and gendarmes were injured. Over 2,000 shops were looted or damaged nationwide, with losses running into the hundreds of millions of euros.
In Limoges, the 143-year-old town hall was deliberately set ablaze; its roof collapsed. Paris deputy mayor Emmanuel Grégoire said entire streets had been “methodically ravaged.” Macron himself addressed the nation calling the violence “unbridled” and saying the country felt “anger and shame.”
The media’s response has been pure gaslighting. The BBC described the scenes of burning cars, masked looters, and street battles as “mostly peaceful.”
Sky News blamed right-wing accounts for sharing the footage rather than the people destroying the cities. The footage shows mass looting, burning barricades, and crowds with Palestinian flags, while the network frets about people sharing it online.
In more completely dystopian scenes, a CBS clip showed a couple calmly sipping drinks near the Arc de Triomphe while fires raged and rioters clashed with police just meters away.
Another captured tourists with luggage trying to navigate the chaos, complete with French text overlay reading “Yes it’s for the Airbnb, we’re in front.”
Locals keep dancing, jogging and giving tours in BURNING Paris while Macron hits a Celine Dion concert
This is not spontaneous student anger. The unrest began last month in Paris’s working-class northern suburbs – the same areas that have produced previous waves of banlieue riots. Far-left networks, communist and socialist groups, and Islamist elements have coordinated and amplified it.
Specific organizations signaled the October 17 actions in advance and are planning a major demonstration across 12 countries on November 20.
The same far-left ecosystem funding the street chaos was already active weeks ago. Prime Minister Sébastien Lecornu blamed “ultra-left” elements and criminals. Núñez called the hijackers “opportunistic delinquents who had seen a chance to pillage and loot.”
Communists, socialists, and Islamists linked to China tycoon are hijacking ‘student’ riots
Videos from the ground confirm the character of the violence. Another clip highlights rioters confronting and attacking firefighters trying to put out the fires they started.
Another clip shows locals – the actual French residents – out the next morning sweeping glass, clearing debris, and boarding up shops while the culprits are nowhere to be seen.
A separate viral video captured a woman of Algerian origin at the protests blaming “Zionists,” claiming dual-nationality voters are the majority, and urging votes for Mélenchon before joining the masked chaos.
French politician Éric Zemmour cut through the noise, urging “I believe that what we saw yesterday is the true face of the Great Replacement. It has an appearance: hordes of North African and African barbarians who ransack cities.” He pointed to the Palestinian, Algerian, and Moroccan flags, the Antifa allies, the legal cover from LFI deputies, and the ideological engine of “hatred of France and revenge for colonization.”
Donald Trump posted that immigration from “an entirely different world, people with hatred in their hearts, has shattered that once great country” and urged France to close its borders. JD Vance wrote that “Western liberals imported the third world into France and other countries in the name of diversity and compassion.”
The Louvre closed because of “student strikes.” The reality was rioters blocking access after a night of smashing and burning.
The same demographic pattern has appeared in French riots for two decades: young men of first-, second-, and third-generation migrant background from the suburbs, often coordinated with far-left groups that treat the destruction as a political weapon.
The media’s insistence on “mostly peaceful” and “education reform” is the same script they run every time the consequences of open borders become visible.
France is reaping what its leaders sowed. The native population is left sweeping up the glass while the political class offers curfews and more of the same.
END
UK//UK REMEBRANCE DAY
MUSLIMIZATION OF BRITAIN!!
Veterans Blast ‘Palestine Poppy’ As Hijacking Of Remembrance Symbol, A Week After Protesters Trampled Battle Of Britain Wreaths
Tuesday, Oct 20, 2026 – 02:45 AM
Pro-Palestinian campaigners are selling a “Palestine Poppy” in the green, red, white and black of the Palestinian flag ahead of Remembrance Sunday, and British veterans say it hijacks the country’s day of mourning for its war dead, GB News reports.
eteran outrage at Palestine Poppy ‘hijacking’ remembrance symbol | UK | News | Express.co.uk
The badge is on eBay for £1.74 each, and the Mail counts more than 1,200 sold so far. The group behind it calls the poppies “a symbol of solidarity and remembrance for the ongoing struggle of the Palestinian people and their fight for justice.” Sales are not-for-profit, with a “small donation” going to charities in Palestine and to groups seeking to end “the occupation and war crimes through legal routes.”
Retired Army officer and defense analyst Lt. Col. Stuart Crawford told GB News the badge is an attempt to “ride on the coat-tails of the familiar red poppy.”
“The Remembrance poppy is avowedly apolitical,” he said, while the Palestine version is “unashamedly political, designed to divide rather than unite.”
Former Royal Navy officer Stuart Fawcett tied it to last weekend’s march in London.
“Now, we see them hijacking our national symbol of remembrance,” he told the broadcaster.
The march he means took place Saturday, Oct. 10. The Met Police said it made 20 arrests, six of them for criminal damage after protesters climbed the Battle of Britain memorial on the Embankment, where wreaths at the base were trampled and destroyed. Others were held for showing placards backing Palestine Action, a proscribed group, and for a racially aggravated public order offense after a woman was seen making a Nazi salute, Jewish News reports, citing the force.
Conservative MP Nick Timothy called the protesters “scum,” and Lord Hannan asked what they had against the Battle of Britain pilots. Deputy Assistant Commissioner Carl Galvin, who ran the operation, said the march’s timing near the third anniversary of the Oct. 7 attack raised the risk to community relations.
The poppy’s website carries the slogan “From the river to the sea, Palestine will be free,” which critics read as a denial of Israel’s right to exist, the Mail notes. It also calls those killed or displaced in Gaza victims of “genocide,” a label Israel and its supporters reject.
Remembrance poppy
EUROPEAN PARLIAMENT
what took them so long:
European Parliament Condemns Muslim Brotherhood, Calls For Crackdown on Islamist Influence
The European Parliament has approved a resolution condemning the Muslim Brotherhood and calling for stronger action against Islamist influence in European institutions. The resolution is a significant development in the continent’s efforts to combat political extremism.
The center-right European People’s Party spearheaded the resolution, which follows the Trump administration’s designation of the Muslim Brotherhood and four affiliated branches as terrorist organizations.
French European Parliament member Céline Imart, who sponsored the measure, celebrated the vote as a breakthrough.
“This is a historic victory because it is a European first,”Imart said, describing the resolution as Europe’s first parliamentary action specifically confronting Islamist infiltration and the Muslim Brotherhood.
The resolution warns that organized Islamist networks threaten democratic institutions, religious freedoms, the rule of law and equality between men and women.
It calls for greater scrutiny of foreign funding, particularly involving organizations connected to Qatar and Turkey, and increased transparency surrounding European Union funding of groups suspected of Muslim Brotherhood ties.
Lawmakers also urged the European Council to consider whether Brotherhood-linked individuals and organizations should be added to the EU’s terrorist list.
Lorenzo Vidino, director of George Washington University’s Program on Extremism, said conservative lawmakers overwhelmingly supported the measure, while significant portions of the political left opposed it.
Imart criticized socialist and far-left lawmakers for boycotting negotiations on the resolution.
Security experts described the vote as an important first step toward confronting Islamist organizations accused of exploiting European democratic institutions.
“This resolution is where the pushback begins against Islamist entryism in Europe,” said Edmund Fitton-Brown, a senior fellow at the Foundation for Defense of Democracies.
However, the European Network Against Racism condemned the resolution, calling it discriminatory and warning that it could unfairly target Muslim communities and civil society organizations.
The Parliament emphasized that protecting Muslims from discrimination remains essential while distinguishing religious freedom from organized Islamist political activity.
Unlike the Trump administration’s terrorist designations, the European resolution is not binding legislation. Additional action by EU institutions would be required to implement its recommendations.
Imart vowed to continue pressing European leaders to act.
“This vote is a victory, but it is also a starting point,” she said.
END
EU NATURAL GAS/TUESDAY
EU NatGas Hits 2022 Crisis Levels As Goldman Warns 150 Euros Could Be Next
Tuesday, Oct 20, 2026 – 08:45 AM
Back in late August, Goldman Sachs commodities expert Samantha Dart warned that EU natural gas prices would need to soar dramatically to discourage Asian LNG demand and shift cargoes to Europe amid disruptions at the Strait of Hormuz.
Fast forward to Tuesday morning, European gas prices (TTF) have topped 90 euros per megawatt-hour, the highest level since late 2022. Notably, Dart warned about where prices were headed when EU NatGas was trading around 67 euros.
Separately, Goldman’s Daan Struyven and Dart released a new note earlier today, putting their base case for Brent crude at $90 a barrel and European benchmark EU NatGas at 70 euros by year-end, assuming a recovery in Middle Eastern supply and easing risk premiums. Brent is forecast to average $80 in 2027.
However, they warned that risks remained skewed toward the upside: Brent crude could climb to $140 early next year and average about $125 in 2027 if Gulf oil output averages 5 million barrels a day below February 2026 levels. As for EU NatGas, they warned it could soar to 150 euros if Gulf LNG exports remain at just one quarter of normal levels and a more severe winter boosts heating demand.
Here’s what they said:
Our base case is that a further recovery in Mideast supply and a moderation in the risk premium reduce prices of Brent crude and European natural gas to $90/bbl and EUR70/MWh, respectively, by end-2026.2 However, we remain concerned that geopolitical escalation—such as intensified shipping attacks or damage to energy infrastructure—and, for European natural gas, a cold winter could push energy prices significantly higher.
While estimated Persian Gulf exports of crude oil—including estimated dark exports— remained near their 2025 average over the past 7 days (Exhibit 2), they edged down from the early October highs as attacks on ships attempting to cross Hormuz have picked up (Exhibit 2). Estimated Gulf exports of refined oil products are much lower at around 40% of the 2025 average, in part reflecting Mideast refinery outages. Similarly, visible LNG crossings through Hormuz, have edged down this month relative to late October levels.
Misses in Mideast supply could push energy prices significantly higher:
Brent might rally to $140 in early 2027 and average around $125/bbl in 2027 (red line, Exhibit 4) if 2027 average Gulf output remains 5mb/d below Feb26 levels (while refined product prices would likely rise further from already very high levels)
TTF might rally to 150 EUR/MWh by year-end if Persian Gulf LNG exports don’t improve beyond 25% of normal and if the winter realizes 1 std. dev. colder than average (Exhibit 5)
Beyond energy, the analysts noted that the Bloomberg Commodity Index delivered a 36% total return this year, outperforming equities and bonds.
As ex-Goldman Sachs Jeff Currie, including ourselves, has pointed out, commodities have entered a period of scarcity, whether due to resource nationalism, adverse weather, supply woes, and more.
END
GERMANY
German Power Supply Startups Exit Market As Wholesale Prices Soar
Two startup electricity retailers in Germany have recently announced they would cease operations as spiking wholesale prices amid the gas price surge are pressuring the industry again, and this time the pressure is compounded by plans for renewable policy changes.
Renewable electricity provider Grüüün, part of Münch Energie Group, early this month said it would discontinue servicing about 200,000 residential customers as of October 31, 2026, and these will now have to switch to other providers.
Grüüün, which launched operations in 2024, attributed its decision to fold to Germany’s proposed changes to its renewable energy policy, including the upcoming overhaul of the Renewable Energy Sources Act (EEG 2027), the government’s focus on gas-fired power generation, and rising grid charges that have disrupted its long-term pricing structure.
Another startup, Berlin-based Stromee, has also reportedly exited the German retail market after a local utility in western Germany, SWK Energie GmbH, said this week that it had taken over power and gas customers “in the low five-digit range.”
The wholesale power price spikes and the regulatory shifts in Germany have made the sector vulnerable, with market exits reminiscent of the 2022 energy crisis when numerous small providers were forced to fold, Bloomberg notes.
This year, Germany is also facing the start of the winter with historically low levels of gas in storage sites. As of October 15, Germany’s gas storage sites were 60% full, well below the EU average of 74%, according to data by Gas Infrastructure Europe. The EU storage levels are at their lowest since at least 2011, raising concerns that a cold winter could lead to gas shortages.
Thanks to diversified import capabilities, Germany doesn’t face a gas supply shortage despite record-low levels of natural gas in storage sites, one of the biggest German gas importers, VNG, said at the end of last month.
Low stockpiles in Germany’s vast storage, the world’s fourth-largest, have prompted concerns about supply security if the coming winter turns out much colder than previous winters.
END
5.RUSSIA AND ISRAEL AND MIDDLE EASTERN AFFIARS
ISRAEL/IRAN/USA //TUESDAY
Two Tankers On Fire Off Oman As IRGC Boasts Of Naval Mine Warfare
Tuesday, Oct 20, 2026 – 08:25 AM
On Tuesday the UK Maritime Operations Centre has reported a new incident around 121 nautical miles east of the Omani coast.
The UKMTO announced the vessel was “subject to interaction as part of ongoing military activity in the region” at around 10am GMT. Regional reports say two tankers are on fire. But Tehran is boasting of a fresh sea mine attack, amid daily ramped-up assaults on international shipping as it tries to hold on to leverage over the United States and global oil transit.
Illustrative file image, via Free Malaysia Today
The Iranian side filled in more information, with the Islamic Revolutionary Guard Corps (IRGC) describing that “Two violating oil tankers were set ablaze and halted due to the explosion of mines planted by the brave sailors of the IRGC Navy at an illegal crossing point in the southern part of the Strait of Hormuz,” according to a statement published on their official Sepah News website.
This past weekend Iranian Foreign Minister Abbas Araqchi said that his country’s offer to the United States to reopen the Strait of Hormuz within seven days is still on the table.
Mediation efforts said that “Qatar and Pakistan presented a ‘compromise proposal’ that meets the demands of both the American and Iranian sides”, Al Araby Al Jadeed reports citing sources.
Those conditions were first presented in mid-September. “Our situation is clear and based on the seven-days proposal presented to the US. They shared comments which we are reviewing, but our proposal is still on the table and if there is any honesty on the US part, which there isn’t, the way to reopening the Strait of Hormuz is obvious,” Araqchi stated Sunday.
halt all US actions “under the pretext of threats and military operations”;
end the war on Iran and its regional allies;
withdraw US forces from areas around Iran’s borders;
pay compensation for war damage and commit not to interfere with Iran’s nuclear and missile capabilities.
According to more of the latest from BloombergTuesday morning:
Brent oil fluctuated near a five-month high as traders weighed the risk of further Iranian attacks in the Strait of Hormuz against robust crude flows from the Persian Gulf. The global benchmark was just below US$110 a barrel, near the highest since May, while the most-active West Texas Intermediate contract was close to US$99.
Iran has “no choice” but to assert control over Hormuz to safeguard the country’s security, First Vice-President Mohammad Reza Aref said on Oct 19, according to a report from state-run news agency IRNA.
Meanwhile, other Tehran officials have continued to warn that if active fighting resumes, Iran’s military still has a lot of cards to play.
At the start of this week IRGC spokesperson Hossein Mohebi has threatened to target undersea communication cables in the Strait of Hormuz. He warned that “all of the world’s internet and commercial data depend on them,” according to Al Jazeera.
He added: “We just want them to know that new targets and new weapons will be unveiled.”
Mohebi has also claimed that the US lacks the “technical and military”” capability to launch a new operation, which President Trump has lately threatened, likely to resume after the November midterm elections. So far the US military has remained surprisingly quiet amid daily Iranian assaults on international shipping.
More Latest Developments
via Newsquawk…
US President Trump criticised Europe for failing to support the US over Iran and suggested Washington could reconsider its support for Europe.
Iran’s IRGC said it intercepted and destroyed a US MQ-9 drone over the Strait of Hormuz using its new advanced air defence system.
Iranian Foreign Ministry Spokesperson Baghaei said they have held several contacts and consultations and that if there is even the slightest chance that it may be able to prevent the escalation of tensions through diplomacy, they must definitely go this route. On talks with Russia, Baghaei said there was no discussion about nuclear negotiations with the US, and that Iran are not negotiating with the US in this regard.
Iranian Foreign Ministry said the US’ response to the proposal from Iran was incomplete and insufficient.
Iranian President Pezeshkian said US bases in the region provide no benefits and only fuel insecurity, Press TV reported.
Iranian Foreign Minister Araghchi said Iran-Russia cooperation is closer than ever, with talks covering regional developments and expanding economic and nuclear cooperation, IRNA reported.
Qatari Foreign Ministry spokesperson said “We are working with Washington and Tehran in partnership with other mediating countries to end the war in the region.”
Pakistan Army Chief Munir has arrived in Tehran to meet with senior officials of Iran.
Russian Foreign Minister met Iran’s President and Supreme National Security Council Secretary in Tehran, following earlier talks with his Iranian counterpart, Iran Nuances reported.
An explosion was reportedly heard in Iran’s southern city of Bandar Abbas, Sabereen News reported.
Yemeni forces reportedly targeted Saudi Arabia’s Dammam airport with missiles and drones, temporarily suspending operations, Tasnim reported, citing Al-Masirah.
Israeli PM Netanyahu said there are indications that Iran and its proxies want to challenge Israel before the elections.
US War Secretary Hegseth met Israeli PM Netanyahu during an unannounced visit to Israel on Monday, Axios reported.
US President Trump’s envoys Kushner and Witkoff plan to travel to Norway this week for Ukraine talks and Ukraine President Zelensky is expected to join talks.
Ukrainian President Zelensky said he talked with US Secretary of State Rubio on the topics of ballistic interceptors and Starlinks. He later said that Ukraine supports a mutual energy ceasefire.
Ukraine’s DTEK said a Russian attack struck three of its energy facilities in the Odessa region.
The Trump administration has delayed approving transfers of Patriot interceptor missiles to Ukraine from partner countries, Washington Post reported.
END
Iran Rejects Report That Deal Is ‘Close’ After Qatar, Pakistan Push ‘Compromise Proposal’ To End War
Tuesday, Oct 20, 2026 – 11:17 AM
Update(1117ET): The somewhat expected quick rejection is coming from the Iranians via newswires:
IRAN-US TALKS CONTINUE, REPORTS DEAL IS CLOSE ARE WRONG
And Israeli media: “At least once, the US Trump administration was ‘very close’ to approving an attack on Iran” i24 Stein’s reports citing sources. Oil bouncing back on the Iranian rejection headlines, and despite…
RUBIO: OIL GOING THROUGH HORMUZ NEARLY EQUAL TO BEFORE WAR
* * *
Update(1035ET): This past weekend Iranian Foreign Minister Abbas Araqchi said that his country’s offer to the United States to reopen the Strait of Hormuz within seven days is still on the table.
By Tuesday morning, we have a return of another round of ‘deal imminent’-style headlines, which has gained more visibility over the last couple hours, resulting in oil prices tumbling:
Mediation efforts said that “Qatar and Pakistan presented a ‘compromise proposal’ that meets the demands of both the American and Iranian sides”, Al Araby Al Jadeed reports citing sources.
Another bout of pressure in the crude complex as the earlier reports via Al Araby Al Jadeed related to a “compromise proposal” gets wider airing; a move which is lifting the ES
* * *
On Tuesday the UK Maritime Operations Centre has reported a new incident around 121 nautical miles east of the Omani coast.
The UKMTO announced the vessel was “subject to interaction as part of ongoing military activity in the region” at around 10am GMT. Regional reports say two tankers are on fire. But Tehran is boasting of a fresh sea mine attack, amid daily ramped-up assaults on international shipping as it tries to hold on to leverage over the United States and global oil transit.
Illustrative file image, via Free Malaysia Today
The Iranian side filled in more information, with the Islamic Revolutionary Guard Corps (IRGC) describing that “Two violating oil tankers were set ablaze and halted due to the explosion of mines planted by the brave sailors of the IRGC Navy at an illegal crossing point in the southern part of the Strait of Hormuz,” according to a statement published on their official Sepah News website.
END
Amid ‘Compromise’ Chaos, Analyst Sees 90% Chance Of Iran War Round 3 As Hegseth Makes ‘Secretive’ Israel Visit
Tuesday, Oct 20, 2026 – 11:15 AM
The Monday surprise visit of US Secretary of War Pete Hegseth to Israel where he met with Prime Minister Benjamin Netanyahu has set off an avalanche of speculation regarding the likelihood of another major round of fighting in the Iran war.
The trip has been presented by Axios as happening under some degree of secrecy, with talks having taken place at the Ovda Air Base in southern Israel, which plays host to US refueling planes and fighter jets. While the Pentagon did not immediately comment, Israeli media has also been reporting on the high profile visit to the airbase. The Trump administration has remained silent on the visit.
But what has taken over by Tuesday morning are more ‘deal imminent’-style headlines, coming out of Gulf-aligned sources:
Mediation efforts said that “Qatar and Pakistan presented a ‘compromise proposal’ that meets the demands of both the American and Iranian sides”, Al Araby Al Jadeed reports, citing unnamed officials.
The timing of all this is most interesting, given that in the Hormuz Strait, Iran is mounting daily attacks against international shipping (it’s been a record-breaking pace this month) – but with nothing seen in the way of direct retaliation by the US military. On the Arabian peninsula, the Houthis have stepped up ballistic missile strikes on Saudi Arabia, a situation which threatens to merge the Persian Gulf and Yemeni theatres of conflict.
Closer to home in Israel, the country’s parliamentary election is just a week away, and Netanyahu is in a tough battle with main challenger, former military chief Gadi Eisenkot.
Netanyahu is doing what he’s done for his past couple decades in power – selling himself as the ‘war time leader’ – which President Trump has lately backed, calling him the “Great Warrior” prime minister (in a Truth Social endorsement).
“Donald, we have a job to finish. You said it, and we will finish it together,” Netanyahu subsequently told Trump in a phone call, following Trump’s public endorsement.
And related to the upcoming vote, the Israeli military has just been placed on its ‘highest state of alert’:
Israel Defense Forces Chief of Staff Lt. Gen. Eyal Zamir placed the military on its “highest state of alert” ahead of next week’s election and canceled soldiers’ leave, as Prime Minister Benjamin Netanyahu warned Israel’s enemies not to test the country.
Zamir held an assessment Monday morning with senior officers, during which he “stressed that the IDF’s mission is to enable the democratic elections to take place on schedule and safely,” according to a statement.
He said the military is “on the highest state of alert and will continue to maintain a high level of vigilance and readiness across all fronts” in the coming period, ahead of the October 27 vote.
Neither Israeli media or officials have cited any other direct threat or provocation as driving the heightened military alert level.
via Reuters
Trita Parsi of the Quincy Institute sees in all of this maneuvering signs of an imminent US-Israel military escalation against Iran. He lays out that “Things are looking very bad” in terms of the prospect for a third round of major war:
Between Trump’s coordination with Netanyahu – his bizarre endorsement of the Israeli war criminal and Heghseth’s surprise visit there – troop movements, and perhaps most importantly, a non-starter American proposal, the likelihood of a third round of the war is reaching 90% in my assessment.
As I have pointed out for weeks, Trump pretends the Strait is open and wants to exchange the lifting of the blockade for Iran’s 60% HEU instead of a reopening of the Strait. It’s understandable he wants a final deal right away. But it is unrealistic to expect a final deal without final-deal American compromises. As I understand it, Trump is not willing to offer that upfront, but wants Iran’s 60% HEU shipped out upfront. This won’t work and will likely lead to a third round of the war – before the midterms and possibly before Israel’s elections on the 27th.
Parsi has some further interesting insight on likely Iranian thinking concerning Washington insistence that nuclear negotiations be carried out as part of a comprehensive peace deal. Of course, Tehran has rejected this, saying time and again it will only address the nuclear file after the war concludes.
“All of these changes render a comprehensive deal less likely unless circumstances change considerably,” writes Parsi. “Instead, I suspect Iran mainly seeks temporary deals to lower the temperature in the immediate term, without ever seriously addressing the core nuclear issue until Trump leaves office.”
Fresh Tuesday reporting in Reuters seems consistent with this take – that Iran is ‘waiting out’ the Trump presidency (which should come as no surprise) and exploiting the compounding problems of his Operation Epic Fury:
Iran has deliberately prolonged talks with the US to try to weaken Donald Trump politically ahead of November’s US midterm elections, senior officials say, while fears of renewed military action and deep distrust of Washington have reinforced Tehran’s reluctance to strike a quick deal to end the war.
Three senior Iranian officials and an Iranian insider, speaking on condition of anonymity, said Tehran was convinced the US president was ready to resort to renewed attacks to try to break the stalemate in the eight-month-old war.
“Iran is preparing for renewed Israeli and US attacks, not for a deal with America to end the war,” one of the officials was quoted as saying. “The clerical establishment is determined not to give Trump a political victory.”
Houthis Target More Saudi Airports, Aramco Sites As US Issues Urgent Alert For 12 Mideast States
Monday, Oct 19, 2026 – 04:40 PM
Embassies in the Middle East – and broadly the State Department – have issued warnings that the Iran and Yemen conflicts may soon escalate unpredictably, including a blanket new travel alert covering for no less than a dozen regional countries.
More missiles were launched on Saudi Arabia Monday: “Yemen’s Houthis said on Monday they carried out attacks on Saudi energy, airport, and military targets including an Aramco facility in Yanbu, the Shaybah oilfield, King Khalid International Airport in Riyadh, and Abha airport,” reportsAl Jazeera. The Saudi government has yet to confirm that there were strikes on these locations, however.
AFP/Getty Images
Also, active fighting between Iranian and US forces could erupt once again at any moment. An Iranian official has freshly put US allied states across the region on notice.
An adviser to Supreme Leader Mojtaba Khamenei says Iran will respond with attacks against numerous US allies in the Middle East if it’s attacked again.
Conservative politician Mohammad Mokhber said Iran would strike “nine countries” if Iranian military bases or “petrochemical” facilities are struck again. His recorded comments posted by Tasnim, a semi-official news agency close to the Islamic Revolutionary Guard Corps, did not name the countries.
As for the newest US State Dept. alert that went out to Americans in the region, this high threat standard indicates that severe or life-threatening risks and dangers are present – also with the potential for getting trapped in a country, with possible flight cancellations, airspace closures and travel disruptions. Much of Saudi airspace has been closed for over a week at this point.
The fresh warning covering a dozen countries states that “the hostilities have the potential to escalate rapidly beyond that immediate area” and to “develop contingency plans in advance.”
“Iran and groups supportive of Iran may target other US interests overseas or at locations associated with the United States and Americans throughout the world, including US businesses and other institutions,” the alert said. The below countries are listed:
Saudi Arabia
Yemen
Israel
Iraq
Lebanon
Jordan
Qatar
Bahrain
Kuwait
UAE
Oman
Iran
One obvious highly dangerous place of travel remains Saudi Arabia, where the Houthis have been targeting major airports – including Riyadh’s main international hub – as well as Aramco oil infrastructure, almost on a daily basis. Already at the start renewed Yemen fighting, the US Embassy in Saudi Arabia warned its diplomats against unauthorized travel through King Khalid International Airport.
At this point the international hub remains closed for an indefinite amount of time, with the Houthis again on Monday announcing the airport was targeted by a ballistic missile.
There’s some speculation that the new heighted State Dept. alert could be a precursor to potential renewed US bombing raids against Iran, despite White House statements indicating this likely won’t happen until after the November midterm elections.
END
TURKEY/AZERBAIJAN//ISRAEL
attack Azerbaijan because of their banning hijabs?
Is Turkiye Plotting A Coup In Brotherly Azerbaijan?
A now-deleted Azeri article over the weekend, whose initial publication was perceived by many Turks as having been state-approved, prompted a complaint from the Turkish Embassy in Baku and worsened mutual suspicions among these fraternal people of what the other’s government is up to.
The Turkish Embassy in Baku released a statement over the weekend denying a local media report that former spy chief-turned-Foreign Minister Hakan Fidan’s picture with members of the “Youth Assistance Foundation” during his latest trip to Baku to attend a multilateral event was proof of a secret meeting. The report has since been deleted, but the gist was that the aforesaid group and others are operating under Turkiye’s influence to weaponize the recent pro-hijab protests for regime change purposes.
For background, Turkish President Recep Tayyip Erdogan’s condemnation of unnamed states’ hijab bans in his UNGA speech last month preceded the entry into force of Azerbaijan’s new school uniform policy that was interpreted by some administrators in that way, thus prompting a wave of protests. His Azerbaijani counterpart Ilham Aliyev then accused unnamed states of meddling in Azeri affairs during a speech to members of the ruling party. Some Azeris suspect that Turkish activists organized the protests.
Ahead of the previously mentioned event in Baku, Aliyev dispatched his national airline to pick up his Israeli counterpart on a plane named after the Azeri-Turkish alliance to fly him to to Baku across Turkish airspace despite Ankara banning all Israeli flights, which some Turks considered to be a snub. Since then, criticalarticles about Turkiye have appeared in Azeri media, which is considered by some to be state-influenced. This further fueled their ongoing social media disputes. Here are three background briefings:
Two driving forces are behind this unprecedented dispute between these fraternal nations that consider themselves to be “one nation, two states”. These are Turkiye’s discomfort with Azerbaijan’s de facto alliance with Israel, with which Turkiye has been in a rivalry since October 7th, and Azerbaijan’s discomfort what some perceive to be Turkiye’s Neo-Ottoman plans. Some Turks now suspect that Israel is behind Azerbaijan’s alleged hijab ban while some Azeris suspect that Turkiye is behind the protests.
Moreover, some Azeris worry that Turkiye’s suspected plans to turn August 2025’s “Trump Route for International Peace and Prosperity” into a Turkish-led NATO logistics corridor along Russia’s southern periphery could spark a Ukrainian-like war, while some Turks believe that Israel planted these fears. The hijab issue was therefore only the spark for getting Azeris and Turks to air out their grievances against one another on social media, not the root cause, but it now seems to have taken on a life of its own.
This background contextualizes the earlier cited article that was deleted after the Turkish Embassy’s complaint. While its veracity is unclear, what’s much more certain is that its publication was probably greenlit to signal to Turkiye to rein in its social media activists who’ve directly involved themselves in Azerbaijan’s hijab debate, which Baku tacitly considers to be meddling given the protests that have since followed. If they don’t soon stop, then Azeris might consider this to be a betrayal of their brotherhood.
COVID VACCINE INJURY REPORTS; DR MARK CRISPIN MILLER
DR PAUL ALEXANDER
RABOBANK/MICHAEL EVERY/OR OR PICTON/GIFFIN OR RABOBANK EXECUTIVE/COMMENTARY ON WORLDLY AFFAIRS
7. OIL AND NATURAL GAS/ENERGY COMMENTARIES
Oil Tumbles As Qatar, Pakistan Tout ‘Compromise Proposal’ To End Iran War
Tuesday, Oct 20, 2026 – 10:35 AM
Update(1035ET): This past weekend Iranian Foreign Minister Abbas Araqchi said that his country’s offer to the United States to reopen the Strait of Hormuz within seven days is still on the table.
By Tuesday morning, we have a return of another round of ‘deal imminent’-style headlines, which has gained more visibility over the last couple hours, resulting in oil prices tumbling:
Mediation efforts said that “Qatar and Pakistan presented a ‘compromise proposal’ that meets the demands of both the American and Iranian sides”, Al Araby Al Jadeed reports citing sources.
Another bout of pressure in the crude complex as the earlier reports via Al Araby Al Jadeed related to a “compromise proposal” gets wider airing; a move which is lifting the ES
* * *
On Tuesday the UK Maritime Operations Centre has reported a new incident around 121 nautical miles east of the Omani coast.
The UKMTO announced the vessel was “subject to interaction as part of ongoing military activity in the region” at around 10am GMT. Regional reports say two tankers are on fire. But Tehran is boasting of a fresh sea mine attack, amid daily ramped-up assaults on international shipping as it tries to hold on to leverage over the United States and global oil transit.
Illustrative file image, via Free Malaysia Today
The Iranian side filled in more information, with the Islamic Revolutionary Guard Corps (IRGC) describing that “Two violating oil tankers were set ablaze and halted due to the explosion of mines planted by the brave sailors of the IRGC Navy at an illegal crossing point in the southern part of the Strait of Hormuz,” according to a statement published on their official Sepah News website.
Those conditions were first presented in mid-September. “Our situation is clear and based on the seven-days proposal presented to the US. They shared comments which we are reviewing, but our proposal is still on the table and if there is any honesty on the US part, which there isn’t, the way to reopening the Strait of Hormuz is obvious,” Araqchi stated Sunday.
halt all US actions “under the pretext of threats and military operations”;
end the war on Iran and its regional allies;
withdraw US forces from areas around Iran’s borders;
pay compensation for war damage and commit not to interfere with Iran’s nuclear and missile capabilities.
According to more of the latest from BloombergTuesday morning:
Brent oil fluctuated near a five-month high as traders weighed the risk of further Iranian attacks in the Strait of Hormuz against robust crude flows from the Persian Gulf. The global benchmark was just below US$110 a barrel, near the highest since May, while the most-active West Texas Intermediate contract was close to US$99.
Iran has “no choice” but to assert control over Hormuz to safeguard the country’s security, First Vice-President Mohammad Reza Aref said on Oct 19, according to a report from state-run news agency IRNA.
Meanwhile, other Tehran officials have continued to warn that if active fighting resumes, Iran’s military still has a lot of cards to play.
END
8. EMERGING MARKETS//AUSTRALIA NEW ZEALAND ISSUES
CANADA/ ALBERTA votes to stay in Canada
Alberta Overwhelmingly Votes To Stay In Canada In Historic Referendum
With about 1.2 million votes counted, about 76% were in favor of remaining in Canada, enough for the Canadian Broadcasting Corp. to project victory for that side. The other option on the ballot was to support starting a legal process that could eventually lead to a second referendum on independence.
Premier Danielle Smith called the referendum in May after separatist organizers collected hundreds of thousands of names on a petition that asked for a vote. She advocated for staying in the country, though opinion surveys showed supporters of her United Conservative Party are divided on the matter. That tension may play out in the coming months, as she and others have warned of a potential split within the governing party.
“I’m very pleased to see the initial results from Elections Alberta show widespread support for remaining in Canada. Albertans have voted for a stronger Alberta in a united Canada,” Smith said in a statement. She said she would make a live address to the province on Tuesday evening.
The resource-rich province of 5 million people produces more than 4 million barrels a day of oil and ships the bulk of it to refineries in the US, helping to make energy Canada’s largest category of exports.The region has been the epicenter of anger about former Prime Minister Justin Trudeau’s environmental policies, which restricted energy development and sought to promote renewables over fossil fuels.
Since taking power more than 18 months ago, Carney has reversed or changed a number of Trudeau’s signature policies – canceling a consumer carbon tax, loosening emissions rules and focusing the government on attracting more investment.
The prime minister, who grew up in Alberta, also made a series of pacts with Smith. The Canadian government agreed to back a new 1 million-barrel-a-day oil pipeline to the west coast as a project in the “national interest.” Carney and his cabinet pledged to fast-track approvals and asked state-owned pipeline company Trans Mountain Corp. to lead the building of it.
The issue captured public attention. The most prominent pro-Canada group was led by Lukaszuk, who crisscrossed the province in a recreational vehicle to give speeches, hold events and hand out lawn signs. Carney appeared twice at the group’s rallies last week in Calgary and Edmonton.
Alberta premier Danielle Smith reduced the number of signatures needed to hold the advisory referendum, but cheered the result.
end
U.S./GOLD AND SILVER PRICING/ASIAN CLOSING MARKETS AND EUROPEAN BOURSE OPENING AND CLOSING/ INTEREST RATE SETTINGS TUESDAY MORNING 6;30AM//OPENING AND CLOSING\
OPENING LEVELS OF CURRENCIES// AND CLOSING ASIAN STOCK MARKET AND OPENING EUROPEAN STOCKS:6 AM EST
EURO VS USA DOLLAR: 1.1212 DOWN 0.0002
USA/ YEN 158.18 DOWN 0.347 NOW TARGETS INTEREST RATE AT 1.75% AS IT WILL BUY UNLIMITED BONDS TO GETS TO THAT LEVEL…//YEN STILL FALLS//END OF YEN CARRY TRADE BEGINS AGAIN DEC 2024/Bank of Japan raises rates by .25% TO 1.75 ..TAKAICHI NEW PM AS YIELDS RISE//JAPAN DEEPLY IN TROUBLE WITH RISING RATES AND A FALLING YEN!! BANK OF JAPAN WILL NO LONGER DO QE. URGES PENSION AND INSUANCE FUNDS TO BUY JAPANESE BONDS//
YEN CARRY TRADERS MURDERED
GBP/USA1.3338 UP 0.0008 OR 8 BASIS PTS
USA/CAN DOLLAR: 1.4053 DOWN 0.0054 //CDN DOLLAR UP 54 BASIS PTS//
Last night Shanghai COMPOSITE CLOSED UP 4.45 PTS OR 0.12%
Hang Seng CLOSED DOWN 319.09 PTS OR 1.32%
AUSTRALIA CLOSED UP 0.28%
// EUROPEAN BOURSE: ALL RED
Trading from Europe and ASIA
I) EUROPEAN BOURSES: ALL RED
2/ CHINESE BOURSES / :Hang SENG CLOSED DOWN 319.09 PTS OR 1.32%
/SHANGHAI CLOSED UP 4.45 PTS OR 0.12%
AUSTRALIA BOURSE CLOSED UP 0.28%
(Nikkei (Japan) CLOSED DOWN 752.30 PTS OR 1.16%
INDIA’S SENSEX IN THE RED
Gold very early morning trading: $4116.30
silver:$57.11
USA DOLLAR VS TRY (TURKISH LIRA): 49.58 UP 3 BASIS PTS AND NOW WE SEE THEIR STUPIDITY OF SELLING SOME OF THEIR GOLD AND ALL OF THEIR USA DOLLAR RESERVES. THE COUNTRY IS IN BIG FINANCIAL TROUBLE
USA DOLLAR VS RUSSIAN ROUBLE: 82.61 ROUBLE// UP 0 ROUBLE AND 13 BASIS PTS.
UK 10 YR BOND YIELD: 5.4393 UP 3 BASIS PTS
UK 30 YR BOND YIELD: 5.8882 UP 3 BASIS PTS
FRENCH OAT 10 YR BOND YIELD: 4.866 UP 8 BASIS PTS.
CDN 10 YR BOND YIELD: 3.948 UP 2 BASIS PTS
CDN 5 YR BOND YIELD; 3.669 UP 2 BASIS PTS
USA dollar index early TUESDAY MORNING: 101.67 DOWN 11 BASIS POINTS FROM MONDAY’s CLOSE
TUESDAY MORNING NUMBERS ENDS
And now your closing TUESDAY NUMBERS 10.00 AM
Portuguese 10 year bond yield: 3.911% DOWN 3 in basis point(s) yield
JAPANESE BOND 10 yr YIELD: +2.8920% DOWN 2 FULL POINTS BASIS POINTS /JAPAN losing control of its yield curve/
JAPAN 30 YR: 3.9444 DOWN 5 BASIS PTS//
SPANISH 10 YR BOND YIELD: 4.048 DOWN 3 in basis points yield
ITALY 10 YR BOND: 4.5690 UP 0 points in basis points yield ./
GERMAN 10 YR BOND YIELD: 3.4171 DOWN 4 BASIS PTS
IMPORTANT CURRENCY CLOSES : MID DAY TUESDAY
Closing currency crosses for day /USA DOLLAR INDEX/USA 10 YR BOND YIELD/10:00 AM
Euro/USA 1.1232 DOWN 0.0019 OR 19 basis points
USA/Japan: 158.05 DOWN 0.473 OR YEN IS UP 48 BASIS PTS// HIGHLY INFLATIONARY TO JAPAN
Great Britain 10 YR RATE 5.4403 UP 3 BASIS POINTS //
GREAT BRITAIN 30 YR BOND; 5.8737 DOWN 2 BASIS POINTS.
REAR VIEW: Reports suggest a compromise proposal meets the demands of both the US and Iran, implying progress, although later sources rejected claims that a US-Iran deal is close; Iranian officials say they cannot gain US trust until seven conditions are met; US Pending Home Sales sink in September, Building Permits slightly above forecasts; BoJ is reportedly likely to keep rates unchanged in October but may signal that a rate hike could come in December; UK unemployment rate unexpectedly declines; Germany’s ZEW falls more than expected; GM shares fall on FY profit outlook miss.
Stocks climbed as breadth outside of AI-related names was strong, with Healthcare setting fresh YTD highs. Other gains were seen in Utilities, Financials and Consumer Discretionary. Meanwhile, Communications underperformed on Alphabet and Meta weakness, whilst Tech saw marginal losses. The lackluster performance in AI names amid the broad rally, likely explains the continued bid for US Treasuries, as concerns remain over AI-exposed debt. Short-end yields, however, were modestly firmer, leaving the curve flatter.
Oil prices settled lower on reports that a Qatar-Pakistan proposal presented to Iranian officials today has US approval and had previously been accepted by Iran. The proposal includes a compromise from both sides on the nuclear issue and frozen Iranian funds. Crude prices fell sharply as the report got wider airing, before paring some of the losses on a counter-report citing a diplomat close to the talks, who said that Iran and US talks continue and that reports the deal is close are wrong.
In FX, the dollar was weighed on by downside in US yields, leaving major peers firmer. GBP outperformed following an unexpected decline in the unemployment rate. Precious metals were mixed: gold saw losses despite the lower yield environment, while silver gained.
US data included a huge 7.3% decline in Pending Home Sales to the lowest level on record, as higher mortgage rates remain a barrier to a pickup in housing activity; Building Permits were little changed in September. Elsewhere, the Atlanta Fed revised its GDPNow Q3 real GDP growth estimate lower to 3.5% from 3.6%.
US
PENDING HOME SALES: Pending Home Sales tumbled 7.3% M/M in September (exp. -0.5%), with M/M sales declining in all four major US regions. Market conditions continued to weaken amid fast-rising mortgage rates, with housing affordability highly sensitive to mortgage rates. NAR Chief Economist Yun said, “Given that mortgage rates have already risen much more than the Federal Reserve’s short-term interest rate hikes, mortgage rates could be topping out”, although energy prices and the resulting inflationary reaction remain highly uncertain. Yun added, “Despite the difficulty of obtaining a mortgage, the limited number of distressed properties is ensuring steady home prices, buyers and sellers may simply be holding back until mortgage rates move favorably.” *
HOUSING STARTS/BUILDING PERMITS: Housing Starts fell 5.2% M/M in September to 1.221mln (exp. 1.300mln, prev. 1.288mln), while Building Permits dipped 0.2% to 1.400mln (exp. 1.390mln, prev. 1.403mln), but were above expectations. For Starts, single-family dropped 4.6% to 859k (prev. 900k), with multi-family also falling 6.7% to 349k. Looking at permits, single-family authorisations declined 4% to 845k, with multi-family printing 503k.
FIXED INCOME
T-NOTE FUTURES (Z6) SETTLED 2 TICKS HIGHER AT 105-10
Treasury curve flattens as AI debt concerns keep the flight-to-haven trade in play. At settlement, 2-year +0.9bps at 4.787%, 3-year +0.4bps at 4.872%, 5-year -1.1bps at 4.936%, 7-year -2.3bps at 5.021%, 10-year -2.3bps at 5.119%, 20-year -4.9bps at 5.479%, 30-year -5.0bps at 5.426%.
THE DAY: The Treasury curve was flatter. Whilst breadth was encouraging in US equities, the lacklustre tech performance reflects continued concern surrounding AI debt and, as such, gives investors further reason to increase exposure to USTs. That said, the short end was sold, leaving front-end yields modestly higher despite the slight decline in oil prices on optimism over a potential US-Iran deal. A clear driver of the 2/3yr upside was lacking, but with markets still favouring a hold at next week’s FOMC, repricing may have been at play. Additionally, even if a US-Iran deal were reached imminently, resolving the refined product shortage is not an overnight fix, as repairing refineries and building extra capacity can take months/years.
US data included a huge 7.3% decline in Pending Home Sales to the lowest level on record, as higher mortgage rates remain a barrier to a pickup in housing activity; Building Permits were little changed in September, as expected. Today, the Atlanta Fed revised its GDPNow Q3 real GDP growth estimate lower to 3.5% from 3.6%.
Supply
US sold 6-week bills at a high rate of 3.975%, B/C 2.74x
US to sell USD 75bln of 17-week bills on October 21st, and USD 105bln of 8-week bills and USD 110bln of 4-week bills on October 22nd; all to settle on October 27th
STIRS / OPERATIONS
Fed Hike Pricing via CME FedWatch: Oct 4.3bps (prev. 4.3bps), Dec 25.8bps (prev. 26.0bps)
EFFR at 3.88% (prev. 3.88%), volumes at USD 110bln (prev. USD 115bln) on October 19th
SOFR at 3.87% (prev. 3.88%), volumes at USD 2.888tln (prev. USD 2.925tln) on October 19th
NY Fed RRP op demand at USD 0.227bln (prev. USD 0.330bln) across 3 counterparties (prev. 7) on October 20th
CRUDE
WTI (Z6) SETTLED USD 0.72 LOWER AT 97.82/BBL; BRENT (X6) SETTLED USD 0.76 LOWER AT USD 108.78/BBL
The crude complex was lower, albeit in choppy trade, as constructive Middle East headlines dominated price action. WTI and Brent hit highs of USD 101.37/bbl and USD 111.99/bbl, respectively, in US pre-market trade, before pulling back on an Al Araby Al Jadeed report, which said Qatar and Pakistan presented a proposal to Iranian officials today that has US approval and had previously received Iranian approval. As the report got wider airing on other outlets, the oil downside notably extended, with WTI hitting a trough of USD 95.25/bbl and Brent a low of USD 105.95/bbl. However, reports, citing an official close to the talks, noted that talks between Iran and the US continue and that reports the deal is close are wrong, which allowed crude to pare some of the move. Later, the Iranian President said that for any negotiation, the pressures, threats and sanctions must first be lifted. After-hours attention turns to the weekly private inventory metrics.
EQUITIES
CLOSES: SPX +0.28% at 7,713, NDX -0.13% at 29,490, DJI +1.02% at 52,497, RUT +1.67% at 2,774
SECTORS: Communication services -0.89%, Technology -0.34%, Industrials flat, Energy +0.18%, Consumer staples +0.28%, Materials +0.31%, Consumer discretionary +0.72%, Financials +1.14%, Utilities +1.15%, Real estate +1.7%, Health +2.34%.
EUROPEAN CLOSES: Euro Stoxx 50 -0.33% at 6,125, Dax 40 -0.05% at 25,307, FTSE 100 -0.29% at 10,733, CAC 40 -0.38% at 7,838, FTSE MIB -0.03% at 49,071, IBEX 35 +0.28% at 19,092, PSI -0.67% at 9,331, SMI +0.76% at 14,478, AEX -0.68% at 1,134.
STOCK SPECIFICS:
3M (MMM): Profit beat and lifted FY EPS guidance.
RTX (RTX): Top and bottom lines beat expectations, with a strong outlook.
Steel Dynamics (STLD): EPS and revenue fell short of Wall Street consensus.
Solstice Advanced Materials (SOLS): Starboard Value has built a stake worth several hundred million dollars.
MSCI (MSCI): Revenue beat.
General Motors (GM): Announced a USD 20bln share repurchase programme.
Halliburton (HAL): EPS and revenue topped Wall Street expectations.
Apple (AAPL): Downgraded at Loop Capital.
CoreWeave (CRWV): ‘Reduce’ rating reiterated at HSBC.
Braze (BRZE): To be acquired by Salesforce (CRM) for c. USD 5.66bln in enterprise value, with shareholders to receive USD 47.50/shr in cash.
Casella Waste Systems (CWST): Jana Partners has built a stake and urged management to improve margins and returns on capital.
Qiagen (QGEN): EQT is reportedly in advanced talks to acquire the company.
FX
The Dollar Index was lower on Tuesday, seemingly hit by broader risk sentiment as US equities marched higher despite flattish AI names, alongside more encouraging developments out of the Middle East, although these were later denied. On the data front, US Pending Home Sales for September tumbled much more than expected, continuing to highlight the US housing market’s struggles given current mortgage rates, which risk moving higher given current energy prices and their potential knock-on effect on inflation.
G10 FX peers were firmer across the board against the Dollar, as, while the aforementioned broader market conditions helped, some currency-specific catalysts also aided. The Pound, the outperformer, was supported by the better-than-expected UK unemployment figure. On the central bank front, BoE’s Greene said she continues to believe the Bank should proactively lean against the risk of second-round inflation effects, adding that this risk is greater than previously thought. Cable traded between 1.3295-1.3409.
Elsewhere, sources overnight said the BoJ is likely to keep rates unchanged in October but may signal that a rate hike could come in December; the Bank may also raise its FY27 inflation forecast slightly. Overall, the report does little to shift market expectations, and at the time of writing, money markets assign only a 5% chance of a hike in October and c. 80% in December.
In Europe, the German ZEW Economic Sentiment Index for October disappointed, with the headline coming in at 28.1, below the expected 30.0 and the prior 34.7. Finally, there was little reaction in the HUF after the NBH left rates unchanged at 5.50%, as expected. In post-decision comments, the NBH said it is committed to achieving the inflation target in a sustainable manner.
END
USA DATA RELEASES
Housing Starts Collapse Near COVID Lows As Homebuilder Confidence Crashes
…it should be no surprise that homebuilders are unwilling to Start building (Housing Starts -5.2% MoM in September and August revised down to a 5.9% MoM plunge) or even more forward looking, get Permits ( -0.2% MoM)…
On a SAAR basis, Starts are back near post-COVID lows while Permits are holding near the lows of a four year range…
Starts of single-family home construction decreased to the lowest level in a year.
Finally, circling back to where we started, Homebuyers have never been less enthusiastic about the American Dream… perhaps this is why…
The gap between current mortgage rates (7.5%) and the average mortgage across all of American homeowners (4.33%) is extreme to say the least, trapping sellers and buyers…
Who blinks first? With inventories of new homes at highs…
…it appears builders aren’t willing to throw good money after bad until the mortgage-rate gap narrows further.
END
US Pending Home Sales Collapse To Record Lows In September
After a very small rebound (+0.3% MoM) in August, US Pending Home Sales collapsed (-7.3% MoM vs -3.9% MoM exp) in September. That dragged
“Market conditions weakened in September due to fast-rising mortgage rates,” says Lawrence Yun, NAR’s chief economist.
“Although job growth and income gains can support home purchases, housing affordability is more affected by changes in mortgage rates…
…Buyers and sellers may simply be holding back until mortgage rates move favorably.”
September’s slump smashes the Pending Home Sales Index to a record low…
But Yun believes – ever the optimist – that the rapid run-up in mortgage rates over the last month may be nearing the end.
“Given that mortgage rates have already risen much more than the Federal Reserve’s short-term interest rate hikes, mortgage rates could be topping out,” Yun says.
“However, increasing energy prices and the resulting inflationary pressures are highly uncertain.”
For the week of October 11, the 30-year fixed mortgage rate came in at 7.40% per Freddie Mac, flat sequentially and up 113bps YOY. Mortgage applications fell 37% YOY along with refinancings down 56% YOY, both similar to last week, while purchase volumes declined 16% YOY vs -15% last week. ARMs accounted for 11% of volume, up 20bps sequentially and vs 9% last year. Purchase applications were down 4% sequentially as rates hold at a 52-week high, though they are 5% above the February 2025 trough.
Goldman Sachs economists sum things up succinctly: “We expect near-term [housing] activity to remain under pressure given the rate and broader macro backdrop.”
Contract signings in September dropped by the largest percentage in the West, falling 9.2% from August and down 15% from a year ago. The South followed with an 8.2% month-over-month and 12% annual decrease in September. The Midwest posted a 6.5% monthly decline and 8.7% decrease from a year ago.
Meanwhile, the Northeast fared best, but with pending home sales still falling 4.2% in September compared to August and down 9.4% from a year earlier. The region continues to grapple with some of the nation’s tightest housing inventories, which has fueled strong price gains and ongoing bidding wars in some markets. In September, the Northeast posted the largest annual home price increase in the country, with the median existing-home price rising 5% to $523,600.
As a reminder, because houses typically go under contract a month or two before they’re sold, the pending home sales data tend to be a leading indicator of closings that are captured in the monthly previously owned home sales reports.
Translation – this is terrible news building on an already ugly situation in the US housing market.
USA ECONOMIC REPORTS
44% Of Americans Have Trouble Paying For Basic Necessities As Lifetime Cost Of The American Dream Tops $5 Million
How did we get to a point where nearly half of the entire population is struggling to even pay for the most basic necessities? A lot of people talk about “economic collapse” as something that will occur someday in the future. The truth is that “economic collapse” has been slowly happening for decades as the middle class has been systematically eviscerated. It now takes 5.3 million dollars to live the American Dream over the course of a lifetime. Who can afford that? Most Americans aren’t even going to come close to making 5.3 million dollars during their working years. Of course in this economic environment, much of the population is just concerned with trying to survive from month to month. The cost of living crisis that has been raging for this entire decade is absolutely crushing millions upon millions of U.S. households, and now we just learned that the official inflation rate has gone up again.
If financial stress has become a major theme in your life, I want you to know that you are not alone.
According to a shocking new survey just released by the Pew Research Center, 44 percent of Americans struggle to even pay for the most basic necessities…
More than four-in-ten Americans (44%) indicate they have had trouble paying for at least one of these basic necessities in the past year
We aren’t talking about having difficulty paying the phone bill.
The survey found that an alarmingly high percentage of the population can’t even afford to pay for housing, food and medical care.
60% say they do not currently have enough income to lead the kind of life they want.
53% say they do not have emergency funds that would cover their expenses for three months.
27% cannot pay some of their monthly bills or can only make partial payments.
32% say they worry every day or almost every day about the cost of healthcare and the amount of debt they have.
More than a quarter of the population is getting behind on their debts.
That is what you call a crisis.
And there is no end in sight.
Most Americans don’t want to be rich.
Most Americans just want to live a middle class lifestyle like their parents did.
Unfortunately, it now costs 5.3 million dollars to live the American Dream over the course of a lifetime…
The cost of the American dream is rising at a faster pace than household earnings, driven by notable increases in the cost of homeownership, raising children and paying for college, according to a new report.
An analysis by Investopedia finds that the lifetime cost of the American dream rose 4.1% from 2025 to 2026, with the cost increasing by more than $208,000 from $5.11 million a year ago to $5.32 million this year.
Are you going to make more than 5 million dollars during your working years?
Homeownership costs rose the most in dollar terms, with the lifetime cost rising by over $91,000 from $1.184 million in 2025 to $1.275 million in 2026. That rise amounts to a 7.7% increase year over year.
That figure includes a 20% down payment on a median-priced single-family home of $420,000, with a 6.32% 30-year mortgage that brings the total cost with interest to about $837,000, as well as $3,057 a year in insurance costs, property taxes and 30 years of upkeep and utilities which adds another $438,000 to the price tag.
Of course the figures quoted above no longer apply, because the average rate on a 30 year mortgage is now well over 7 percent.
So now homeownership is even more unaffordable.
And just about everything else is becoming more expensive too.
Today we learned that the official rate of inflation just went up again…
September brought little relief to the accelerating cost of living, as consumer prices increased again and kept the inflation rate well above the Federal Reserve’s goal.
The consumer price index, a broad measure of goods and services costs across the U.S. economy, rose a seasonally adjusted 0.6% for the month, putting the 12-month rate at 3.7%, the Bureau of Labor Statistics reported Wednesday. Economists surveyed by Dow Jones expected respective gains of 0.6% and 3.6%.
The formula that is used to calculate the official rate of inflation has been changed dozens of times since the Jimmy Carter era, and at this stage it doesn’t even come close to accurately reflecting how quickly prices are actually going up.
But the fact that even the government is admitting that inflation is rising is not good.
Soaring energy costs were the primary reason for the spike in the inflation rate…
Energy costs drove inflation in September, and high retail prices in October suggest pain at the pump will continue. Prices have soared since the Iran conflict started at the end of February.
Gasoline prices last month rose 9.1% from the prior month – a faster pace than August’s 3.9% increase – and are up 34% over the past year. Fuel-oil prices, meanwhile, are up 74% since last September.
When this inflation report was released, it really spooked investors, and bond yields spiked dramatically…
The 10-year Treasury note yield rose on Wednesday following the latest U.S. inflation print.
The yield on the 10-year Treasury note – the main benchmark for mortgages, auto loans and credit card debt – jumped more than 7 basis points to 5.289% and reached the highest level since Oct. 8.
The longer-dated 30-year U.S. Treasury yield – which tends to react most to geopolitical events – was up more than 3 basis points to 5.602%.
The U.S. Treasury has been working really hard to keep bond yields under control.
I think that U.S. Treasury Secretary Scott Bessent is going to need a bigger boat.
During most economic downturns, normally we are either facing an inflation crisis or an unemployment crisis.
This time around, it appears that we will have both.
Mass layoffs have been occurring all over the nation, and on Wednesday we learned that Netflix is joining the party…
Netflix is reportedly laying off 1,000 workers – the streaming giant’s biggest cuts since 2022.
Staff were told Wednesday that about 6% of the workforce – within product, tech, legal, and human resources teams – was being slashed, according to a memo obtained by the Post.
Kroger is planning to eliminate approximately 3,000 corporate positions over the next three years as the grocery giant expands its use of artificial intelligence and looks to cut costs, according to a report.
The planned cuts would affect roughly 37% of Kroger’s approximately 8,200 corporate employees, Reuters reported Monday, citing an internal memo from CEO Greg Foran.
The restructuring comes as Kroger faces pressure to improve sales, keep grocery prices competitive and streamline operations through increased use of AI.
Every time more highly-paid jobs are wiped out, the middle class gets even smaller.
The top 10 percent of all income earners are still thriving, but for almost everyone else life is a struggle.
It didn’t have to turn out this way.
Decades of insanely bad decisions have brought us to this point, and now the cost of living is the number one political issue during this campaign season by a very wide margin.
END
People, Power And Politics: Morgan Stanley Maps The Three Ways AI’s $1.6 Trillion Capex Plan Can Collapse
MS’s public policy strategist Ariana Salvatore frames the main constraints on the AI infrastructure story as “people, power, and politics,” and the downside section works through all three. Spoiler alert: the bank still expects the buildout to happen, just with a growing list of asterisks attached.
The Midterm Wedge
Salvatore doesn’t mince words:
Political pushback, to be sure, has become the wedge issue in the midterm elections, which we think can present a catalyst with respect to this issue and broader AI sentiment.
Her framing has three key pieces:
No federal pause. Given the national-security framing and a likely presidential veto of restrictive legislation, MS doesn’t expect Washington to stop the buildout. Instead, she sees the midterms laying “the groundwork for potential legislation toward that end in 2029.”
The binding levers are local. Interconnection, large-load rate design, siting, permitting and tax abatements are all decided at the state level, “which is why governors and utility commissions matter more than Senate races.”
Incumbents vs. challengers. Because non-incumbent candidates in key races tend to propose tougher restrictions, MS sees sentiment as most constructive under a Republican sweep, broadly neutral under divided government, and least constructive under a Democratic sweep (something we discussed previously).
That last point is worth holding up against what the market has been doing. On Friday we noted that JPMorgan’s “Democrat Factor” has soared 20% as Wall Street prices in a sweep, and we laid out last month what’s likely to be on the target list if Democrats win the House, data centers included. Put the two together and the market is pricing the scenario MS calls least constructive for AI sentiment, with barely two weeks to go.
“No Major Candidate… Is Running As Pro-Data-Center Without Qualifiers”
The report’s most useful contribution is a race-by-race scorecard of every contest that could tighten the rules, from governors to elected utility commissions:
Three takeaways stand out.
First, the debate has moved from whether to restrict data centers to how: in Salvatore’s words, “the remaining argument is whether to pause development outright or allow it to proceed subject to specific conditions.”
Second, tax breaks are the consensus target regardless of who wins: Abbott, Tiffany, Ford, Nesbitt and Georgia Republicans have all called for repeal or rollback, and Arizona has already paused its exemption through June 2029.
Third, the utility commissions may matter most of all, since they “decide the dockets that set cost allocation and approve generation, and those are legally durable.” In Georgia, the 3-2 GOP majority on the PSC flips if Democrats win both seats; in Louisiana, a vote on ~$15 billion of Entergy gas units for Meta’s Richland Parish expansion lands right around the election.
And the stakes are huge. Adding up the capacity in the states MS flags (counting Georgia once), we get almost 60 GW of data centers under construction, planned or on acquired land, with Texas alone at 24 GW and Pennsylvania at 11 GW:
For context, MS’s own forecast has all hyperscalers and neoclouds adding 32 GW of compute capacity in 2027. Texas, where Governor Abbott paused new approvals in early August pending an audit of ~250-300 projects and then ordered a halt to new data centers in September, is a reminder that the incumbents aren’t exactly cheerleaders either. We flagged the math behind Abbott’s decision at the time:
Meanwhile Ohio, home to AWS, Meta, Google and Microsoft builds, is the cleanest example of both parties converging on restrictions, as we first noted last month:
MS remains “constructive on the buildout” because the industry is responding to each of the three pressure points with its own fix:
Electricity prices: a number of hyperscalers signed the Ratepayer Protection Pledge, promising to build or buy their own generation, cover grid upgrade costs and pay separate large-load rates whether or not they use the power (just don’t ask them to do the math on how realistic it is to get all the pieces together). Congress is moving the same way, with the House passing a bill making data centers cover their own energy costs.
Water: Google committed to returning more water to local systems than its data centers use by 2030, and Amazon disclosed global data center water use for the first time.
Quality of life: Meta launched a $1 billion fund for host-community teachers, first responders and infrastructure.
MS’s base case is therefore a “conditional buildout,” preserving the capex but only in regions where community engagement or mitigation works. Translation: the $1.6 trillion still gets spent, but some of it costs more and lands later, which feeds straight into the next two risks.
Volume And Price: “A Compounding Risk”
The second downside risk is the one we think gets the least attention, and Morgan Stanley lays it out as a classic capital-cycle problem. Scarcity drives what the bank calls the “fear of missing procurement”: buyers assume tomorrow’s compute will cost more, so they pay up today, and suppliers stack margins on top. That’s why volume growth and pricing power have reinforced each other. Then the cycle turns:
Once capacity catches up or demand normalizes, the same forward-buying and urgency that inflated prices work in reverse, collapsing pricing power just as suppliers are stuck holding high-cost inventory. It’s the standard capital-cycle playbook, just compressed by how concentrated the hyperscaler customer base is.
Incidentally, that is precisely what we said a month ago:
MS’s analog is the late-2022 memory downturn, when NAND shipments fell only ~5% but prices fell 20-30%, crushing supplier margins far faster than volumes alone implied. Applied to AI, “even a plateau (not a collapse)” in hyperscaler capex could leave volumes resilient while pricing and upstream margins evaporate. The bank’s conclusion is blunt: “We think the risk of both volumes and price falling at the same time is underappreciated in the current market.”
This connects directly to a point MS’s memory analysts make elsewhere in the report: Amazon attributed most of its 2026 capex increase to rising memory costs, with no change to its build plan. So a chunk of the capex “boom” is price, and memory is exactly where it would unwind first. Consumers are already feeling the other side of that trade, with global smartphone shipments crashing 22% as the memory crisis squeezes everyone not named Nvidia. And in memory (as in everything else), nothing cures record prices like record prices.
The 32 GW Power Wall
Finally, power, which MS calls “the most tangible risk that we see now.” The $1.6 trillion capex estimate assumes every chip ordered gets powered and put to work. MS’s own Powering AI model says that may not happen: even after time-to-power solutions (nuclear, turbines, engines and Bloom fuel cells), it still sees a 32 GW net US shortfall through 2028, or 34% of the 97 GW needed, and roughly 72 GW through 2029.
MS frames this as a timing mismatch rather than a demand collapse. Hyperscalers can keep buying scarce GPUs ahead of power (warehousing them as very expensive paperweights in dark and dusty data centers for years until they get “lit”, further pushing prices higher due to artificial scarcity), which certainly props up near-term chip revenue but “could produce hoarding and stranded inventory,” and eventually “buying power-dependent equipment that cannot be turned on is hard to sustain.” The risk is uneven across the chain:
Most exposed: components bought ahead of need that ship with the rack (memory, networking, optical, ODM server builds), with memory the most sensitive because recent capex increases are partly price.
Slower backlog conversion: electrical, cooling and construction equipment, where slower interconnection shows up as backlog conversion delays.
Relative winners: behind-the-meter generation (such as gas turbines and, eventually, modular nuclear reactors), fuel cells and powered shell providers. MS also expects hyperscalers to build more capex outside the US if domestic power stays tight.
Having pounded the table on precisely this issue for much of the past year, we’ll repeat it once more: behind-the-meter generation should be mandatory for every new data center. It solves the ratepayer problem that is driving the politics and the grid problem that is driving the shortfall at the same time. Even PJM, the nation’s biggest grid, had to scrap its emergency data center power auction earlier this month after a FERC smackdown, which tells you how well the alternative is going.
Paying For It
MS lays out all three risks and still lands on a constructive base case: a conditional buildout, a power gap that delays rather than destroys demand, and a price cycle that can be managed by long-term agreements. Maybe. But the three risks feed each other, meanwhile the AI money monster needs to be fed constantly and anything that leads to even a hint of capex slowdown send the entire cycle into reverse with catastrophic consequences. No wonder last week the most important man on Wall Street, Blackrock’s Larry Fink, warned a data center ban would put the US in recession. Politics slows interconnection and siting, which widens the power gap, which strands chips that were bought at peak prices, which is exactly the “volumes and price falling at the same time” scenario MS says nobody is positioned for.
We’d add a fourth “P” to MS’s list: paying for it. As MS’s credit strategists showed in the same report, 2027 is also the year free cash flow hits its deepest hole and the lower-rated borrowers run out of cushion.
A buildout that has to clear the ballot box, the grid and the bond market all at once has a lot more ways to slip than the $1.6 trillion headline suggests. November 3 is the first test, and with the market already pricing the least constructive outcome for AI, we’d watch the utility commissions at least as closely as the governors.
President Donald Trump announced a new Department of Agriculture program offering $8 billion to farmers during harvest season, as rising diesel costs strain operations nationwide.
“And when the Republicans win, we will pass even more funding for our farmers,” Trump told a standing-room-only crowd of thousands during a rally in the Heartland Credit Union Arena in Park City, just north of Wichita, Kansas.
The Harvest Fuel Relief program will use a formula to determine losses and offset increased diesel costs, with calculations similar to those used in the established Farmer Bridge Assistance program, according to a statement from the Department of Agriculture.
Farmer Cliff Carter works on an irrigation system for one of his rice fields in Rector, Ark., on June 5, 2026. Karen Pulfer Focht/Reuters
“This $8 billion dollar investment will help bring certainty to our farmers during this harvest so they can continue to feed our nation,” Agriculture Secretary Brooke Rollins said in a statement released shortly after the president’s announcement.
Diesel prices averaged $6.18 per gallon nationwide as of Oct. 12, up about $2.51 per gallon from the same time last year, according to the most recent data from the U.S. Energy Information Administration.
During an approximately 90-minute address, Trump highlighted recent policies his administration enacted to benefit farmers and rural Americans, including raising production targets for ethanol-based biofuels to the highest levels recorded, a move the president estimated would boost farm incomes in Kansas by $4 billion, collectively, per year.
He noted a recently signed waiver allowing the year-round sale of E15 gasoline could become permanent, but only if Republicans win in the upcoming midterm elections.
“If you want to see what is at stake in this election, just look at what’s happening in France, a once-great nation that is being conquered, looted, and burned to the ground by migrants, jihadists, and communists who hate Christianity, and they hate, frankly, the Western civilization itself,” Trump said.
“Americans are going to stand up and declare that we will defend our culture, we will protect our civilization, we will preserve our religion, our values, and our heritage, and we will never let our nation be conquered or destroyed by people that hate us.”
President Donald Trump reacts during a rally in support of Republican U.S. Senate reelection candidate Roger Marshall (R-Kan.) in Park City, Kan., on Oct. 19, 2026. Jonathan Ernst/Reuters
Incumbent first-term Republican Sen. Roger Marshall, facing Democratic challenger Adam Hamilton in a race recent polls suggest is a toss-up, told the crowd his reelection would support “secure borders, a strong military, and lower taxes.”
A loss would potentially allow Democrats to gain a majority and overtake consequential Senate committee positions, he said.
“If Kansas loses this Senate race, Chuck Schumer will control the Senate. Elizabeth Warren would control the Bank Committee, and Bernie Sanders would control the Health Care Committee, and Cory Booker, a vegan, would control the [Agriculture] Committee,” Marshall said.
“We need a senator on the ag committee that can sort heifers and steers, not someone who doesn’t know the difference between a bull and a steer.”
Hamilton co-founded the United Methodist Church of the Resurrection in Leawood, Kansas, and supported the inclusion of same-sex marriages and other changes to church protocols that led to division among some congregations.
His campaign is focused on reducing the cost of living and changing rules for elected officials, including establishing term-limits and blocking Congress members and their families from trading stocks.
“Washington has become overrun by chaos and corruption, with far too many politicians on both sides of the aisle putting themselves and special interests first instead of listening to their constituents’ needs. It’s time for a change,” Hamilton said in a statement, citing “rampant conflicts of interest and self-dealing,” among other issues he aims to correct.
“Kansans deserve leaders who truly believe in government ethics and real accountability.”
Republican nominee for governor Ty Masterson is running against Democrat state Sen. Cindy Holscher to replace term-limited Democrat Laura Kelly.
“This isn’t about any individual running for an elected office, myself included,” Masterson said during the rally. “It’s about the future of this state and this country. It’s about the next generation.”
The candidate reiterated a common theme of recent rallies, that those in attendance are the catalyst for a Republican victory if they mobilize their networks.
“You must get out and vote, and you must bring 10 of your friends because the stakes are that high, they really are,” Masterson said.
Rocker Ted Nugent boosted the energy in the arena with a surprise appearance, telling the audience his “life pivots upon God, family, country, Constitution, the Bill of Rights, the 10 Commandments, the Golden Rule, work ethic, law and order, self-defense, [and] private property rights.”
He commended the veterans in attendance and those around the world who served and those on duty defending the country.
“Politics is we the people thanking those flag-draped coffins for their sacrifice by voting for the beliefs they died for,” Nugent said.
“You’ve always seen me rock and roll on stage, but I’ve always stood up for the truth, logic, and common sense, the God-given individual freedoms that they died for that is guaranteed in that sacred United States Constitution.”
The president’s visit to Kansas marked his first in the state since a Topeka rally in 2018. He is in the midst of a midterm blitz to support Republican candidates, having rallied in Kentucky, Georgia, Montana, Ohio, and New York in recent days, with stops in North Carolina, South Carolina, Iowa, Florida, and another Georgia rally on the schedule, with more expected through Nov. 3.
GENERAL MOTORS
General Motors Shares Plunge 6% Despite $20 Billion Buyback Announcement And Earnings Beat
Tuesday, Oct 20, 2026 – 09:30 AM
General Motors shares are plunging more than 6% in premarket trading Tuesday, despite the automaker announcing a massive new $20 billion share repurchase program and reporting quarterly earnings that came in ahead of Wall Street expectations, according to Bloomberg News.
The selling comes as GM continues to grapple with a weakening U.S. auto market, where higher financing costs and pressure on household budgets have made it increasingly difficult to sell lower-priced vehicles. Demand for the company’s more expensive trucks and SUVs has held up considerably better, allowing GM to preserve profitability even as overall sales volumes come under pressure.
Bloomberg/Financial Post reports that for the third quarter, GM generated approximately $50 billion in revenue and $4.1 billion in adjusted operating profit, narrowly beating analyst expectations. Adjusted earnings of $3.70 per share also exceeded the $3.56 consensus estimate. Perhaps more importantly, automotive free cash flow jumped 40% to $5.9 billion.
That cash generation is helping fund an increasingly aggressive effort to return money to shareholders. GM’s latest $20 billion repurchase authorization follows a $6 billion program announced earlier this year and approximately $29.5 billion in buybacks completed since 2023. The newest authorization is expected to be used over several years.
Management also tightened its 2026 earnings forecast, now expecting adjusted operating profit between $14.5 billion and $15.5 billion, versus its previous projection of $14 billion to $16 billion. The midpoint of the guidance remains unchanged.
Looking ahead, GM is putting additional emphasis on its bread-and-butter pickup business, with redesigned Chevrolet Silverado and GMC Sierra trucks expected later this year. The company also plans to increase output of higher-end models equipped with V-8 engines, betting that wealthier consumers will continue paying a premium for larger vehicles.
The approach marks a notable change from GM’s previous enthusiasm for electric vehicles and autonomous driving, both of which have resulted in expensive setbacks. CEO Mary Barra has increasingly redirected attention toward established profit centers, while pursuing more targeted opportunities in vehicle software, advanced driver assistance and even defense-related manufacturing.
GM’s overseas operations, meanwhile, continue to struggle. Quarterly profit from China fell 60% from a year earlier to just $32 million.
The broader auto industry has undergone a significant reassessment over the past two years. After spending much of the early 2020s promising an accelerated transition to electric vehicles, several major manufacturers have scaled back EV investments, delayed launches and absorbed substantial losses as consumer adoption failed to match earlier expectations.
At the same time, persistently expensive vehicles, elevated interest rates and increasingly stretched consumers have complicated the outlook for traditional auto sales. The result is an industry increasingly focused on protecting margins, generating cash and selling the vehicles customers are actually willing to buy, rather than pursuing the ambitious growth narratives that dominated the sector just a few years ago.
END
COREWEAVE…AI
HSBC Destroys Goldman’s CoreWeave Upgrade: “The More It Invests, The More The Value Destruction”; Sees Crash To $39
HSBC reiterated its Reduce (sell-equivalent) rating and $39 price target on CoreWeave (CRWV) on October 19–20, 2026, arguing that the company’s returns on invested capital fall short of its borrowing costs—so additional investment destroys shareholder value—while its long-term earnings outlook sits far below consensus. This came right after Goldman Sachs upgraded the stock to Buy (with a cut price target of $106 from $139).
dealroom.co
Context and recent movesCoreWeave, a major “neocloud” provider of GPU capacity for AI workloads (with ties to Nvidia and large LLM customers), had plunged roughly 25% the prior week and about 43% since its August 2026 earnings report. The sell-off was driven mainly by credit-market stress: bond yields climbed into the 14–15% range, credit-default-swap spreads reached distress levels, and investors questioned whether the company could fund its heavy capital spending (tens of billions in debt already outstanding, with more needed for expansion) without value erosion.
tradingtips.com
Goldman analyst Gabriela Borges upgraded from Neutral to Buy on October 19, saying not all neoclouds are equal and CoreWeave ranks near the top. She argued the market was overestimating rises in the weighted average cost of capital (WACC) and underestimating unlevered IRR / returns per megawatt, citing tight GPU supply and the company’s ability to finance via asset-backed debt (DDTLs). The stock briefly bounced (up ~6–7% premarket) before giving back gains.
@matthew_sigel
HSBC’s bearish case
HSBC analyst Abhishek Shukla stuck with Reduce and the $39 target (implying ~36% downside from the ~$61 level around October 16). Key points from the note:
Value destruction: Estimated average ROIC for 2026–2030 is about 8.9%, below the cost of borrowing. “The more it invests, the more the value destruction.” CoreWeave has taken on >$50 billion in debt to fund infrastructure. tradersunion.com
Structural disadvantages vs. hyperscalers: HSBC expects CoreWeave to generate ~$12 million of revenue per MW annually in 2027 vs. $17–18 million for larger cloud providers. Neoclouds largely sell commoditized bare-metal GPU capacity to a few large customers; hyperscalers offer more differentiated services, shorter-term/higher-margin contracts, and broader customer bases. Long-term non-GAAP operating margin seen at 15–16% vs. management’s ~25% guidance. dealroom.co
Earnings far below consensus: 2028–2030 non-GAAP EPS estimates are 50–70% below Street numbers. Debt is projected to keep rising (HSBC sees net debt reaching ~$92 billion by end-2030 vs. a much lower near-term figure). High bond yields (14–15%) make speculative or short-term-contract capacity harder to finance and undercut assumptions of lower future interest rates. finance.yahoo.com
Demand and contract risks: Recent short-term deals (e.g., 3–6 month contracts at high annualized rates) provided a temporary boost, but moderating LLM provider growth and tighter credit could limit those opportunities.
The stock traded lower in premarket/early sessions on October 20 (down several percent at times) amid the reiteration.
invezz.com
Broader pictureAnalyst views remain split: many firms (JPMorgan, Cantor Fitzgerald, Wells Fargo, etc.) stay bullish with higher targets, citing backlog strength (~$100B+), demand durability, and asset-backed financing. HSBC has long been among the most skeptical. Risks center on financing costs, customer concentration, GPU depreciation/refresh needs, and whether AI compute economics ultimately support the capital intensity. This is not investment advice—neocloud/AI infrastructure names remain highly volatile and sensitive to credit conditions and AI spending trends.
END
Shocker: Teens Put Down Their Phones For Summer Camp, Mental Health Improves
Tuesday, Oct 20, 2026 – 04:15 AM
For two to three-and-a-half weeks, teenagers at a Maine summer camp traded their devices for outdoor activities and face-to-face friendships. By the end, their mental health had improved – with the largest gains among those who arrived struggling.
The findings add to research suggesting that relief from constant connectivity can produce benefits surprisingly quickly. They also raise a question – How much of it depends on what replaces the screen?
The study, published in Mental Health & Prevention, assessed 192 adolescents attending a device-free residential camp. Researchers included scientists from Sapien Labs and UC San Diego.
Participants’ composite mental-health scores improved by an average of 10.1 points between arrival and departure. Those starting with mental-health struggles recorded a median improvement of 27 points. These are changes on the study’s questionnaire scale, not percentage improvements or evidence that a psychiatric condition was cured.
The strongest gains involved adaptability and resilience. Campers also reported better focus and less worry and restlessness. Forty-four percent said they felt a stronger sense of belonging at camp than at school; 40% found making friends easier.
A session cost $4,900 to $7,900. Fewer than one in 10 campers arrived in the study’s distressed or struggling range, against more than half of US teens on the same measure, and nearly a quarter saw their scores fall by more than five points. Sapien notes that there was no control group – so we can’t know for sure whether removing devices caused the improvement, vs. how much came from exercise, sleep, friendship and the broader camp experience.
That said, there’s been similar research…
A 2024 Danish study in JAMA Network Open randomly assigned 89 families, including 181 children and adolescents, either to reduce recreational screen use or continue their usual habits. For two weeks, the intervention families handed over smartphones and tablets and were instructed to limit leisure screen use to three hours per week per person. Basic phones preserved calls and texting.
Children in those families showed greater improvement in behavioral difficulties, particularly emotional symptoms and peer problems, alongside better prosocial behavior. The overall effect was moderate by conventional statistical standards.
This provides stronger evidence that changing screen habits can help. Still, the children averaged roughly nine years old, parents knew which group they were in and supplied the behavioral ratings, and the experiment did not establish whether the benefits were lasting.
In a 2014 study led by UCLA researchers, 51 sixth-graders spent five days at an outdoor camp without screens. Compared with 54 schoolmates who continued their normal routines, campers improved more at recognizing emotions from facial expressions and other nonverbal cues. That measured a social skill, rather than depression or anxiety. The groups were not randomly assigned, and outdoor activities and greater personal interaction accompanied the screen break. Nevertheless, the finding suggests that even a brief change in daily habits can affect how children read other people.
A 2025 randomized trial in PNAS Nexus enrolled 467 people in an experiment blocking internet access on their smartphones for two weeks. Calls, texts and internet access through other devices remained available. Researchers found improvements in mental health, wellbeing and objectively tested sustained attention. Participants reported spending more time socializing in person, exercising and being outdoors. Just 119 participants met the prespecified compliance threshold of keeping the block active for at least 10 days. The average participant was 32, so these results cannot simply be transferred to teenagers.
There is also emerging evidence from the Maine camp itself. A September 2026 preprint examined brain-wave recordings from 30 campers and reported changes associated with some improvements in wellbeing. However, it was a small, uncontrolled pilot, had not been peer-reviewed, and came from the same broader camp project. Meanwhile, a 2025 SMART Schools study compared 1,227 adolescents across 30 English schools. Students at schools with restrictive phone policies used phones less during school, but did not report better mental wellbeing. Their overall weekday and weekend phone use was not significantly different.
Maine campers who said they exercised more at camp gained 17.4 points on average, against 4.8 for those who exercised less. Those who felt a stronger sense of belonging gained 15 points, against 5.8 for those whose sense of belonging fell. None of those gaps reached statistical significance, and the scores were taken on the last day of camp, so whether the gains lasted after campers went home is unknown.
END
KING NEWS
The King Report October 20, 2026 Issue 7851
Independent View of the News
THE REAL COST OF SOCIALISM IN AMERICA – The Council of Economic AdvisorsScoring the Economic and Fiscal Impact of the DSA Agenda October 2026If the DSA promises are financed by deficit spending—that is, by taking on additional government debt—CEA estimates that: • Interest rates on 10-year Treasury bonds would rise by 5.8 percentage points, likely breaching 10 percent, and dramatically increasing not only the government’s cost of borrowing, but also interest rates on mortgages and loans of hardworking Americans, families, and small businesses.• Inflation would increase to double-digit levels, with cumulative excess inflation of 130 to 160 percentage points over ten years, increasing costs for Americans.If the DSA promises are instead financed by increasing taxes on hardworking Americans, CEA estimates that: • The tax hikes would lower U.S. economic output (real annual GDP) by 14.6 percent in perpetuity. This is driven by fewer machines, fewer factories, and less intellectual property, and by a 16.2 percent fall in total labor hours – less employment.• US economic output could fall by about 19.2 percent per year, roughly $72.5 trillion in output lost over a decade, meaning fewer jobs and lower wages for Americans.• After-tax hourly wages for the average household shrink by 28.4 percent, an average of $22,000 in lost annual income in 2026 dollars… (Democratic Socialists of America = DSA)https://www.whitehouse.gov/wp-content/uploads/2026/10/The-Real-Cost-of-Socialism-In-America-Report.pdf Google AI Overview: Hedge funds and retail investors are locked in a classic market standoff, as institutional managers rapidly unwind crowded artificial intelligence positions while retail traders aggressively buy the dip. Driven by hot inflation data and rising bond yields, global hedge funds have sold off global AI stocks for six straight sessions, while retail investors poured a record $7 billion into the Direxion Daily Semiconductor Bull 3X ETF (SOXL) in a single week.Leveraged chip fund sees record $7 billion inflow amid selloffThe Direxion Daily Semiconductor Bull 3X ETF attracted more than $7 billion last week, marking the largest inflow on record for the fund, even as it lost approximately one-third of its value during the sameperiod. The Philadelphia Semiconductor Index declined for eight consecutive sessions through lastweek, representing its longest losing streak since October 2008…https://www.investing.com/news/stock-market-news/leveraged-chip-fund-sees-record-7-billion-inflow-amid-selloff-93CH-4957271 As noted in our Monday missive, traders aggressively bought ESZs and NQZs on Sunday night for the expected Monday Rally and the coming Fang and AI stock results, which begin today with Netflix. At 10:26 ET: MU +4.36%, NVDA 1.92%, SNDK +7.37%, TSLA +3.19%, AMD +3.59%, SPCX +2.83%, META -1.82%, INTC +4.9%, APPL +0.8%, AMXN +4.03%, CRWC +2.3%, MSFT 0.867%, SOX +2.8% The S&P 500 Index opened at 7702.77 (+43.33 pts). A pro dump that took the S&P down to 7684.79 at 10:04 ET. The index rallied to 7731.18 at 11:37 ET. It then fell on a US strike on an Iran Naval base. @FrankCurzio, midday Monday: Oil just jumped back above $111 a barrel after reports the US struck Iran’s Konarak Naval Base. It’s the first US strike on Iran in nearly 7 weeks. Brent (the global oil price) is now up 2.6% from today’s low. Hours earlier, Energy Sec. Chris Wright said pump prices had peaked. Crude fell overnight but rallied on Monday morning. This is the opposite of the usual trend of rallying during Asian and early European trading, and then someone knocks oil down during early US trading. A 5-wave decline, with a classic elongated 3 wave developed. The S&P fell to 7700.21 at 14:35 ET. Using the 7700 resistance, and perhaps trying to prevent momentum selling, someone instigated an afternoon rally that took the S&P 500 to 7711.97 at 15:25 ET. The afternoon rally occurred during a Trump impromptu press conference. DJT noted that he is trying to free hostages, and “we are negotiating with him on Ukraine… and on Iran… Zelensky is not helping matters much. I think he doesn’t want to stop it… I want to get the war stopped…” https://x.com/FoxNews/status/2112262112076874177 Trump added: Russia’s done very little for Iran, that’s positive… and it’s time for someone else to negotiate on behalf of Ukraine. DJT the US-Russia-China negotiation would occur in China. @clashreport: Q: Who ordered the interruption of Starlink in Ukraine? Trump: I don’t know who it was, but I’d like to find out.https://x.com/clashreport/status/2112264441098363132 @clashreport: Reporter: Zelensky says you’re supporting Putin by waiving these sanctions. Trump: I’m supporting stopping the war between Russia and Ukraine. Reporter: How does that help stop the war? Trump: Why? Because that’s what I do for a living. https://x.com/clashreport/status/2112270569005617586Trump is doing what he can to torpedo Zelinsky. The Ukraine leader will do the same to DJT. DJT blasted French President Macron for allowing unfettered 3rd World immigration into France and not doing anything to suppress their violence. Trump warned that Paris will be a “Muslim city very soon.” @realDonaldTrump: The Democrats gave us the Highest Inflation in History, and the Highest Prices to go with it and, as soon as l came into Office, they started screaming, “AFFORDABILITY.” They are the ones that created the Affordability Crisis. I’m the one who created the Greatest Economy and am bringing the prices down. It’s just another Fake News CON JOB! Oct 19, 2026, 3:05 PM @realDonaldTrump: New Mexico should immediately change its name to New America. We are not Mexico, we are the United States of America! The name would add great value and prestige to the State! Home Values and Incomes would rise, and you would be even prouder while saluting our beautiful American Flag! Maybe even the Crooked Elections that New Mexico is known for would become honest again!… Oct 19, 2026, 3:06 PM A selling onslaught appeared after 15:42 ET. The S&P 500 Index sank to 7688.45 (7700 breach) at 15:59 ET. The late manipulation closed the S&P 500 Index at 7690.73. NAHB/Wells Fargo Housing Market Index (Fell to a 14-year low in October)Builder confidence in the market for newly built single-family homes fell three points to 29 in October.Here are the readings for the three HMI indices in October:Current sales conditions fell two points to 33.Sales expectations in the next six months dropped five points to 32.Traffic of prospective buyers fell five points to 18.Signs of Market Cooling – The latest HMI survey found that 43% of builders cut prices in October, the highest share during the 2020-2026 period. The average price cut remained at 6% for the seventh consecutive month. Meanwhile, 65% of builders reported using sales incentives in October, the 19th straight month at least 60% of builders have done so…https://www.nahb.org/news-and-economics/housing-economics/indices/housing-market-index @Hedgeye: U.S. strategic oil reserve hits lowest level since 1982https://x.com/Hedgeye/status/2111157978908721320 @HedgeyeDJ: 283M barrels in the SPR, down from 406M a year ago. That’s roughly two weeks of U.S. demand sitting in the emergency fund… Positive aspects of previous session S&P 500 +0.41%, Nasdaq +1.11%, Nas 100 +1.17%, SOX Index +1.61%SP Consumer Discretionary +2.73%, Info Tech +1.19%, Comm Services +0.28%, Materials +0.08%Dec Brent -$0.47 at 109.39at 16:16 ET after hitting 110.69; Nov Gasoline -.05¢ at 16:20 ET Negative aspects of previous session DJIA -0.07%, DJTA -0.9%; Nov WTI +$2.43, Nov Diesel +3.61¢ at 16:15 ETSP Utes -1.97%, Real Estate -1.17%, Financials +0.79%, Industrials +0.65%, Energy -0.84%, Heath Care -0.61%, Consumer Staples -0.42%;USZs -17/32 (104 28/32) at 16:23 ET; 104 23 /32 , -22/32, low Ambiguous aspects of previous sessionAre these factors driving stocks lower: Inflation, Iran attack after 11/3, and Dem Midterm sweep?First Hour/Last Hour NYSE Action [S&P 500 Index]: 1st Hour: Down; Last Hour: DownPivot Point for S&P 500 Index [above/below indicates daily trend to day traders]: 7702.23Previous session (S&P 500 Index) High/Low: 7731.18 (11:35 ET); 7684.79 (10:04 ET) FBI smash huge voter fraud ring in California – days after feds issued ultimatum to stateFederal agents collared suspects in a slew of voter fraud cases Monday morning, chasing targets across California drawn from a list of more than 20,000 suspected noncitizens in the state who allegedly registered to vote in next month’s midterm election… LA’s top federal prosecutor Bill Essayli said the charges brought against Muñoz and other suspects sought Monday buttress the federal government’s claims of widespread voter fraud in California… “State-facilitated voter fraudis unacceptable in the United States of America,” Blanche said. “If found responsible in a court of law, the State of California will have seriously undermined confidence in our electoral system.”https://trib.al/fNpv8SuInside France’s ‘Chaos Inc’ franchise of communist groups, labor unions and global activists pushing radical-left riotshttps://trib.al/Mhnwn25France announces curfews in northern cities for Monday and Tuesday nightshttps://bit.ly/4dID3NI @NBCNews: French authorities acknowledge they have “lost control” in major citiesas widespread protests, violence and unrest grip the country, prompting calls for curfews to restore order. The unrest has also disrupted major landmarks, with the Louvre Museum in Paris closing after protesters announced a blockade, while a towering spire in Limoges collapsed in flames.https://www.nbcnews.com/world/europe/france-violence-riots-looting-paris-limoges-curfews-macron-protests-rcna604292 Babylon Bee: French Protesters Demand More Socialism to Fix Problems Caused by Socialism France, and most of Western Europe, need Charles Martel. Unfortunately, it has Macron. United Airlines CEO calls for national wealth tax, inheritance taxes approaching 100%Scott Kirby also defended charging passengers more for certain seating optionshttps://www.foxbusiness.com/fox-news-travel/united-airlines-ceo-scott-kirby-wealth-inheritance-tax? Reuters: @ErinBanco: Jared Kushner and Steve Witkoff plan to go to Norway tomorrow where they’re expected to meet Ukrainian officials as the admin tries to get closer to trilateral talks. On Sunday, Trump publicly endorsed Israeli Prime Minister Benjamin Netanyahu ahead of Israel’s elections. VP JD Vance has declined to take a position. Perhaps Vance does NOT want to upset his sponsor and facilitator, Tucker Carlson. Today – Bulls had everything going their way on Monday. ESZs and NQZ rallied sharply on Sunday night on buying for the expected Monday Rally; Fang/AI reporting season is about to begin; the usual Monday reports of ‘peace is at hand’ appeared; stock were oversold on a short-term basis; and the downward pressure of traders being too long calls for the October expiry on Friday was over. But stocks peaked near 11:35 ET, and there was a sharp decline late in the session of trader liquidation. Traders will play for Fangs/tech stock reporting season rally. They bought early on Monday night; but NQZs have declined 82.00 points from the 29,803.50 high at 18:04 ET. ESZs +10.25; NQZs -12.50, USZs -3/32, Nov WTI -$0.28, Nov Gas -0.06¢, ¥/$ 158.58 at 20:08 ET Expected earnings: GE 2.02, NFLX 0.82, RTX 1.78, CB 6.53, COF 5.45, MMM 2.41, GM 3.52, NOC 7.22, UAL 2.60, HAL 0.58, GPC 2.09, HAS 1.86, ALK 0.35, Expected Economic Data: Sept Housing Starts 1.265m, Permits 1.403m; Sept Pending Home Sales 0.3% m/m & -4.7% y/y S&P 500 50-day MA: 7705; 100-day MA: 7600; 200-day MA: 7274 (Close 7690.73, +0.41%)Nasdaq 100 50-day MA: 29,866; 100-day MA: 29,618; 200-day MA: 27,760 (Close 29,529.34, +1.17%) DJIA 50-day MA: 52,420; 100-day MA: 52,238; 200-day MA: 50,460 (Close 52,002.41 -0.007%) (Green is positive slope; Red is negative slope) @ValerieAnne1970: This Mom has EVERY right to be outraged… “You f’d up, CBS… this is my kid you used in your story without my permission. He does NOT have measles. This was his reaction to the MMR shot. Take it down. Now. Issue a retraction. It’s much easier than having to litigate a defamation case. I’II wait.” I still can’t believe CBS-DFW ran this story when they knew it was a lie. A local news station used aphoto of a toddler’s rash, labeled it measles, and put it in a story without the parent’s permission. Mom, Dawn Neufeld, said it wasn’t measles — it was the child’s reaction to the MMR shot — and had to publicly demand they take it down and issue a retraction. That’s not reporting. That’s using a kid’s vaccine-injured face to scare people. https://x.com/ValerieAnne1970/status/2111925284886994979Gaza teacher says she was threatened for refusing to teach kids to hate Jews: ‘We will cut your tongue’https://trib.al

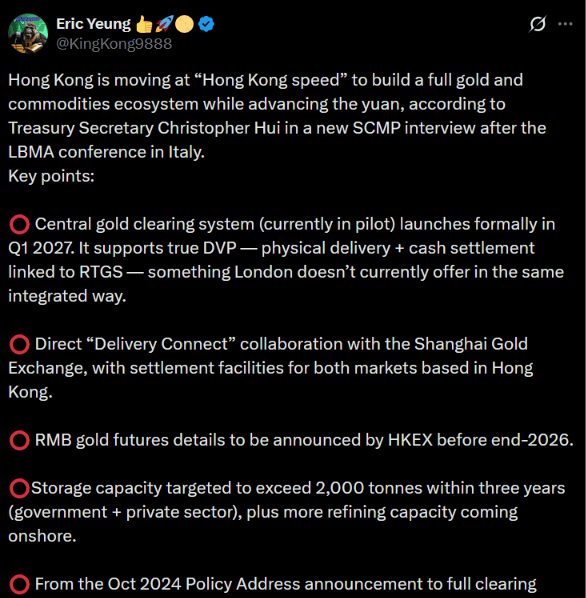
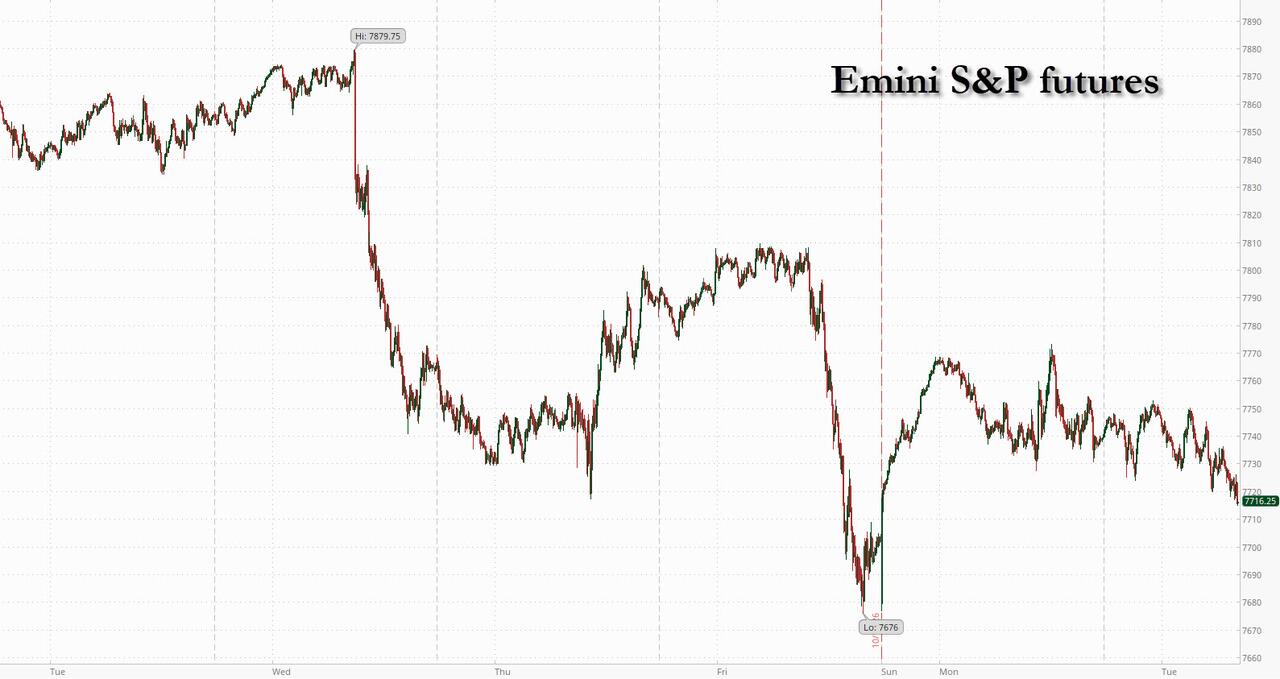
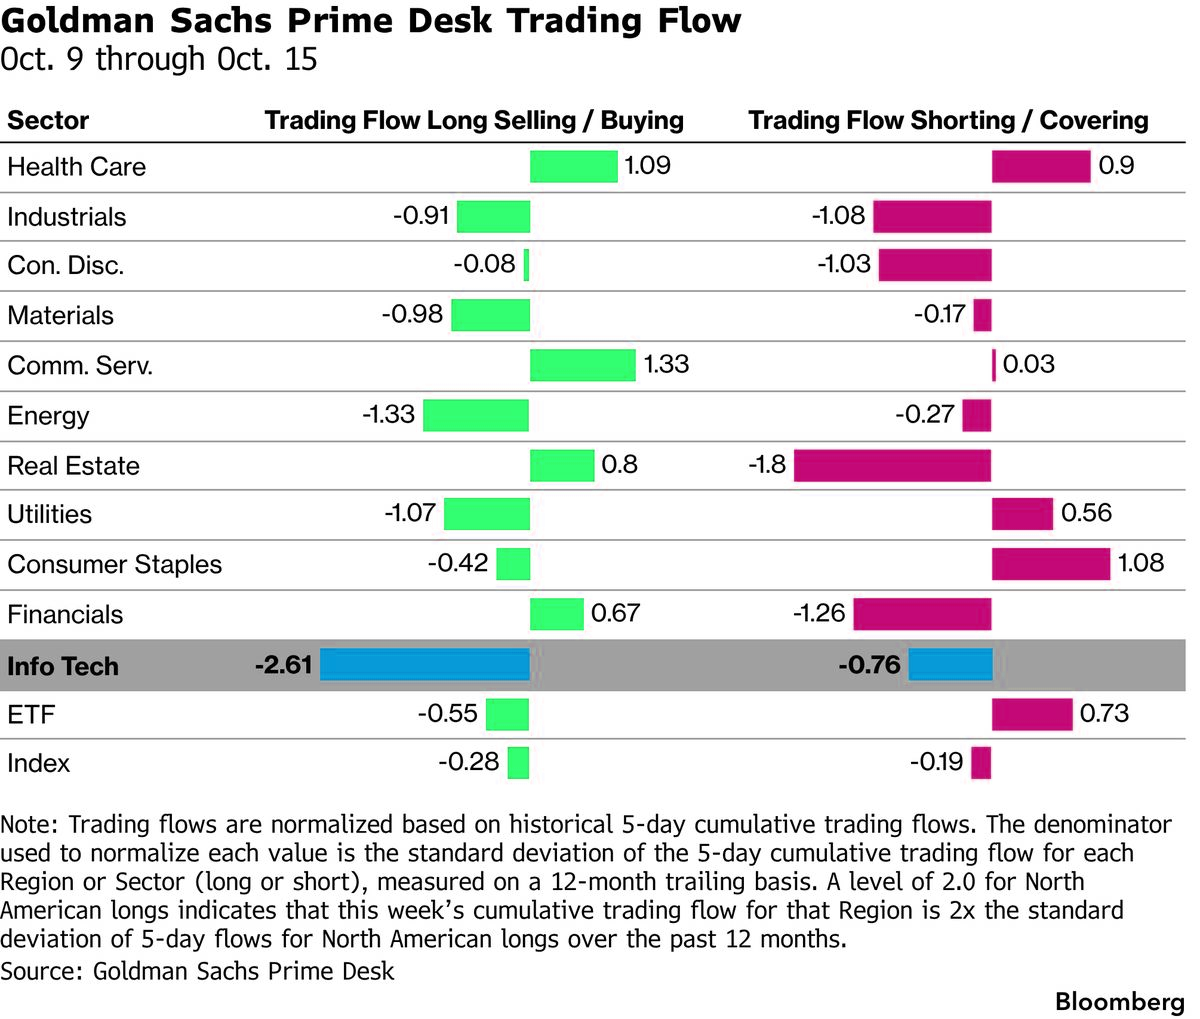
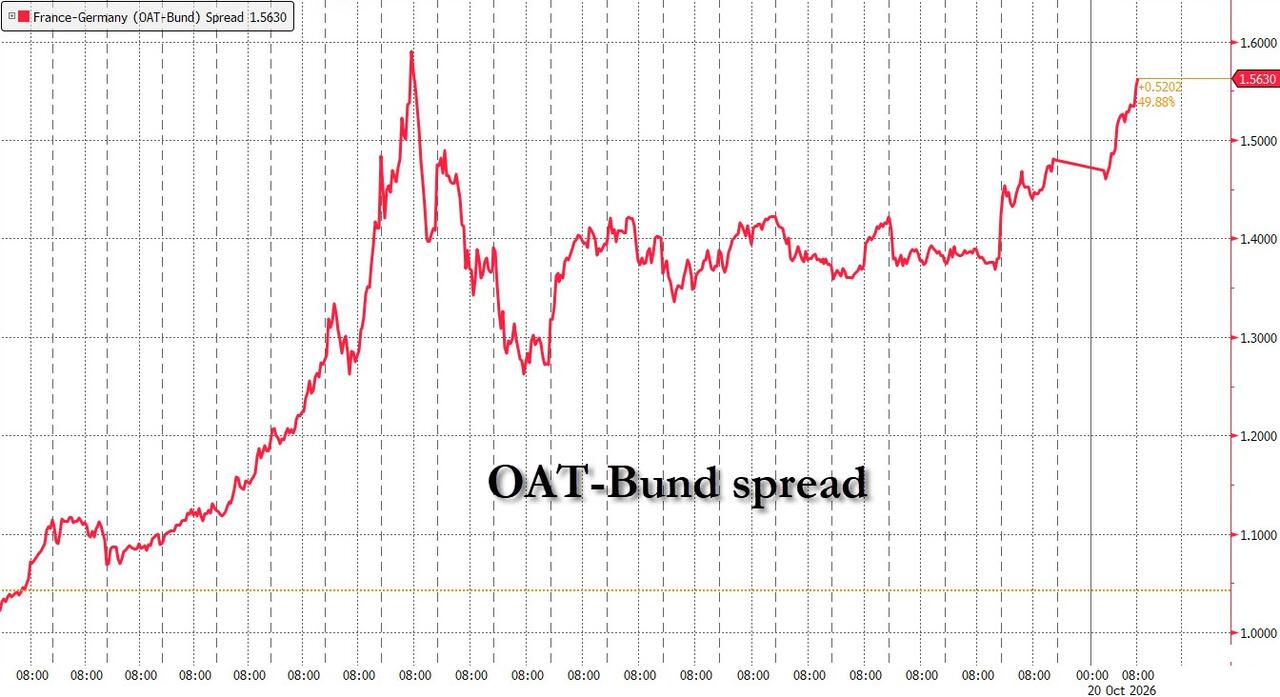
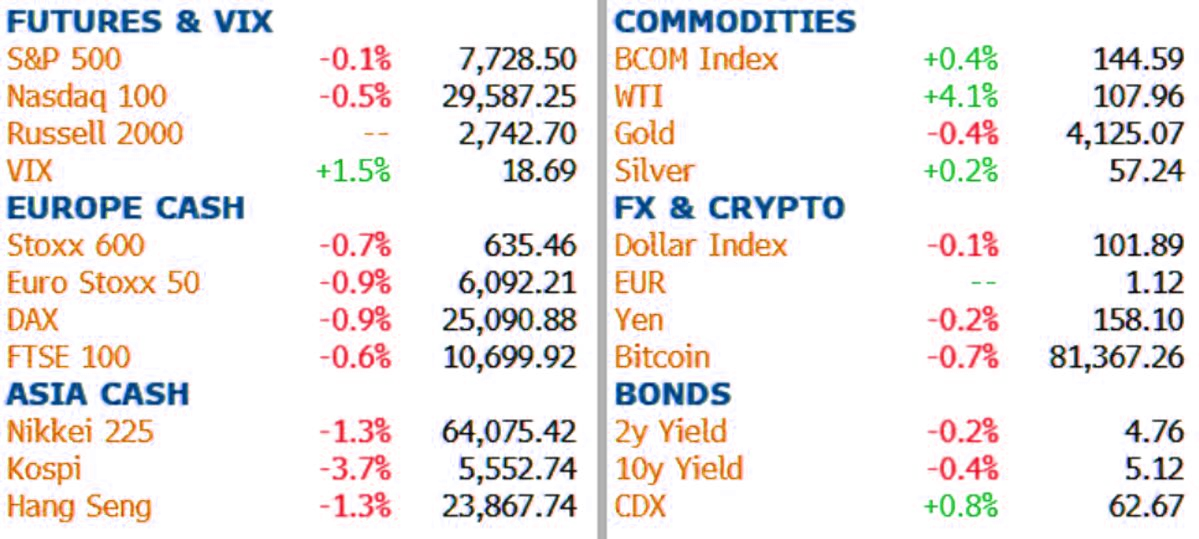
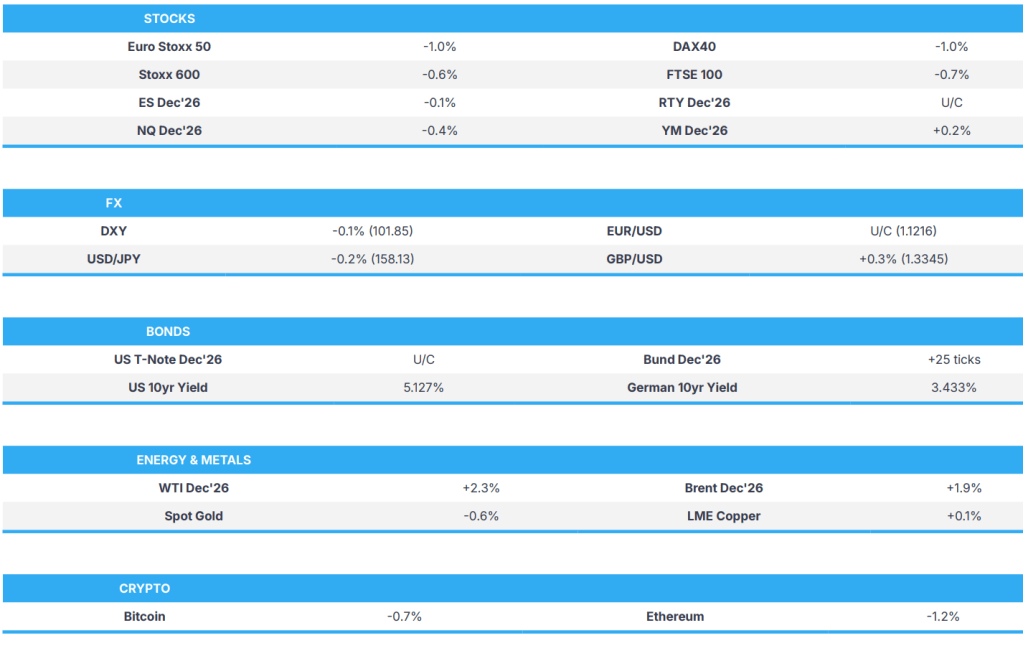

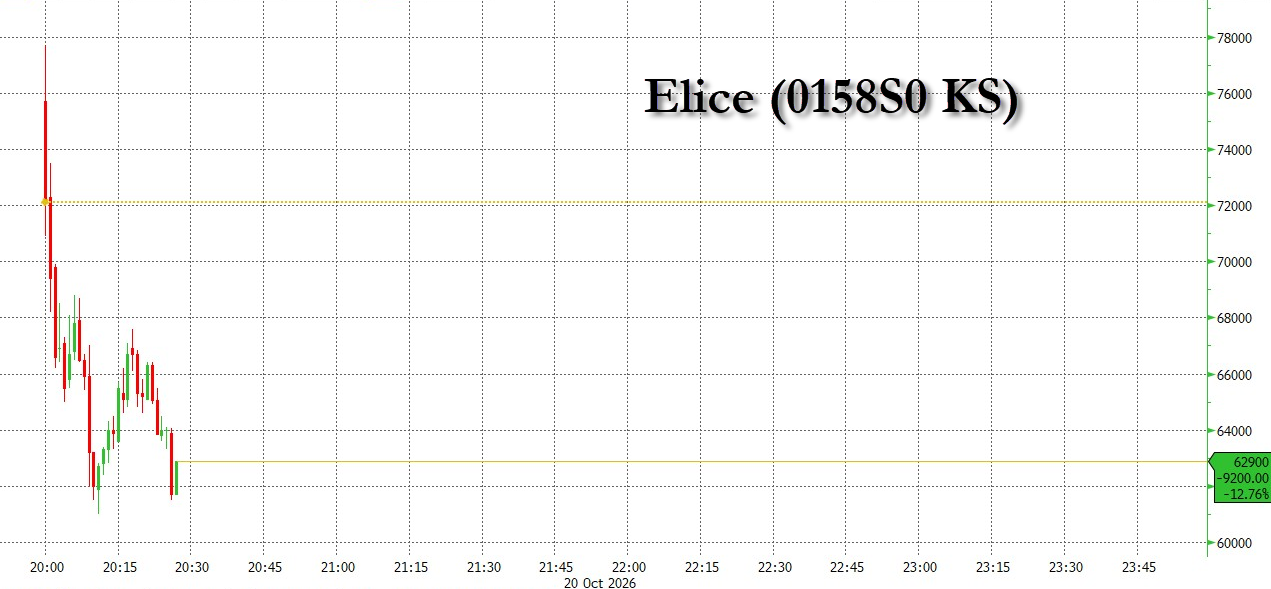
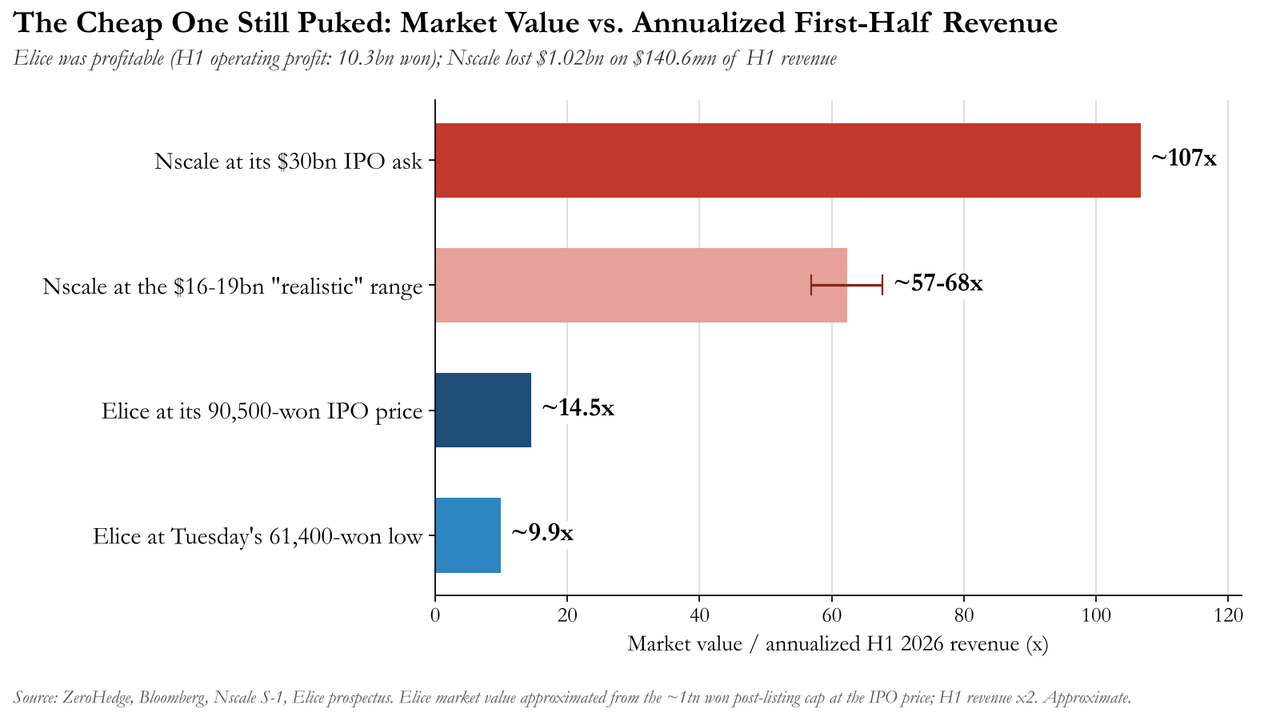
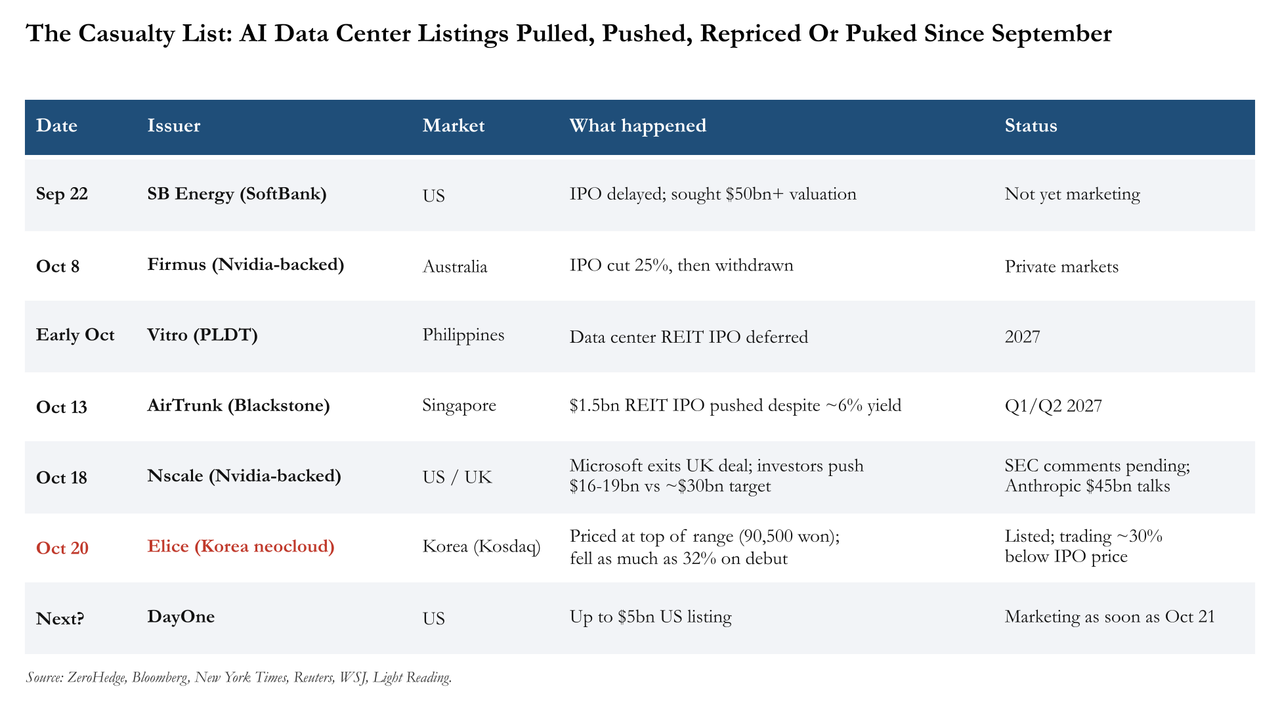
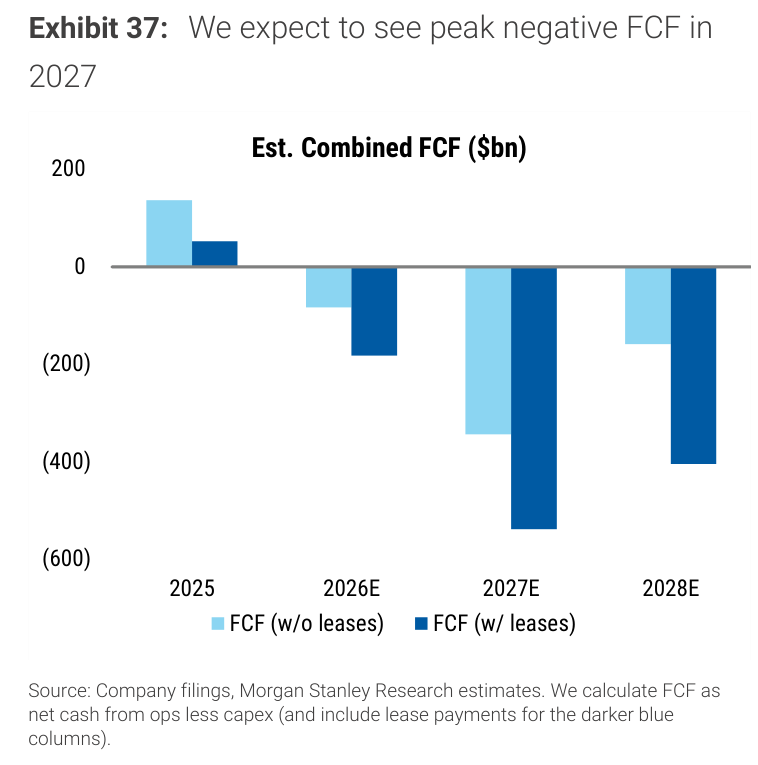
 modernity