EXCHANGE: COMEX
CONTRACT: OCTOBER 2026 COMEX 100 GOLD FUTURES
SETTLEMENT: 4,130.500000000 USD
INTENT DATE: 10/21/2026 DELIVERY DATE: 10/23/2026
FIRM ORG FIRM NAME ISSUED STOPPED
363 H WELLS FARGO SECURITI 7
624 H BOFA SECURITIES 66
686 H STONEX FINANCIAL INC 59
905 C ADM 4
991 H CME 18
TOTAL: 77 77
MONTH TOTAL 13,449
GOLD: NUMBER OF NOTICES FILED FOR OCT./2026: 77 CONTRACTs NOTICES FOR 7700 OZ or 0.2395 TONNES
total notices so far: 13,449 contracts FOR 1,344,900 OZ OR 41.8320 TONNES
SILVER NOTICES: 4 NOTICE(S) FILED FOR 20,000 OZ /
total number of notices filed so far this month : 3515 CONTRACTS (NOTICES) for 17.575 million oz
GLD
SHANGHAI CLOSED DOWN 55.00 PTS OR 1.48%
HANG SENG CLOSED DOWN 731.37 PTS OR 3.09%
Nikkei CLOSED DOWN 1551.24 PTS OR 2.40%
//Australia’s all ordinaries CLOSED DOWN 0.49%
//Chinese yuan (ONSHORE) CLOSED UP AT 6.6727
/ OFFSHORE CLOSED UP AT 6.6721 Oil UP TO 99.83 dollars per barrel for WTI and BRENT UP TO 112.12 Stocks in Europe OPENED ALL RED
ONSHORE USA/ YUAN// WITH YUAN TRADING 6.6727 OFFSHORE YUAN TRADING UP TO 6.6721 ONSHORE YUAN TRADING BELOW LEVEL // OFF SHORE AND UP ON THE DOLLAR)// / AND THUS STRONGER/OFF SHORE YUAN TRADING UP AGAINST US DOLLAR/ AND THUS STRONGER
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
| Gold | Ounces |
| Withdrawals from Dealers Inventory in oz | nil |
| Withdrawals from Customer Inventory in oz | 3 ENTRIES i) Out of Asahi: 27,558.994 oz ii) Out of Loomis 1607.550 oz (80 kilobars) iii) Out of Manfra: 32,151.000 oz (1000 kilobars) total withdrawal: 61,317.504 oz |
| Deposit to theDealerInventory in oz | 0 ENTRIES |
| Deposits to the Customer Inventory, in oz | DEPOSITS/CUSTOMER//gold 0 ENTRIES xxxxxxxxxxxxxxxx |
| No of oz served (contracts) today | 77 CONTRACTS 7,700 OZ 0.9113 TONNES OF GOLD |
| No of oz to be served (notices) | 29 Contracts 2900 OZ 0.0902 TONNES |
| Total monthly oz gold served (contracts) so far this month | 13,449 notices 1,344,900 OZ 41.832 TONNES |
| Total accumulative withdrawals of gold from the Dealers inventory this month | NIL oz |
| Total accumulative withdrawal of gold from the Customer inventory this month |
dealer deposits: 0
xxxxxxxxxxxxxxxxxxx
DEPOSITS:CUSTOMER ACCT
ENTRIES: 0
xxxxxxxxxxxxxxxxxx
comex withdrawals
3 ENTRIES
i) Out of Asahi: 27,558.994 oz
ii) Out of Loomis 1607.550 oz (80 kilobars)
iii) Out of Manfra: 32,151.000 oz (1000 kilobars)
total withdrawal: 61,317.504 oz
adjustments: 0
COMEX IS DRAINING GOLD
chaos inside the comex
THE FRONT MONTH OF OCT OI STANDS AT 106 CONTRACTS HAVING A LOSS OF 239 CONTRACTS.
WEDNESDAY WE HAD A NORMAL DELIVERY OF 1,342,000 OZ ( 41.1741 TONNES) OF GOLD STANDING FOR DELIVERY: TODAY: 1,347,800 OZ OR 41.922 TONNES FOR A GAIN OF 5800 OZ (0.1804 TONNES) OR 58 CONTRACTS UNDERWENT A SMALL QUEUE JUMP WHERE THESE BOYS WILL TRY THEIR LUCK BY TAKING DELIVERY ON THIS SIDE OF THE POND..
NOVEMBER LOST 86 CONTRACTS FALLING TO 3476
DECEMBER, THE LARGEST DELIVERY MONTH IN THE CALENDAR, ITS OI FALLS BY 2838 CONTRACTS DOWN TO 312.761.
.
We had 77 contracts filed for today representing 7700 oz
Today, 0 notice(s) were issued from J.P.Morgan dealer and 0 notices issued from their client or customer account. The total of all issuance by all participants equate to 77 contract(s) of which 0 notices were stopped (received) by j.P. Morgan dealer and 0 notice(s) was (were) stopped (received) by J.P.Morgan//customer account
To calculate the INITIAL total number of gold ounces standing for OCT /2026. contract month, we take the total number of notices filed so far for the month (13,449) to which we add the difference between the open interest for the front month of OCT (106 CONTRACTS) minus the number of notices served upon today 77 x 100 oz per contract) equals 1,347,800 OZ OR(41.922 Tonnes of gold) to which we add our two exchange for risk in Oct totalling 837 contracts for 83,700 oz or 2.60346 tonnes. Thus Oct standing for gold advances to 44.5254 tonnes
THUS: INITIAL total number of gold ounces standing for OCT. /2026. contract month,we take the total number of notices filed so far for the month (13,449) to which we add the difference between the open interest for the front month of OCT(106) contracts minus the number of notices served upon today 77 x 100 oz per contract) equals 1,347,800 OZ OR(41.922 Tonnes of gold) plus our first exchange for risk totalling 837 contracts//83700 oz//2.60346 tonnes//standing ADVANCES to 44.5254 tonnes
new total of gold standing in OCT becomes 44.5254 TONNES//
TOTAL COMEX GOLD STANDING FOR OCT.: 44.5254 TONNES WHICH IS NOW VERY STRONG FOR THIS NON ACTIVE DELIVERY MONTH OF OCT./
WEDNESDAY VOLUME: 160,337 poor
COMEX GOLD INVENTORIES/CLASSIFICATION
NEW PLEDGED GOLD:
241,794.285 oz NOW PLEDGED /HSBC 5.94 TONNES
204,937.290 OZ PLEDGED MANFRA 3.08 TONNES
83,657.582 PLEDGED JPMorgan no 1 1.690 tonnes
265,999.054, oz JPM No 2
1,152,376.639 oz pledged Brinks/
Manfra: 33,758.550 oz
Delaware: 193.721 oz
International Delaware:: 11,188.542 oz
total pledged gold: 1,746,271.131 oz 54.31 tonnes pledged gold lowers
total inventories in gold declining rapidly
total pledged gold: 1,746,271.131 tonnes oz 54.31 tonnes
TOTAL OF ALL GOLD ELIGIBLE AND REGISTERED GOLD 23,943,063.686 oz//
TOTAL REGISTERED GOLD 14,816,969.006 tonnes (460.86 tonnes)
TOTAL OF ALL ELIGIBLE GOLD 8,526,094.680 oz.
REGISTERED GOLD THAT CAN BE SERVED UPON 13,070,698 oz ((REG GOLD- PLEDGED GOLD)=
406.553 Tonnes //
total inventories in gold declining rapidly
SILVER COMEX
OCT DELIVERY MONTH
OCT 22
| Silver | Ounces |
| Withdrawals from Dealers Inventory | NIL oz |
| Withdrawals from Customer Inventory | 2 entries i) Asahi: 28,897.740 oz ii) CNT 59,418.840 oz total withdrawal 88,316.540 oz |
| Deposits to the Dealer Inventory | 0 ENTRY |
| Deposits to the Customer Inventory | ENTRIES: 1 i) Into Delaware 4029.400 oz total deposit: 4029.400 oz |
| No of oz served today (contracts) | 4 CONTRACT(S) ( 20,000 OZ) |
| No of oz to be served (notices) | 18 Contracts (0.090 MILLION oz) |
| Total monthly oz silver served (contracts) | 3515 contracts 17.575 MILLIONoz |
| Total accumulative withdrawal of silver from the Dealers inventory this month | NIL oz |
| Total accumulative withdrawal of silver from the Customer inventory this month |
DEPOSITS INTO DEALER ACCOUNTS
ENTRY:0
DEPOSIT ENTRIES/CUSTOMER ACCOUNT
1 ENTRIES:
i) Into Delaware 4029.400 oz
total deposit: 4029.400 oz
xxxxxxxxxxxxxxxxxxxxxxxxx
withdrawals:
2 entries
i) Asahi: 28,897.740 oz
ii) CNT 59,418.840 oz
total withdrawal 88,316.540 oz
adjustments : 5 all customer to dealer
a) Asahi 2,014,046.485 oz
b) Brinks 85,872.930 oz
c) CNT 280,466.600 oz
d) Manfra: 9990.292 oz
e) Stonex: 262,470.470 oz
xxxxxxxxxxxxxx
TOTAL REGISTERED SILVER: 100.698 MILLION OZ//.TOTAL REG + ELIGIBLE. 337.602 Million oz
registered silver dropping in numbers
CALCULATIONS FOR THE NEW STANDING FOR SILVER FOR OCT
FRONT MONTH: SILVER OPEN INTEREST CONTRACTS: 22 FOR A GAIN OF 4 CONTRACTS . WEDNESDAY WE HAD 17.645 MILLION OZ STAND: TODAY: 17.665 MILLION OZ FOR A GAIN OF 20,000 OZ (4 CONTRACTS). THUS A 4 CONTRACT QUEUE JUMP//WHERE THEY WILL NEITHER TAKE ANY DELIVERY ON THIS SIDE OF THE POND.
.
NOVEMBER LOST 51 CONTRACTS DOWN TO AN OI OF 1821
DECEMBER LOST 101 CONTRACTS UP TO AN OI OF 85,953
TOTAL NUMBER OF NOTICES FILED FOR TODAY: 4 or 20,000 oz
CONFIRMED volume WEDNESDAY; 37.655 // poor/
AND NOW OCT. DELIVERIES:
To calculate the number of silver ounces that will stand for delivery in OCT. we take the total number of notices filed for the month so far at 3515 X5,000 oz = 17.575 MILLION oz.
Then we take the difference between the front month of OCT. and the number of notices filed for today x 5000 to give us our standing
Thus the standings for silver for the OCT 2026 contract month: (3515 )Notices served so far) x 5000 oz + OI for the front month of OCT (22) minus number of notices served upon today ( 4 x 5000 oz) equals silver standing for the OCT .contract month equating to 17.665 MILLION OZ to which we add silver’s TWO exchange for risk for 450 contracts (2.25 million oz).. total standing REMAINS AT 19.915 million oz//. ( a very strong delivery month)
We must also keep in mind that there is considerable silver standing in London coming from our longs
There are ONLY 100.698 million oz of registered silver
JPMorgan as a percentage of total silver: 125.510/337.685 million: 37.02%
The record level of silver open interest is 234,787 contracts set on April 21./2017 with the price on that day at $18.42.
The previous record was 224,540 contracts with the price at that time of $20.44.
BOTH GLD AND SLV ARE MASSIVE FRAUD
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
OCT 22//2026/WITH GOLD DOWN $2.72 /HUGE CHANGES IN GOLD AT THE GLD. A DEPOSIT OF 1.14 TONNES OF GOLDINTO THE GLD//// //:/INVENTORY RESTS AT 1060.18 TONNES
OCT 21//2026/WITH GOLD UP $8.55 /NO CHANGES IN GOLD AT THE GLD.// //:/INVENTORY RESTS AT 1059.04 TONNES
OCT 20//2026/WITH GOLD DOWN $41.05 /NO CHANGES IN GOLD AT THE GLD. //:/INVENTORY RESTS AT 1059.04 TONNES
OCT 19//2026/WITH GOLD DOWN $19.65 /HUGE CHANGES IN GOLD AT THE GLD:A DEPOSIT OF 5.13 TONNES OF 0.29 TONNES OF GOLD INTO THE GLD/. //:/INVENTORY RESTS AT 1059.04 TONNES
OCT 16//2026/WITH GOLD UP $60.50 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 0.29 TONNES OF GOLD FROM THE GLD/. //:/INVENTORY RESTS AT 1053.91 TONNES
OCT 15//2026/WITH GOLD UP $60.50 /HUGE CHANGES IN GOLD AT THE GLD:A WITHDRAWAL OF 1.21 TONNES OF GOLD FROM THE GLD/. //:/INVENTORY RESTS AT 1054.20 TONNES
OCT 14//2026/WITH GOLD DOWN $66.25 /NO CHANGES IN GOLD AT THE GLD: //:/INVENTORY RESTS AT 1055.41 TONNES
OCT 13//2026/WITH GOLD DOWN $13.25 /HUGE CHANGES IN GOLD AT THE GLD: A DEPOSIT OF OF 2.281TONNES OF GOLD INTO THE THE GLD//: //:/INVENTORY RESTS AT 1055.411 TONNES
OCT 12//2026/WITH GOLD DOWN $24.20 /HUGE CHANGES IN GOLD AT THE GLD: A WITHDRAWAL OF 2TONNES OF GOLD OUT OF THE GLD//: //:/INVENTORY RESTS AT 1053.13 TONNES
OCT 9//2026/WITH GOLD UP $60.00 /HUGE CHANGES IN GOLD AT THE GLD: A WITHDRAWAL OF 4.562 TONNES OF GOLD OUT OF THE GLD//: //:/INVENTORY RESTS AT 1055.411 TONNES
OCT 8//2026/WITH GOLD UP $16.85 /HUGE CHANGES IN GOLD AT THE GLD: A DEPOSIT OF 3.703 TONNES OF GOLD INTO THE GLD//: //:/INVENTORY RESTS AT 1059.873 TONNES
OCT 7//2026/WITH GOLD DOWN $46.70 /NO CHANGES IN GOLD AT THE GLD:: //:/INVENTORY RESTS AT 1056.27 TONNES
OCT 6//2026/WITH GOLD UP $30.60 /HUGE CHANGES IN GOLD AT THE GLD:: A DEPOSIT OF 0.754 TONNES OF GOLD INTO THE GLD// //:/INVENTORY RESTS AT 1056.27 TONNES
OCT 5//2026/WITH GOLD DOWN $2.20 /HUGE CHANGES IN GOLD AT THE GLD:: A WITHDRAWAL OF 0.854 TONNES OF GOLD INTO THE GLD// //:/INVENTORY RESTS AT 1055.696 TONNES
OCT 2//2026/WITH GOLD DOWN $43.00 /HUGE CHANGES IN GOLD AT THE GLD:: A DEPOSIT OF 0.854 TONNES OF GOLD INTO THE GLD// //:/INVENTORY RESTS AT 1056.55 TONNES
OCT 1//2026/WITH GOLD UP $19.55 /HUGE CHANGES IN GOLD AT THE GLD:: A WITHDRAWAL OF 1.711 TONNES OF GOLD OUT OF THE GLD// //:/INVENTORY RESTS AT 1055.696 TONNES
SEPT 30//2026/WITH GOLD UP $7.80 /HUGE CHANGES IN GOLD AT THE GLD:: A DEPOSIT OF 2.847 TONNES OF GOLD INTO THE GLD// //:/INVENTORY RESTS AT 1057.407 TONNES
SEPT 29//2026/WITH GOLD UP $11.75 /NO CHANGES IN GOLD AT THE GLD //:/INVENTORY RESTS AT 1054.56 TONNES
SEPT 28//2026/WITH GOLD DOWN $150.20 /NO CHANGES IN GOLD AT THE GLD //:/INVENTORY RESTS AT 1054.56 TONNES
SEPT 25//2026/WITH GOLD DOWN $150.20 /NO CHANGES IN GOLD AT THE GLD //:/INVENTORY RESTS AT 1054.56 TONNES
SEPT 24//2026/WITH GOLD DOWN $18.70 /HUGE CHANGES IN GOLD AT THE GLD A DEPOSIT OF 1.43 TONNES OF GOLD INTO THE GLD://:/INVENTORY RESTS AT 1056.84 TONNES
SEPT 23//2026/WITH GOLD DOWN $58.00 /HUGE CHANGES IN GOLD AT THE GLD://:/INVENTORY RESTS AT 1055.41 TONNES
SEPT 22//2026/WITH GOLD DOWN $6.30 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 0.31 TONNES OF GOLD INTO THE GLD/:/INVENTORY RESTS AT 1055.41 TONNES
SEPT 21//2026/WITH GOLD DOWN $41.20 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 2.26 TONNES OF GOLD INTO THE GLD/:/INVENTORY RESTS AT 1055.10 TONNES
SEPT 18//2026/WITH GOLD UP $26.45 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 0.85 TONNES OF GOLD INTO THE GLD/:/INVENTORY RESTS AT 1052.84 TONNES
SEPT 17//2026/WITH GOLD UP $14.05 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 1.71 TONNES OF GOLD INOT THE GLD/:/INVENTORY RESTS AT 1051.99 TONNES
SEPT 16//2026/WITH GOLD UP $53.40 /HUGE CHANGES IN GOLD AT THE GLD://A DEPOSIT OF 2.86 TONNES OF GOLD INOT THE GLD/:/INVENTORY RESTS AT 1050.28 TONNES
SEPT 15//2026/WITH GOLD DOWN $19.45 /NO CHANGES IN GOLD AT THE GLD://A WITHDRAWAL OF 0.353 TONNES OF GOLD FROM THE GLD/:/INVENTORY RESTS AT 1047.420 TONNES
SEPT 14//2026/WITH GOLD DOWN $54.50 /SMALL CHANGES IN GOLD AT THE GLD://A WITHDRAWAL OF 0.353 TONNES OF GOLD FROM THE GLD/:/INVENTORY RESTS AT 1047.420 TONNES
SEPT 11//2026/WITH GOLD UP $1.05 /SMALL CHANGES IN GOLD AT THE GLD://A WITHDRAWAL OF 0.353 TONNES OF GOLD FROM THE GLD/:/INVENTORY RESTS AT 1050.277 TONNES
/
GLD INVENTORY: 1059.04 TONNES, TONIGHTS TOTAL GOLD INVENTORY
SILVER
OCT 22 WITH SILVER DOWN $2.72 : : SMALL CHANGES AT THE SLV: A WITHDRAWAL OF 632,000 OZ INTO SLV// // :INVENTORY RESTS AT 497.876 MILLION OZ
OCT 21 WITH SILVER DOWN $0.28 : : STRONG CHANGES AT THE SLV: A DEPOSIT OF 858,000 OZ INTO SLV// // :INVENTORY RESTS AT 498.508 MILLION OZ
OCT 20 WITH SILVER UP $0.68 : :NO CHANGES A WITHDRAWAL OF 943,000 OZ INTO OUT OF SLV// // :INVENTORY RESTS AT 497.650 MILLION OZ
OCT 16 WITH SILVER UP $1.19 : :MEGA HUGE CHANGES A DEPOSIT OF 4.374 MILLION OZ INTO THE SLV// // :INVENTORY RESTS AT 498.593 MILLION OZ
OCT 15 WITH SILVER UP $1.19 : :SMALL CHANGES A DEPOSIT OF 406,000 OZ INTO THE SLV// // :INVENTORY RESTS AT 494.219 MILLION OZ
OCT 14 WITH SILVER DOWN $3.25 : :SMALL CHANGES A WITHDRAWAL OF 135,000 OZ OUT OF THE SLV// // :INVENTORY RESTS AT 493.948 MILLION OZ
OCT 13 WITH SILVER DOWN $0.97 : :HUGE CHANGES A DEPOSIT OF 722,000 OZ INTO THE SLV// // :INVENTORY RESTS AT 493.813 MILLION OZ
OCT 12 WITH SILVER DOWN $0.51 : :HUGE CHANGES A DEPOSIT OF 722,000 OZ INTO THE SLV// // :INVENTORY RESTS AT 493.948 MILLION OZ
OCT 9 WITH SILVER UP $0.62 : :SMALL CHANGES A DEPOSIT OF 948,000 OZ INTO THE SLV// // :INVENTORY RESTS AT 493.226 MILLION OZ
OCT 8 WITH SILVER DOWN $0.74 : :SMALL CHANGES IN INVENTORY AT THE SLV:A WITHDRAWAL OF 532,000 OZ FROM THE SLV// // :INVENTORY RESTS AT 492.278 MILLION OZ
OCT 7 WITH SILVER DOWN $1.36 : :SMALL CHANGES IN INVENTORY AT THE SLV:A WITHDRAWAL OF 451,000 OZ FROM THE SLV// // :INVENTORY RESTS AT 492.910 MILLION OZ
OCT 6 WITH SILVER UP $0.31 : :NO CHANGES IN INVENTORY AT THE SLV: // :INVENTORY RESTS AT 493.361 MILLION OZ
OCT 5 WITH SILVER UP $0.87 : :NO CHANGES IN INVENTORY AT THE SLV: // :INVENTORY RESTS AT 493.361 MILLION OZ
OCT 2 WITH SILVER DOWN $0.74 : :NO CHANGES IN INVENTORY AT THE SLV: // :INVENTORY RESTS AT 493.578 MILLION OZ
OCT 1 WITH SILVER UP $0.57 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 1.400 MILLION OZ OUT OF THE SLV// :INVENTORY RESTS AT 493.578 MILLION OZ
SEPT 30 WITH SILVER DOWN $0.55 : :HUGE CHANGES IN INVENTORY AT THE SLV: A DEPOSIT OF 994,000 OZ INTO THE SLV// :INVENTORY RESTS AT 494.978 MILLION OZ
SEPT 29 WITH SILVER DOWN $0.58 : :SMALL CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 566,000 OZ FROM THE SLV// :INVENTORY RESTS AT 493.984 MILLION OZ
SEPT 28 WITH SILVER DOWN $2.91 : :SMALL CHANGES IN INVENTORY AT THE SLV: A DEPOSIT OF 0.542 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 494.436 MILLION OZ
SEPT 25 WITH SILVER DOWN $2.91 : :SMALL CHANGES IN INVENTORY AT THE SLV: A DEPOSIT OF 0.542 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 494.436 MILLION OZ
SEPT 24 WITH SILVER DOWN $0.96 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 0.813 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 493.533 MILLION OZ
SEPT 23 WITH SILVER UP $1.58 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 1.716 MILLION OZ FROM THE SLV// :INVENTORY RESTS AT 494.346 MILLION OZ
SEPT 22 WITH SILVER UP $0.10 : :NO CHANGES IN INVENTORY AT THE SLV: :INVENTORY RESTS AT 496.062 MILLION OZ
SEPT 21 WITH SILVER UP $1.04 : :HUGE CHANGES IN INVENTORY AT THE SLV: :INVENTORY RESTS AT 489.558 MILLION OZ
SEPT 18 WITH SILVER UP $1.04 : :NO CHANGES IN INVENTORY AT THE SLV: :INVENTORY RESTS AT 489.558 MILLION OZ
SEPT 17 WITH SILVER UP $1.10 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 1.265 MILLION OZ FROM THE SLV/ :INVENTORY RESTS AT 489.558 MILLION OZ
SEPT 16 WITH SILVER UP $0.95 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 813,000 OZ FROM THE SLV/ :INVENTORY RESTS AT 490.823 MILLION OZ
SEPT 15 WITH SILVER DOWN $0.16 : :HUGE CHANGES IN INVENTORY AT THE SLV: A WITHDRAWAL OF 813,000 OZ FROM THE SLV/ :INVENTORY RESTS AT 491.636 MILLION OZ
SEPT 14 WITH SILVER DOWN $0.91 : :NO CHANGES IN INVENTORY AT THE SLV:/ :INVENTORY RESTS AT 492.449 MILLION OZ
SEPT 11 WITH SILVER DOWN $3.50 : :NO CHANGES IN INVENTORY AT THE SLV:/ :INVENTORY RESTS AT 492.449 MILLION OZ
CLOSING INVENTORY 497.876 MILLION OZ OF SILVER
GOLD COMMENTARIES:
1.PETER SCHIFF//JOHN RUBINO//RAVEN
1 B // JAMES RICKARDS/MATHEW PIEPENBURG/ALASDAIR MACLEOD..
ALASDAIR MACLEOD…
3. CHRIS POWELL AND HIS GATA DISPATCHES
4. ANDREW MAGUIRE//KINESIS LIVE FROM THE VAULT/295
5. COMMODITY REPORT //SILVER
Goldman Says Silver “Still Stuck” After Billions Of Spec-Selling, Puts Panic-Bid
Goldman Sachs (via Robert Quinn’s silver futures note titled “Silver Futures: Still Stuck”) says silver remains range-bound and under pressure after heavy speculative selling, with put options seeing panic buying.
zerohedge.com
Key points from the ZeroHedge report (published ~Oct 22, 2026) and related coverage of Quinn’s analysis:
- Silver was trading around $57.48, down roughly 3% since early October (and sharply lower from its January 2026 peak above $115). zerohedge.com
- Speculative accounts (managed money and related categories) have sold about $2.2 billion of silver futures over the prior three weeks and are still selling. zerohedge.com
- This continues a broader pattern of large outflows. In late September alone, specs net-sold ~$1.6 billion (roughly half long liquidation and half new shorts)—the biggest weekly dump since February. CTA/trend-follower positioning has also swung sharply net short (a multi-billion-dollar reversal to levels not seen in at least a year). news.futunn.com
- Put options are being aggressively bid (“panic-bid”). Dealers who are short those puts can face hedging pressure that involves selling more silver futures as prices fall, which can reinforce the downward loop. @Wizard_Of_Alt
Context from Goldman’s earlier “Stuck” note (early October):
Bullish structural demand signals (AI/data-center and solar-related) have been improving, and physical tightness outside the U.S. (including Chinese dip-buying) has been noted. However, stronger USD and higher real rates have dominated, keeping speculative flows negative and the price “stuck.” Positioning (specs net longs roughly halved from the January peak, elevated put skew, low implied volatility relative to history) is described as extreme, creating potential asymmetry for a rebound if macro headwinds ease.
news.futunn.com
The ZeroHedge piece is largely paywalled beyond the summary, so the full Quinn note details (charts, exact flow breakdowns, options data) are not publicly available in the open excerpts. Spot/COMEX silver has recently traded in the mid-to-high $50s amid ongoing volatility.
END
COMMODITY GOLD/LBMA
LBMA Gold Scandal Breaks Wide Open
by VBL
Thursday, Oct 22, 2026 – 7:58
The LBMA’s Gold Standard Has an Enforcement Problem
Authored by GoldFix. All pictures via the NYT
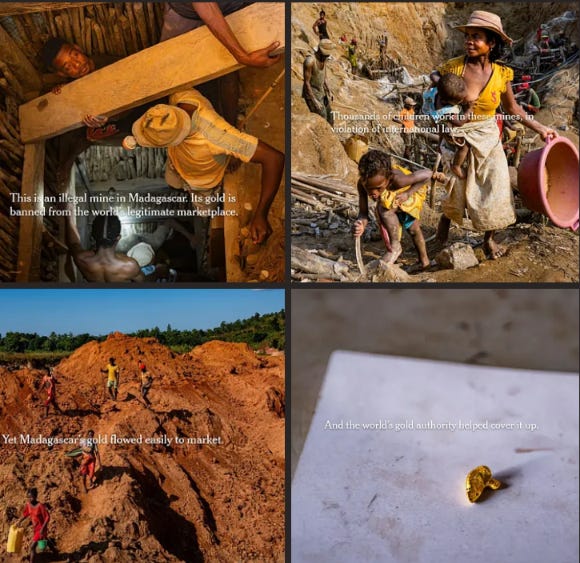
The New York Times investigation, How a Trillion-Dollar Industry Launders Illegal Gold, follows that gold into the legitimate market. It reports that when European scrutiny exposed problems with the sourcing paperwork, the London Bullion Market Association helped the refiner’s auditor revise and backdate the report.
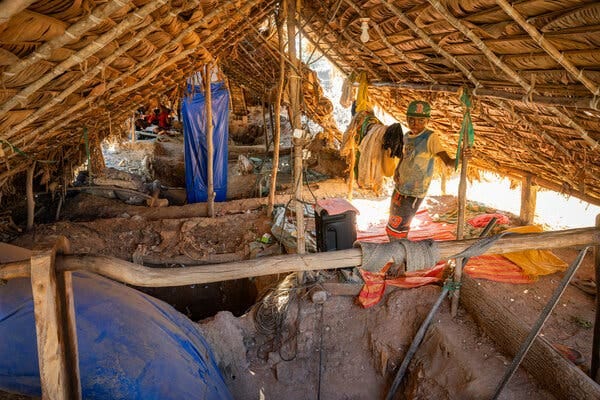
Madagascar had begun buying domestic gold for a national stockpile. Government records reviewed by the Times traced purchases to Madagold, where the reporter observed children working. Other metal came through intermediaries buying from informal mines.
Istanbul’s auditor filed paperwork claiming the company did no business with mines raising red flags, a declaration that allowed it to avoid inspections.
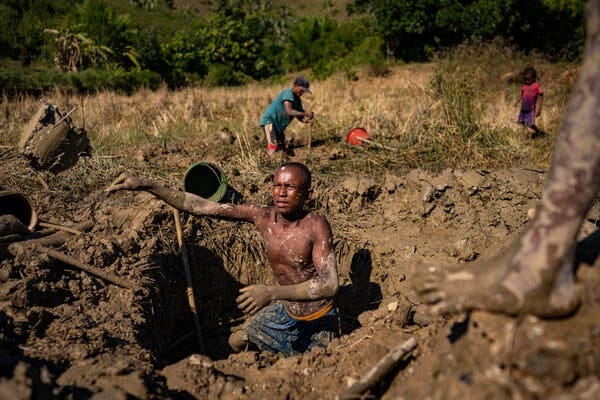
When discrepancies do surface, the refiners seldom face serious consequences.
The newspaper gives examples. An approved refiner received illegally mined Amazon gold and blamed its supplier; the LBMA took no action. After an Australian refiner bought gold tied to child labour and other abuses in Papua New Guinea, the association blacklisted the auditor and required management improvements. The refiner’s gold kept selling.
In 2021, the Times reports, the LBMA learned that Istanbul Gold Refinery had received gold originating from small-scale mines in Mauritania without disclosing it or reporting inspections. The association found that no rules had been broken.
In Madagascar’s case, an EU inspector asked how a refinery could process the country’s gold while reporting no red flags. The LBMA referred the problem to a compliance panel that included chief executive Ruth Crowell.
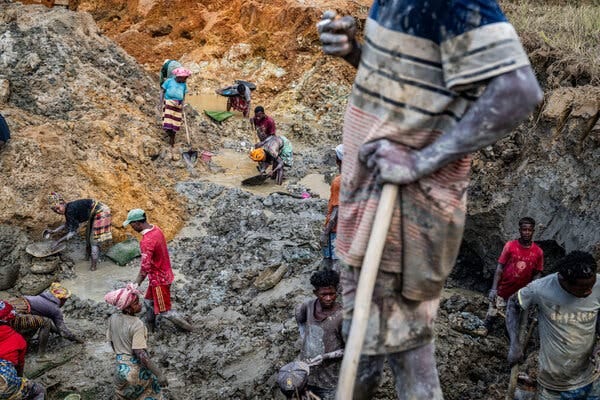
Association officials worked with the Istanbul Gold Refinery’s auditor to create a new report that made it seem like the refiner had disclosed the red flags from the beginning and had taken steps to scrutinize the supply chain, according to documents and the refiner.
The second report acknowledged that the company bought gold that originated in small-scale, red flag operations. But the report concluded that the mines “do not use child labor.”
The report was backdated, as if it had been filed in real time.
That backdated report remains on the L.B.M.A.’s website, with no indication of any alterations. The document serves as proof that Istanbul Gold Refinery processed only gold that had no connection to child labor or other abuses — claims that are undercut by what I saw in the mines.
The Times also found that the refiner relied on the seller, …
Continues here
END
YOUR EARLY CURRENCY VALUES/GOLD AND SILVER PRICING/ASIAN AND EUROPEAN BOURSE MOVEMENTS/AND INTEREST RATE SETTINGS THURSDAY MORNING.7:30 AM
SHANGHAI CLOSED DOWN 55.00 PTS OR 1.48%
HANG SENG CLOSED DOWN 731.37 PTS OR 3.09%
Nikkei CLOSED DOWN 1551.24 PTS OR 2.40%
//Australia’s all ordinaries CLOSED DOWN 0.49%
//Chinese yuan (ONSHORE) CLOSED UP AT 6.6727
/ OFFSHORE CLOSED UP AT 6.6721 Oil UP TO 99.83 dollars per barrel for WTI and BRENT UP TO 112.12 Stocks in Europe OPENED ALL RED
ONSHORE USA/ YUAN// WITH YUAN TRADING 6.6727 OFFSHORE YUAN TRADING UP TO 6.6721 ONSHORE YUAN TRADING BELOW LEVEL // OFF SHORE AND UP ON THE DOLLAR)// / AND THUS STRONGER/OFF SHORE YUAN TRADING UP AGAINST US DOLLAR/ AND THUS STRONGER
XXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXXX
ONSHORE YUAN: CLOSED UP TO 6.6727
OFFSHORE YUAN: UP TO 6.6721
1A.HANG SANG CLOSED DOWN 731.37 PTS OR 3.09%
1 B. SHANGHAI CLOSED DOWN 55.00 PTS OR 1.40%
2. Nikkei closed DOWN 1551.24 PTS OR 2.40%
WEST TEXAS INTERMEDIATE OIL UP TO 99.83
BRENT; 112.12
3. Europe stocks SO FAR: ALL RED
USA dollar INDEX DOWN 24 BASIS PTS TO 101.36// EURO RISES TO 1.1240 UP 6 BASIS PTS
3b Japan 10 YR bond yield:FALLS TO. +2.871 DOWN 1 FULL BASIS PTS/ VERY TROUBLESOME//Japan buying 100% of bond issuance)/Japanese YEN vs USA CROSS NOW AT 157.09… JAPANESE YEN NOW FALLING AS WE HAVE NOW REACHED THE ENDING OF THE YEN CARRY TRADE AGAIN AND THE REPATRIATION OF YEN DENOMINATED BONDS TRADING IN THE USA/EUROPE. JAPAN 30 YR BOND YIELD: 3.882 DOWN 2 FULL BASIS PTS
3c Nikkei now ABOVE 17,000
3d USA/Yen rate now well ABOVE the important 120 barrier this morning
3e Gold DOWN /JAPANESE Yen UP//CHINESE ONSHORE YUAN: UP (6.6727) AND OFFSHORE: UP AT 6.6721
3f Japan is to buy INFINITE TRILLION YEN worth of BONDS. Japan’s GDP equals 5 trillion USA. CENTRAL BANK OF JAPAN WILL NO LONGER DO QE.
Japan to buy 100% of all new Japanese debt and NOW they will have OVER 50% of all Japanese debt. GOVERMENT ASKED JAPAN PENSION FUNDS AND INSURANCE FUNDS TO BUY MORE JAPANESE BONDS AND REPATRIATE ALL FOREIGN BONDS.
3g Oil UP for WTI and UP for Brent this morning
3h European bond buying continues to push yields HIGHER on all fronts in the EU German 10yr bund YIELD UP TO +3.4043/ Italian 10 Yr bond yield UP AT 4.666/ SPAIN 10 YR BOND YIELD DOWN TO 4.122%
3i Greek 10 year bond yield UP TO 4.466%
3j Gold at $4091.00 /Silver at: 56.02 1 am est) SILVER NEXT RESISTANCE LEVEL AT $100.00
3k USA vs Russian rouble;// Russian rouble UP 0 AND 64/ 100 roubles/81.27
3m oil (WTI) into the 99 dollar handle for WTI and 112 handle for Brent/
3n Higher foreign deposits moving out of China// huge risk of outflows and a currency depreciation. This can spell financial disaster for the rest of the world/
JAPAN ON JAN 29.2016 CONTINUES NIRP. THIS MORNING RAISES AMOUNT OF BONDS THAT THEY WILL PURCHASE UP TO .5% ON THE 10 YR BOND///YEN TRADES TO 157.05 // 10 YEAR YIELD AFTER FIRST BREAKING .54% LAST YEAR NOW EXCEEDS THAT LEVEL TO 2.871% DOWN 1 BASIS PTS STILL ON CENTRAL BANK (JAPAN) INTERVENTION//YEN CARRY TRADE NOW UNWINDING//YEN BOND TRADING OVERSEAS TO BE REPATRIATED.//JAPAN 30 YR: 3.882 DOWN 2 PTS..: USA/SF this 0.8208 as the Swiss Franc . Euro vs SF: 0.9225
USA 10 YR BOND YIELD: 5.075 DOWN 7 BASIS PTS…NOW ABOVE 5.00%
USA 30 YR BOND YIELD: 5.377 DOWN 6 BASIS PTS/
USA 2 YR BOND YIELD: 4.770 DOWN 5 BASIS PTS
USA DOLLAR VS TURKISH LIRA: 49.63 UP 3 BASIS PTS/LIRA GETTING KILLED//IDIOTS FOR SELLING GOLD AND USA DOLLAR RESERVES.
10 YR UK BOND YIELD: 5.3787 DOWN 1 PTS
30 YR UK BOND YIELD: 5.777 DOWN 1 BASIS PTS
10 YEAR FRENCH BOND YIELD; 5.091 % //UP 11 BASIS PTS
10 YR CANADA BOND YIELD: 3.8650 DOWN 3 BASIS PTS
5 YR CANADA BOND YIELD: 3.595 DOWN 3 BASIS PTS.
1a New York Opening report
Futures Slide As Market Runs Out Of AI Patience, Oil Jumps On Saudi Attacks
Thursday, Oct 22, 2026 – 08:25 AM
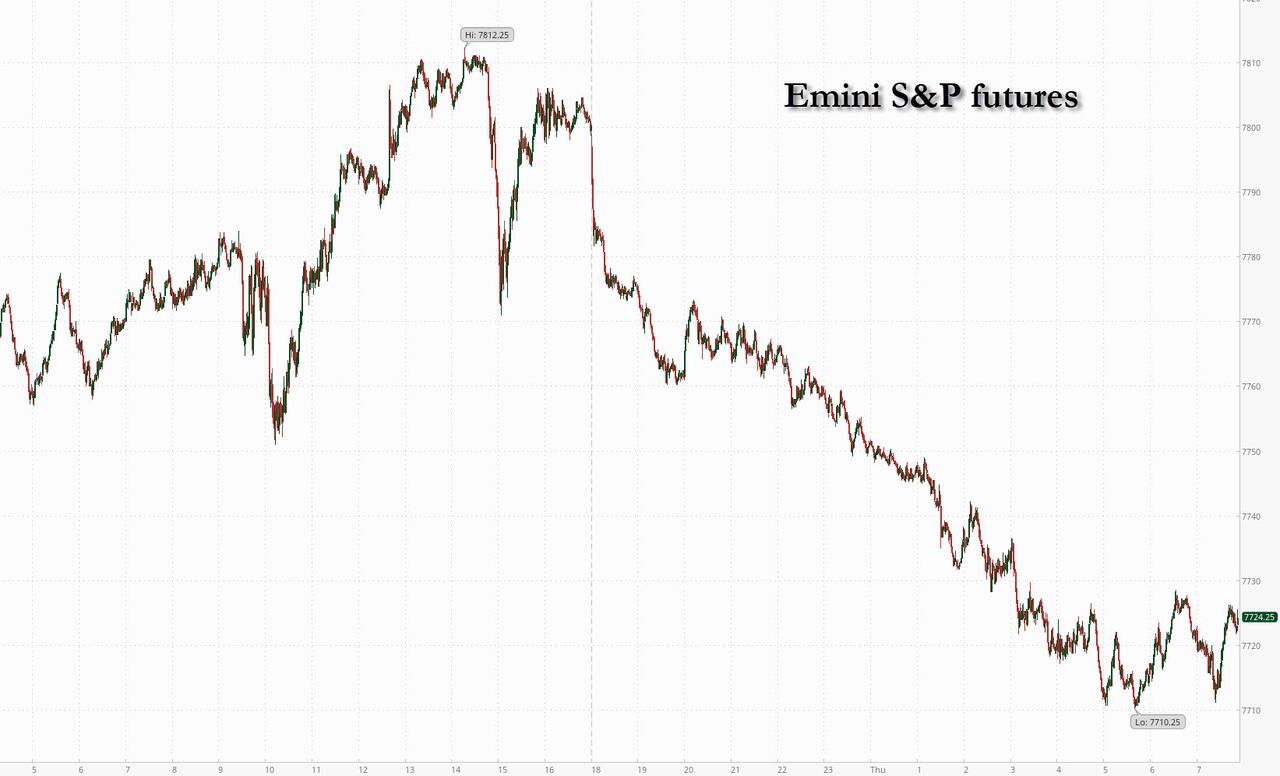
US futures are lower as the AI trade discovered that there is no right answer on capex: Meta spent more, Tesla spent less, and the market slammed both (after an initial kneejerk bounce), while a fresh wave of deadly attacks on Saudi Arabia, a US-ordered departure of diplomats from the kingdom and an NYT report that the US and Israel have drawn up plans for renewed strikes on Iran after the midterms sent Brent back above $112; as a result the flight to quality is back on, with 10Y yields sliding 9bps to 5.03% even as oil jumps and French bond yields soar. As of 8:00am ET, S&P futures are 1.0% lower at 7,720.75 while Nasdaq futures are down 1.7% at 29,507.50 and Dow futures are 0.6% lower. Wednesday’s session closed near its highs, with the S&P rising 0.6% to 7,757 for a third straight gain and closing within 1% of its record high, as the SpaceX blowout revived the AI trade. In premarket trading, all Mag 7 names are red led by Tesla, which drops 4.4% after cutting its 2026 capex target to about $20 billion from more than $25 billion, while Meta reversed an after-hours gain of as much as 5% to trade down about 1.5% as investors focused on its hedged 2027 spending commentary (as we noted last night, the stock erased most of its gains after the CFO warned “significant investment” will raise serving costs); Lam Research tumbles 8% on a soft forecast, dragging chipmakers including AMD, Broadcom and Intel. The day’s driver is oil (again): Brent rose as much as 3.3% to $112.43 and WTI briefly topped $100 after two attacks on an Aramco oil field and an airport in Saudi Arabia’s Eastern Province killed at least three people, Aramco told staff to evacuate its Dhahran headquarters, and the IRGC Navy warned US bases could be targeted if Washington keeps “encouraging” ships through the Strait of Hormuz. Treasuries are bid across the curve in a bull steepener as AI doubts and another spike in French yields drive a haven bid; the OAT-Bund spread blew out by as much as 18bps to 177bps, the widest since 2011. The yen and Swiss franc lead G10 FX, with EUR/JPY at the lowest in almost a year, while the Bloomberg dollar index is little changed. Gold is down 1.3% near $4,085 and silver is down more than 3%, refusing to play haven, copper slides with the AI trade, and Bitcoin slipped below $82,000. US economic data slate includes weekly initial jobless claims (8:30am), the September leading index (10am) and the October Kansas City Fed manufacturing index (11am), and Treasury auctions resume with a $26 billion 5-year TIPS new issue (1pm). The Fed is in its blackout period ahead of next Wednesday’s decision.
In premarket trading, all Mag 7 names are lower: Tesla (TSLA) drops 4.4% after the electric-car maker cut its spending plans, following capital investment that trailed expectations last quarter (Nvidia (NVDA) -2%, Alphabet (GOOGL) -2%, Amazon (AMZN) -2%, Meta Platforms (META) -2%, Microsoft (MSFT) -0.9%, Apple (AAPL) -0.2%)
- Chipmakers and other AI-related firms slide after reports from Tesla, Lam Research and IBM underwhelmed. Decliners include AMD (AMD) -4%, Broadcom (AVGO) -3%, Intel (INTC) -4%. The mood is weighing on other growth sectors and pushing crypto names lower
- American Airlines (AAL) slumps 4% after issuing a broad range for its fourth-quarter loss prediction, highlighting how the industry is struggling to map out its performance amid persistently high fuel prices.
- Biohaven (BHVN) soars 53% after the FDA said company’s new drug application resubmission for Vyglxia has been accepted for review.
- CSX (CSX) inches 2% higher after the railroad reported earnings per share for the third quarter that beat the average analyst estimate.
- The company is benefiting as trucking gets more expensive, pushing shippers to use its intermodal offering instead of having goods carried entirely by truck.
- Gentherm (THRM) falls 6% after the the automotive supplier reported adjusted earnings per share below analyst expectations in the third quarter.
- International Business Machines (IBM) falls 5% after posting third quarter results.
- Kinder Morgan (KMI) gains 2% after formally committing to building a $4.2 billion pipeline that will haul fuel across West Texas and the Panhandle to help power a data center complex.
- Lam Research (LRCX) falls 7% after the semiconductor capital equipment company gave a forecast for adjusted second-quarter earnings that was slightly weaker than expected at the midpoint of the range.
- Lockheed Martin (LMT) rises 4% after lifting its full-year outlook as the company’s missile systems portfolio was buoyed by rising global defense spending.
- Pool Corp. (POOL) gains 4% after third quarter results topped expectations.
- Procter & Gamble (PG) gains 3% after sales and profits beat Wall Street expectations, showing the Tide-owner’s limited price hikes that are successfully drawing constrained customers have not come at the expense of earnings.
In other corporate news, Meta did its best to change the subject from capex, announcing a one-time dividend of non-voting Class C shares that effectively amounts to a 2-for-1 split and, per Bloomberg, gives Mark Zuckerberg shares he can sell without giving up control as a proposed California wealth tax looms; Tesla CEO Elon Musk wants to combine Tesla and SpaceX in a $3.7 trillion deal and is rushing to get it done before Trump leaves office, according to Bloomberg; the US signed a deal with Lockheed Martin for a minimum of 850 F-35 jets; Comcast reported 3Q adjusted EPS of $1.07 vs an estimate of 98c; Blackstone’s 3Q distributable income of $1.32 a share beat the $1.26 estimate; American Airlines sees a 4Q adjusted loss of 50c to $1.10 a share, vs an estimated loss of 49c; Spotify sees 4Q MAUs of 818 million, a hair below the 819.08 million estimate; Barclays is cutting 5,000 jobs, about 5% of headcount, as it adopts AI across the bank; EQT’s bid for Qiagen is now firm at €46.50 a share in cash; and Chinese AI startup DeepSeek raised about 100 billion yuan ($15 billion) in its latest fundraising round.
Bloomberg sums up the overnight mood succinctly: “AI nerves are back.” The bar for an AI beat has moved from ambition to monetization, and the market is no longer giving credit for spending plans alone: Meta lifted the bottom of its 2026 capex range to $135 billion from $130 billion and guided above consensus, Tesla cut its capex target after third-quarter spending came in at $4.73 billion vs $7.95 billion expected, and both stocks are lower. Spend more or spend less, the market frowned either way. IBM swung from a 5% gain to a 4.6% loss in late trading even after saying slipped infrastructure deals had come back, a reminder that software is no safe corner of the AI trade either. All of this comes as hyperscaler credit spreads sit at record wides (as we noted in last night’s wrap) and as Ken Griffin calls AI “almost certainly” a bubble.
“Markets are basically telling us we are moving on from trading AI vibes and narrative to now requiring a pretty high bar for what an earnings beat looks like,” said Kaanhari Singh, APAC head of equity derivatives sales at Barclays, on Bloomberg TV. “That’s both in terms of capex forward guidance, but also for the path of monetization.”
Tesla and Lam results put “the AI confidence back in the air again, dragging a few other semi names lower,” said Anna Wu, an investment strategist and founder of Floodlines Research.
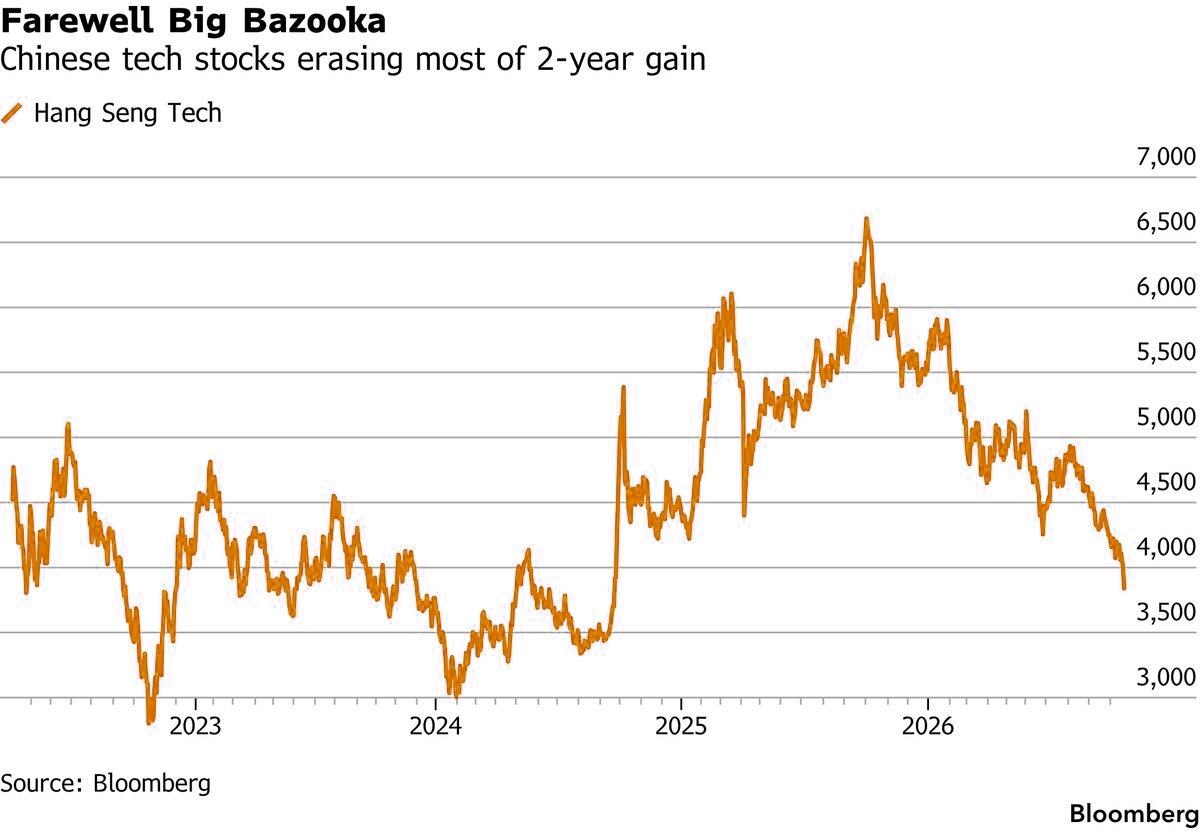
The pain was most acute in Asia, where the CSI 300 briefly entered a bear market, down 20% from its June highs, and Chinese e-commerce names including Alibaba slumped after the market regulator urged platforms to tighten product quality controls. Chinese tech stocks are now erasing most of their 2-year gain.
JPM’s Market Intel desk calls it a “narrative shift overnight amid geopolitics concerns”: Wednesday’s session closed near its highs with AI/Tech and Momentum leading, but that tone reversed overnight. Beyond the NYT Iran headline, the desk says underlying price action and trading desk feedback point to “the still fragile narrative around AI financing concerns and the lack of conviction / re-grossing from the recent tech reversal.” The team stays Tactically Bullish, favoring cyclicals outside tech while selectively buying tech weakness in semis and memory. JPM specialist Mark Schilsky called Meta’s quarter in line, with a Q4 revenue guide that is “decidedly better than expected,” but noted the 2027 commentary “will leave some investors wanting” and that the new Class C shares likely mean an equity raise is coming, just not until early 2027: “The overhang lives on!” Meanwhile, JPM credit trader William Jarvis notes the bank’s HY AI basket is trading at all-time wides, 97bps wider than its July peak, mostly led by CoreWeave, with Oracle widening far more than the rest of IG (as Barclays warned, the AI credit flush won’t be the last).
Over at Goldman, Rich Privorotsky flagged the capex whiplash: “Tesla actually cut FY capex guidance from >$25bn to ~$20bn, completely out of sync with what SpaceX was telling us earlier this week. Could be sequencing, but the market doesn’t like capex going backwards.” He also notes the NYT report means “we’ve now effectively stapled another potential escalation event to the calendar” right after the midterms, and that prime data shows one of the most pronounced net tech reductions in recent memory. The GS desk adds that hedge funds have heavily net sold global equities in October, with short sales outpacing long buys about 5 to 1, and short leverage at the 99th percentile; with positioning this defensive, the derivatives desk sees right-tail hedges as historically cheap. In Asia, Goldman’s prime book shows L/S managers down 1.5% intraday and 8.6% month to date.
In Europe, the French bond rout that has carried out London macro traders deepened: France’s 10Y yield hit 5.14% and its risk premium over bunds widened to 177bps, the most since 2011, as the government prepares to deploy soldiers to free up police for Saturday’s protests and Paris luxury boutiques brace for more unrest. Goldman has built a fragmentation alarm to gauge how close Europe is to another “whatever it takes” moment; M&G is not worried just yet.
“We don’t believe that France needs to be bailed out. There’s no concern about this,” said M&G Asset Management CEO Joseph Pinto on Bloomberg TV. “We believe it’s a sound and solid country. It just needs to act on its budget and provide something that reassures markets.”
In Europe, the Stoxx 600 is down 0.9% at 638.75, with 445 members down and 146 up, as mixed results from US tech revive concerns about the AI trade. Miners and banks are the worst performing sectors, while telecoms, food and beverage and health care are the only gainers; JPM notes semis and electrification baskets are among the top underperformers, with only defensives and rate-sensitive baskets in the green as beta and momentum are sold. Hermès slumps after its Asia-Pacific sales disappointed, while UCB soars after raising guidance. Here are the biggest European movers:
- Nestle gains as much as 2.7% after the company reported real internal growth for the nine month period of +1.9%, which was welcomed by analysts who noted “broad-based” improvement in RIG across different divisions and regions of the business.
- UCB shares rally as much as 16% after the biopharma company raised its guidance, with analysts expecting material upgrades to consensus estimates.
- Verisure shares rise as much as 17% in Stockholm after the Financial Times reported that CVC is exploring a bid to take the security group private.
- Moncler shares rise as much as 2.8% after the Italian luxury company reported third-quarter revenue that beat consensus estimates.
- Rentokil shares rise as much as 9.5% after the British facility management company reported revenue for the third quarter of $1.89 billion.
- Hermès shares fall 9% after the Birkin bag maker’s third-quarter revenue fell short of analyst estimates.
- Besi shares drop 4.3% after reporting 3Q orders that beat consensus estimates and pushing back on concerns that ASML would be a competitive threat to its flagship hybrid bonding technology.
- Roche shares slip as much as 1.5% after the pharmaceutical firm reported third-quarter results. Analysts note the sales beat reflects a benefit from the integration of its Enterprise Resource Planning IT system.
- SEB shared declined as much as 5.2% after the lender reported earnings that analysts say are weak and announced a pause in buybacks after Sweden’s financial regulator temporarily raised its capital requirements.
- Yara shares fall as much as 4.7% after the fertilizer producer reported adjusted Ebitda for the third quarter that missed the average analyst estimate.
- Sainsbury shares fall as much as 4.4% after the British supermarket reported earnings for the first half, including revenue which fell short of expectations.
- Digital Network falls as much as 18% after the founder sold a nearly 20% stake in Polish advertising-services company through an accelerated bookbuild at a 19% discount to the previous close, upsizing the deal from an initially planned 12%.
- Inchcape shares fall as much as 12% after the vehicle dealership group cut its margin guidance for the year due to continued underperformance of its business in Australia.
- Nokia shares fall as much as 3%. The firm gave bullish guidance for revenues exposed to data center buildout in 2027, seeing 25% to 30% growth in optical and IP networks businesses, adding to evidence that its networking gear is seeing strong demand due to AI adoption.
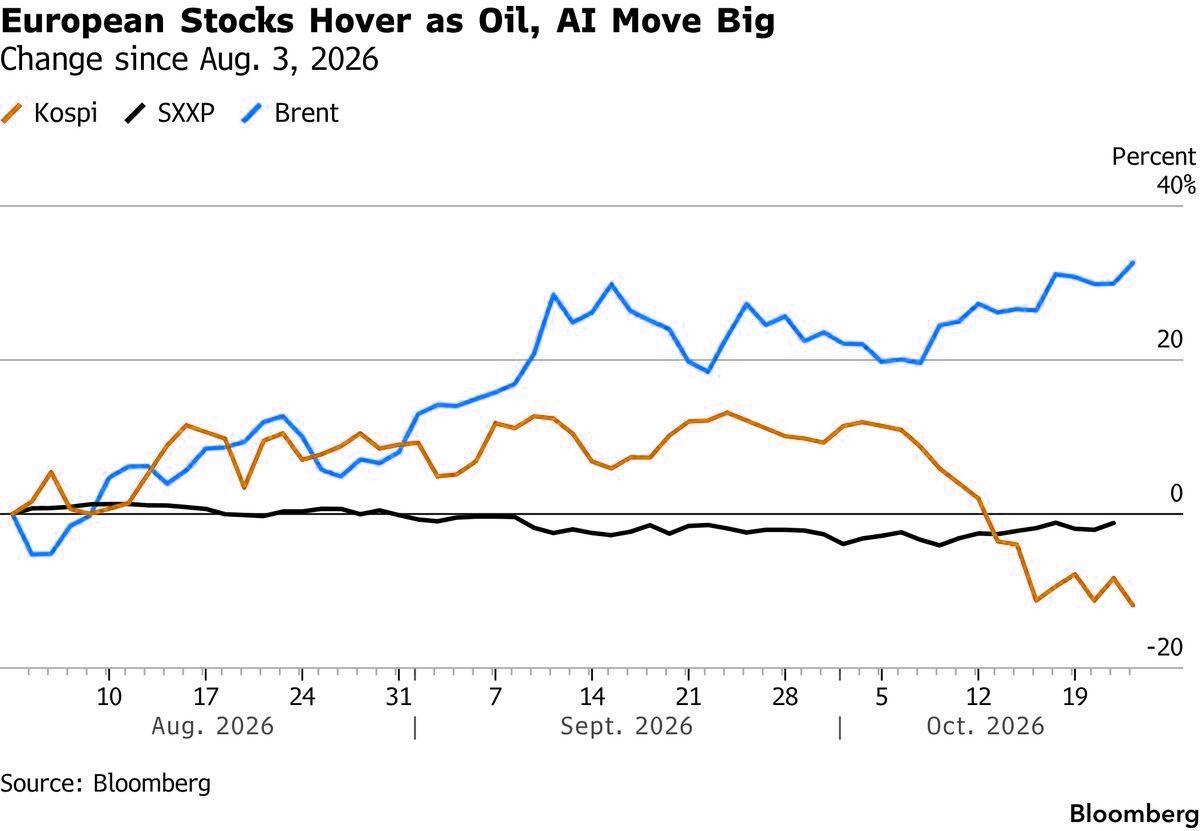
Europe’s Wednesday gains now look like borrowed strength: the Stoxx 600 has gone nowhere since early August while Brent and the Kospi have moved big.
Asian stocks fell sharply, with the MSCI Asia Pacific Index dropping more than 1.5% to head for its lowest close since July 30, as underwhelming US tech earnings and higher oil broadened the AI selloff across the region. According to Goldman’s regional wrap, South Korea’s Kospi sank 3.5% with SK Hynix down 5.5% and Samsung down 4%, the Hang Seng fell 3%, its biggest drop since March, with the Hang Seng Tech index down about 5% as Alibaba and Lenovo slumped, and the Nikkei 225 dropped 2.7% to break below 64,000 as Advantest, Tokyo Electron (-7%) and SoftBank (-6.9%) accounted for about 62% of the index’s losses. China’s CSI 300 fell 1.8% and is now 20% off its June high, Taiwan’s Taiex lost 1.8% and Australia’s ASX 200 slipped 0.4%, while Indonesia was the regional outlier, rising 1.1% as the sovereign wealth fund said it was buying local stocks. The Bank of Korea held rates at 3% but said growth would be “considerably higher” than projected, signaling more tightening to come.
In FX, the Bloomberg Dollar Spot Index is little changed and the DXY trades in a 101.44-101.73 range, pressured by lower yields. The yen is the standout, rising to its strongest against the euro in almost a year, with EUR/JPY falling as much as 1.1% to 175.64, its biggest drop in seven weeks, and USD/JPY dropping as much as 0.9% to 156.77, down for a third day; real money funds have been buying the yen, traders say, while the Swiss franc rose to its strongest against the euro since early July. Bloomberg’s Vassilis Karamanis notes the dollar now trades “almost as a clean function of Treasuries: once 10-year yields slipped below 5.10%, the dollar was sold further.” The kiwi lags after cooler-than-expected New Zealand CPI, the Egyptian pound hit a record low, and Turkey’s central bank cut its one-week repo rate by 100bps to 36%, its first cut since the start of the Iran war and in line with estimates.
Declines in Japanese equities are fueling risk-off sentiment, while recent stability in the Japanese government bond market is also supporting the yen, Hirofumi Suzuki, chief FX strategist at Sumitomo Mitsui Banking Corp., told Bloomberg.
In rates, Treasury futures extend gains in early US trading with the 10-year yield down 9bps near 5.03%, outperforming global peers, as haven demand from the AI stock jitters and deepening French bond stress overwhelms higher energy prices. Yields are 6-10bps lower across the curve with intermediate tenors outperforming, richening the 2s5s30s fly by around 4bp, while the 5s30s spread is steeper by about 4bp and the 30-year yield touched its lowest since Sept. 23. The haven bid is coming from the AI selloff rather than the oil spike, and the long end is the one place investors are still finding shelter (gold and Bitcoin clearly aren’t). Bunds and gilts are also bid, with the German 10-year yield down 7bps at 3.35% and long gilts outperforming, but France is the stress point: OATs fell more than a point at worst, lifting the 10-year yield to 5.14% and the spread over bunds to 177bps, the widest since 2011, while Italian and Spanish spreads also widened Wednesday. Money markets still price about 25bps of Fed hikes by year-end ahead of next Wednesday’s decision, after another poor, tailing 20Y auction on Wednesday. Treasury auctions resume at 1pm with a $26 billion 5-year TIPS new issue, while the IG dollar issuance slate includes one name so far after just over $8 billion priced on Wednesday, with at least two borrowers that stood down planning to look again today.
In commodities, WTI briefly topped $100 and trades in a $97.72-$100.09 range while Brent trades between $109.81 and $112.68, still contained within Tuesday’s broad range, after the IRGC Navy said four vessels transferring oil cargoes were struck in the Persian Gulf and three more hit sea mines west of the Strait of Hormuz. Iran’s Major General Rezaei said Iran will neither reopen the strait nor resume negotiations until seven new conditions are met. Saudi Arabia is in talks to give Aramco access to foreign strategic storage, while Morgan Stanley estimates Middle East crude exports, including non-Hormuz routes, at about 17m b/d last week, roughly 94% of prewar levels. In Libya, a pipeline from the Hamada and Al-Tahara fields was shut. Spot gold sits at the bottom of its $4,067-$4,146 range as the oil spike raises inflation risks ahead of the Fed, and LME copper slid toward the bottom of its $14,090-$14,370 range on the AI selloff.
US economic data slate includes initial jobless claims (8:30am, est. 200k) and continuing claims (8:30am), the September leading index (10am), EIA natural gas storage (10:30am), the October Kansas City Fed manufacturing index (11am) and a $26 billion 5-year TIPS auction (1pm). The Fed is in its blackout period. Companies reporting before the open include Procter & Gamble, Blackstone, Union Pacific, Lockheed Martin, Honeywell, Comcast, American Airlines, Valero and Nasdaq; Valero and Bloom Energy also headline today’s slate.
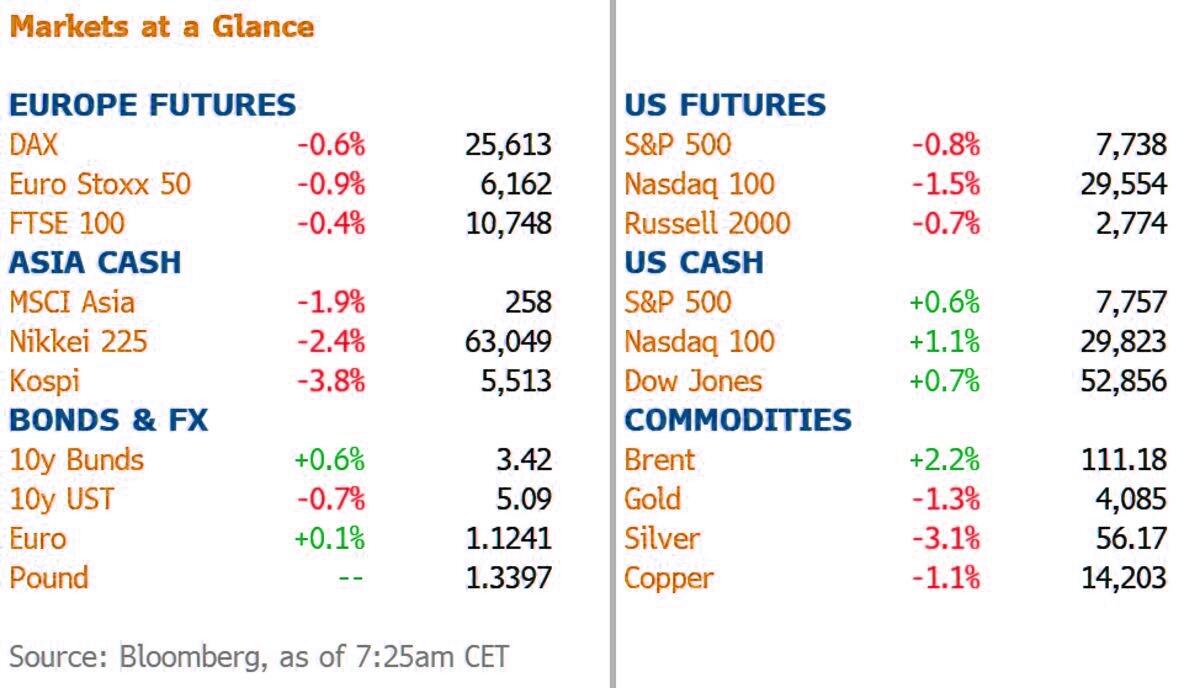
Market Snapshot
Top Overnight News
- For most of the war, Iran had an invaluable cushion: dozens of oil tankers holding millions of barrels of crude sitting safely in waters in Asia. Tehran steadily sold the oil to China, bringing in billions of much-needed cash. Now, that floating storage is gone. By mid-October, the reserves were fully depleted, according to analysts at Kpler, as a U.S. naval blockade prevented Iran from replacing the crude it normally sells to Chinese refineries. WSJ
- The US ordered some diplomats and their families to leave Saudi Arabia because of the threat from Houthi militants, as the Iran-backed group carried out more strikes from Yemen; four people were killed in two attacks on an Aramco oil field and an airport in Saudi Arabia’s Eastern Province. BBG
- The US and Israel have drawn up plans for renewed strikes on Iran after the midterm elections, with targets likely to include Iran’s energy infrastructure, nuclear facilities and missile and drone arsenals. NYT
- Aramco told staff to leave its headquarters in Dhahran and work remotely. RTRS
- Iran’s IRGC threatened US bases in the region if Washington keeps escorting ships through what it calls an “illegal” Hormuz route. BBG
- Saudi Arabia is in talks with foreign governments to give state-owned Aramco access to their strategic oil storage, as the kingdom seeks to make its supplies to customers more resilient during disruptions, Chief Executive Officer Amin Nasser said. BBG
- The risk-off mood boosted havens, with Treasuries, the yen and Swiss franc gaining. The 30-year US yield touched its lowest since Sept. 23, but there was no relief for embattled French bonds which led a slide in European peers. BBG
- France’s 10-year bond risk premium over Germany widened as much as 18bps to 177bps, the widest since 2011. BBG
- Over the past two weeks, HFs aggressively net sold global Info Tech stocks at the fastest pace in the past decade (-3.3 SDs), driven by long-and-short sales. Net allocation to Global AI stocks now sits in the 38th percentile while aggregate long/short ratio is in the 6th percentile vs. the past year. GSPB
- Apple shares have become investors’ preferred Big Tech hedge against AI volatility as the company largely sits out the infrastructure spending boom. BBG
- DeepSeek raised about $15 billion from investors including CATL and Tencent. BBG
- JPM’s HY AI credit basket is trading at all-time wides, 97bps wider than its widest level in July, with most of the move led by CoreWeave; Oracle has widened far more than the rest of the IG hyperscalers. JPM
- Japan’s largest labor union group is seeking another year of wage increases big enough to anchor pay growth against persistent inflation. WSJ
- Japanese monetary policy: the BOJ will keep rates unchanged at its meeting next week according to a report this morning in the Nikkei (this is consistent w/market expectations). Nikkei
- The Philippine central bank surprised markets with a bigger-than-expected interest rate hike as it seeks to keep inflation in check during one of the worst energy crisis in decades and looming weather-driven shocks. WSJ
- Turkey’s central bank cut its one-week repo rate by 100bps to 36%, its first cut since the start of the Iran war, in line with estimates. BBG
- The EU reached a provisional deal to overhaul securitization market rules that would unleash billions of euros to finance initiatives in key areas such as defense and climate resilience. BBG
- Barclays said it’s cutting 5,000 jobs, or about 5% of total headcount, as part of a “technology-enabled” effort to reduce costs as it adopts artificial intelligence across the bank. BBG
- The US signed a deal with Lockheed Martin for a minimum of 850 F-35 jets. BBG
- A federal judge barred the DHS from knocking on doors to check on people’s immigration status in nine states through election day, saying the practice likely violates the Voting Rights Act. BBG
- BofA Total Card Spending (week to October 17th) +4.9% Y/Y (prev. +5.1%); lower-income spending growth has consistently outpaced higher-income spending growth over the past several weeks. Newsquawk
- Some US banks are reportedly detecting unauthorised AI agents operating within accounts: Axios. The report added that the banks affected include Morgan Stanley (MS), Bank of America (BAC), JPMorgan (JPM), Wells Fargo (WFC).
A more detailed look at global markets courtesy of Newsquawk
APAC stocks were pressured and extended on losses throughout the session despite the positive lead from Wall Street, as AI and semiconductor names were sold after Tesla cut capex guidance, Lam Research fell after-hours, and Meta’s results stoked concerns over the financial strain of heavy AI investment. Middle East tensions also remained in focus, with the US preparing ordered departures at embassies across the Gulf and reports of renewed attacks on Saudi Arabia. ASX 200 was lower, with energy and retail stocks leading the declines as Nick Scali slumped after its profit warning and weighed on fellow retailers, although the index pared some of its earlier losses. Nikkei 225 extended on losses, with AI and semiconductor names such as Tokyo Electron, SoftBank Group, Ibiden and Fujikura pressured. KOSPI underperformed as concerns over investment in the AI value chain sparked a selloff in chip stocks, with Samsung Electronics and SK Hynix both pressured, while Samsung Electro-Mechanics reversed the opening gains it saw on its NVIDIA tie-up. The BoK held rates unanimously, as expected, while Governor Shin said the recent stock market correction weighs on consumption. Hang Seng led the declines in the region with Lenovo and Hua Hong Semiconductor each down around 7% and CATL extending its losing streak to a seventh day, while the Shanghai Comp declined amid uncertainty over the Middle East, with semiconductor names sold.
Top Asian News
- BoJ’s October lending survey: Corporate loan demand DI rose to +3 (prev. -1), led by small firms (+5), while banks’ lending stance DI for large firms remained unchanged at +3 and corporate loan margins continued to narrow.
- Japan’s RENGO set 2027 wage negotiation target centred on a 6% pay increase, while maintaining a minimum benchmark of at least 5%, aiming to sustain wage growth momentum following three consecutive years of average pay rises exceeding 5%.
- Japan is reportedly considering broadening the definition of defence-related spending to include AI, satellites, R&D and infrastructure such as ports and railways, amid US pressure to increase defence outlays and domestic fiscal constraints, according to sources.
European bourses are under pressure this morning, following on from the weakness seen in Asia. In Hong Kong, the likes of Alibaba (-6.1%) and PDD (-3.6%) slipped after China’s CMRC urged e-commerce platforms to strengthen product quality controls and consumer protection. Sectors highlight the negative bias. Telecoms, Food, Beverages & Tobacco and Health Care are the sector gainers. The underperformer is Basic Resources, followed by Banks and Tech. Key earnings include: SAP -0.9%, despite Q3 metric beats and sees FY26 cloud revenue at the upper end of its guided range; Nestle +1.6%, Q3 sales beat and reaffirms its FY26 sales growth target; Roche -0.5%, despite Q3 sales topping estimates and reaffirms FY outlook; Nokia -5.3%, despite Q3 profit beating expectations and expects supply chain constraints to continue in 2027. US equity futures follow the broader space lower, with underperformance in the NQ, pressured by Tesla (-4.5% pre-market) after reporting slower deliveries growth. Meta (-1.2% pre-market) follows sentiment lower, despite reporting strong Q3 results, but with potential focus on the Co. being ordered to pay a USD 25bln penalty to New Mexico.
FX
- G10s are mixed against the USD. JPY is the clear outperformer, joined closely by the CHF, benefiting from haven flows. On the flip side, the Antipodeans have been hampered by the risk tone, whilst the Kiwi digests cooler-than-expected CPI.
- DXY is on the back foot this morning, pressured by lower yields, which comes despite elevated energy prices. The index currently holds at the upper end of a 101.44 to 101.73 range; price action today will likely be dictated by cross-asset relationships, given that the data docket remains light today. Some of the pressure today may also be facilitated by poor results from Tesla.
- The JPY is the outperformer this morning, benefiting from its safe haven status. USD/JPY currently holds at the bottom end of a 156.76 to 158.25 range, a move which will no doubt be welcomed by Japanese officials. Focus for geopolitics was on an IRGC warning to US bases, that they may be a target if the US continues to allow ships to pass through the Strait of Hormuz. Aside from geopolitics, the JPY is digesting reports that Japan is considering the resumption of energy subsidies. Whilst this does reduce the inflationary implications of recent energy price rises, the overarching question is how Japan intends to finance this; of course, options include a supplementary budget, which could involve bond issuance, further fuelling fiscal woes. Elsewhere in Japan, the RENGO union is reportedly seeking a 6% wage increase for 2027, an increase from the 2026 figure of 5.01%; for reference, the union had demanded 5.94% in 2026.
- The Antipodeans are the slight laggards this morning, given the subdued risk tone. The Kiwi mildly underperforms vs the Aussie following a cooler-than-expected CPI report, but still remains at elevated levels. Therefore, money markets still expect the RBNZ to hike rates at next week’s meeting; Westpac sees rates to be hiked by 25bps.
Central Banks
- BoK left its rate unchanged at 3.0% as expected. BoK said today’s rate decision was unanimous, while the timing and pace of further rate hikes will depend on inflation, economic conditions and financial stability. It is essential to assess domestic and external risks and the impact of the previous two rate hikes. Expects inflation to remain above its target for an extended period. Stock price volatility has increased amid concerns over slowing semiconductor sector profitability and investment. Financial imbalances related to the housing market and household debt require continued attention. Expects exports and investment to sustain strong growth.
- SNB Minutes (Sept): The rise in inflation since the beginning of the year has been largely attributable to the increase in oil product prices, but there are still no signs of second-round effects, and core inflation has risen only slightly. At the same time, medium-term inflationary pressure is only slightly higher, and the new conditional inflation forecast shows that inflation is within the range consistent with price stability over the entire forecast horizon. On FX, the Minutes state that the SNB is also willing to be active in the foreign exchange market as necessary to ensure appropriate monetary conditions, but that the increased willingness to intervene is no longer necessary in the current environment.
Fixed Income
- In brief, a haven bid is seen across most core fixed income, as the geopolitical situation escalates and yields prove somewhat resilient to the energy upside, as much of that is priced by this stage, with focus instead increasingly on the growth side of the equation.
- USTs just off a 105-19+ peak, firmer by 16 ticks at best. The docket ahead is relatively light, but the focus is firmly on geopolitics after the activity seen in APAC hours and the continued dissemination of punchy rhetoric in the European morning.
- Bunds also bid, and in-fitting with USTs for the most part. At a 121.90 high, firmer by 50 ticks. As above, specifics are relatively light and the focus is firmly on geopolitical developments for core counterparts.
- In brief, while the focus for core debt is increasingly on the growth implications of the ongoing Middle East situation, this is not to a degree that is likely to dissuade policymakers from tightening in the weeks ahead, with the BoE for instance expected to start its tightening cycle; though, it is expected to be brief.
- Continuing with the UK, Gilts opened with modest gains, given the above haven allure factoring initially, before then being briefly unwound/offset by energy’s influence. However, Gilts broadly conform to peers, with gains of around 15 ticks currently, some 10 off the 84.73 peak.
- More pertinently, those under significant fiscal scrutiny are seeing a selloff as the growth-hit and inflationary angle combine to further knock the fiscal backdrop. A point that is particularly evident in France, with OATs down by over a point at most, lifting the 10yr yield to a 5.14% high, and widening the OAT-Bund spread to 1.73%, the highest since January 2011.
- The UK sells GBP 1bln 0.125% 2031 I/L Gilt: b/c 3.99x (prev. 4.26x), real yield 1.141% (prev. 0.933%).
Commodities
- Crude benchmarks have climbed throughout the APAC session and continue as Europe steps in. Iran’s IRGC Navy said four vessels transferring oil cargoes were struck in the Persian Gulf, while three other vessels hit sea mines yesterday west of the Strait of Hormuz, warning that US efforts to encourage passage could result in strikes on US bases. With repeated airing of these comments, it has continued to support the energy complex. WTI briefly topped USD 100/bbl, but currently holds at the upper end of its USD 97.72-100.09/bbl range, while Brent trades in a USD 109.81-112.68/bbl range. All being said, the crude complex remains contained within Tuesday’s broad range.
- Elsewhere, the NYT reported that the US and Israeli militaries have developed plans for renewed strikes on Iran after the US midterm elections, targeting energy infrastructure, nuclear facilities and missile and drone arsenals, while Israeli press cited US official comments that there has apparently been a change in the American position in favour of a pre-emptive strike on Iran.
- Spot gold has come under pressure in the European morning, as it resides at the lower end of its USD 4067-4146/oz range. Zooming out to the range formed over the past month, the yellow metal sits at the bottom of that range (USD 4066-4228/oz). The precious metal has not been favoured by usual risk-off flows or a weaker dollar, but instead found headwinds from escalating Middle East hostilities, which have raised inflation risks ahead of the Fed decision next week.
- 3M LME Copper slid overnight and currently holds at the bottom end of its USD 14.09k-14.37k/t range. The red metal is tracking the losses in the equity space, over continued worries of the AI trade. Copper has benefited recently due to its use in data centres and power infrastructure.
- US waived Russian diesel tax record requirements for buyers.
- Russia’s Novatek is to redistribute its LNG globally when the ban on its imports into Europe comes into effect, RIA reported.
- Iraq is looking to charter tankers to ship fuel oil outside of the Strait of Hormuz.
- Saudi Aramco CEO expects oil demand to increase by 3mln BPD once the Middle East conflict ends. The CEO added that oil could have been higher during the crisis; one factor that offset it was the east-west pipeline.
- Libya’s NOC said unidentified people have entered the crude-receiving station near the Zawiya refinery (120k BPD) and closed the pipeline valves.
Trade/Tariffs
- China’s MOFCOM said it is to improve its trade friction response mechanism.
Geopolitics: Middle East
- Iran’s IRGC Navy said four vessels transferring oil cargoes were struck in the Persian Gulf, while three other vessels hit sea mines yesterday west of the Strait of Hormuz, warning that US efforts to encourage passage could result in strikes on US bases. Furthermore, Fars reported similar commentary by the IRGC Navy, stating that confrontation could extend to US bases if Washington continues “encouraging” vessels to use an “illegal” route in the Strait of Hormuz.
- Iran’s Major General Rezaei said if diplomacy can create this understanding, Iran prefers diplomacy but warned that continuing the current situation will have strategic consequences, including that energy markets will not calm down for the next three years.
- Iran’s Major General Rezaei said Iran has presented seven new conditions through mediators and will neither reopen the Strait of Hormuz nor resume negotiations until they are met.
- Israeli PM Netanyahu said 90% of the mission has been accomplished in Iran and that striking Iranian nuclear facilities is not enough as long as the regime remains in power, Channel 12 reported. Additionally, Israeli PM Netanyahu said he will inform US President Trump of Israel’s plans regarding Iran but will not seek his approval for any strikes, according to Al Arabiya.
- US and Israeli militaries have reportedly developed plans for renewed strikes on Iran after the US midterm elections, targeting energy infrastructure, nuclear facilities and missile and drone arsenals, NYT reported, citing sources.
- US military is reducing troop presence at bases across the Middle East, while the State Department is ordering further staff reductions at diplomatic posts amid regional threats and potential US military action against Iran, NBC News reported.
- “The likelihood of a renewed war with Iran is increasing”, Israeli Walla reported citing a security official.
- Explosions were reportedly heard in Iran’s port city of Sirik, with claims that US forces struck an anti-ship missile launcher targeting vessels in the Strait of Hormuz, Israel’s Channel 12 reported.
- Saudi Civil Aviation said King Fahd Airport in Dammam was attacked on Wednesday evening, Al Arabiya reported.
- Saudi Arabia’s Eastern Province was reportedly targeted by four drones, Naya for Iraq reported.
- An Aramco facility in Saudi Arabia was on fire, Sabereen News reported.
- Saudi Aramco has reportedly instructed staff to evacuate its Dhahran headquarters and work from home, according to sources.
Geopolitics: Ukraine
- Russian Kremlin said there are no current plans for a conversation between President Putin and US President Trump, but it could be organised quickly if required.
- A drone struck energy infrastructure in Ukraine’s Poltava region near Kremenchuk, according to a local official.
Crypto
- Bitcoin slips below USD 82k, from an earlier peak of USD 84.3k as the downside coincides with the renewed pressure on risk assets.
US Event Calendar
- 08:30: Oct. Initial Jobless Claims, est. 200k, prior 199k
- 08:30: Oct. Continuing Claims, est. 1710k, prior 1710k
- 10:00: Sept. Leading Index, est. -0.1%, prior -0.1%
- 10:30: EIA weekly natural gas storage
- 11:00: Oct. Kansas City Fed Manf. Activity, est. 12, prior 14
- 13:00: $26bn 5-year TIPS auction (new issue)
Central Bank Speakers
- None: the Fed is in its pre-meeting blackout period ahead of the Oct. 28 FOMC decision
DB’s Jim Reid concludes the overnight wrap
It’s been another difficult 24 hours for markets, as investors grapple with AI growth concerns, higher oil prices, and ongoing fiscal stress. Admittedly, yesterday saw the S&P 500 (+0.58%) post a third consecutive gain, closing back within 1% of its record high. But as we go to press this morning, all those risks have resurfaced. First, the latest earnings after the US close failed to reassure investors, with futures on the NASDAQ 100 (-1.32%) pointing to fresh declines. Second, geopolitical tensions in the Middle East have seen oil prices bounce back this morning, with Brent crude (+1.73%) currently around a five-month high of $110.70/bbl. And third, France’s fiscal position has remained in the spotlight, with the country’s 10yr yield (+8.3bps) closing above 5% yesterday for the first time since 2002. Indeed, that risk-off move has also pushed the 30yr Treasury yield (-3.1bps) down to 5.38% this morning, which would be its lowest closing level in the last month. So the overnight backdrop has clearly turned more negative since yesterday’s session.
We’ll start with the oil moves, as several geopolitical headlines came through overnight that led to mounting concerns about a fresh escalation in the conflict. Among others, the New York Times reported that the US and Israel had drawn up plans for renewed strikes against Iran after the midterm elections, with the report saying targets would likely include Iran’s energy infrastructure. Moreover, the strikes on Saudi Arabia continued, with two people killed in an attack on the Shaybah oil field in Saudi Arabia, whilst another was killed in a strike on the King Fahd International Airport. In the meantime, the US State Department issued an ordered departure for non-emergency government employees and family members in Saudi Arabia.
All those headlines have come amidst little sign of progress towards a deal. Indeed, Iran’s foreign minister Abbas Araghchi wrote in an FT op-ed yesterday that “we have no trust whatsoever in the sincerity of the US administration’s professed desire for peace with Iran.” And he also said “there is little reason to expect progress now”. So that dampened hopes for a near-term resolution, and oil prices have continued to rise over the last 24 hours. So Brent crude is currently up +1.73% this morning at $110.70/bbl, and investors are also pricing a longer period of high oil prices extending well into 2027. For instance, the 12-month Brent future (+0.75%) is also up to $88.39/bbl this morning.
The other big development after the US close were the earnings releases from Meta and Tesla, with tech stocks struggling to gain traction since. For Meta, its shares rose by more than +2% in after-hours trading, as it beat on Q3 revenue ($64.6bn vs $63.3bn est.) and delivered Q4 guidance towards the upper end of expectations ($73-76bn vs $73.6bn est.). The company also slightly boosted its 2026 capex plan from a $130bn-145bn range to $135bn-145bn. However, Tesla fell by -3% after-hours after it cut its 2026 capex target from $25bn to $20bn. So that raised questions about the speed of its transition into AI and robotics, while current revenue and earnings were close to expectations.
In aggregate, those results took some of the shine off the tech mood overnight, which had been a bit more optimistic yesterday. So this morning, futures on the S&P 500 (-0.66%) and the NASDAQ 100 (-1.32%) are both pointing lower. Moreover, we’ve seen that echoed across Asian equity markets this morning, with all the major indices falling back. That includes sharp losses for the KOSPI (-3.26%), the Hang Seng (-2.87%) and the Nikkei (-2.00%), whilst there have been relatively smaller declines for the CSI 300 (-1.26%) and the Shanghai Comp (-0.89%). Earlier in the session, the CSI 300 had even entered bear market territory, having fallen more than -20% since its closing peak in June, although it’s pared back those losses since and is now slightly above that level.
Before those earnings, US markets had actually put in a decent session yesterday, with tech stocks leading the way. That was partly thanks to the earnings report from SpaceX after the previous day’s close, which helped to reassure investors that the tech rally was still durable, and we saw some of the most AI-exposed names do particularly well yesterday. For instance, the Philly semiconductor index (+1.97%) continued to recover, whilst the NASDAQ (+1.05%) also put in a strong session. So that helped to lift US equities more broadly, with the S&P 500 ultimately up +0.58%, closing within 1% of its record high. And over in Europe, there were even bigger gains, with the STOXX 600 (+0.92%) and other indices all posting a solid performance, with tech leading the way there too.
But even as equities saw growing optimism, the fiscal concerns were still present around Europe, with France’s 10yr yield (+8.3bps) closing at a post-2002 high of 5.01%. And with the 10yr bund yield only up +2.1bps to 3.42%, that pushed the Franco-German 10yr spread up to 159bps, its highest closing level since 2011. Now admittedly, the spread remains some way beneath its Euro crisis peak, when it closed at 189bps in November 2011, but the continued rise has seen other sovereigns come under pressure too. Among others, the Italian 10yr spread over bunds widened +3.8bps to 116bps, whilst Spain’s widened +3.1bps to 66bps, marking its widest level since June 2025.
For Europe, matters weren’t helped by the latest rise in energy prices, which added to concerns on the inflation side. For instance, European natural gas futures (+2.78%) were back up to €87.43/MWh. And even though Brent crude was little changed in yesterday’s session, the 1yr Euro inflation swap (+3.5bps) still rose to 3.82%, its highest level since May. And with more inflation priced in, investors priced in more ECB rate hikes too, with the amount priced by the June 2027 meeting up +2.0bps on the day to 64bps.
Over in the US, Treasury yields saw a smaller increase than their European counterparts, with the 10yr yield (+1.1bps) only rising to 5.12%. However, that’s pulled back given the risk-off tone overnight, with the 10yr yield (-3.5bps) falling back to 5.08%.
Elsewhere overnight, the Bank of Korea left their policy rate at 3%, in line with expectations. But they also said growth this year and next would be “considerably higher” than their August projections, and Governor Shin said they needed to maintain a tightening policy stance. Meanwhile in New Zealand, inflation fell more than expected in Q3, falling to +3.7% on a year-on-year basis (vs. +3.8% expected).
Finally, the other inflation release yesterday came from the UK CPI print, which rose more than expected to +3.5% in September (vs. +3.4% expected). That was the highest level for headline CPI in nearly a year, whilst the core CPI print also hit a 6-month high of +2.8%, although that was in line with expectations. So collectively, that helped to cement investor expectations for a BoE rate hike in November, particularly after the strong labour market data the previous day. In fact by the close yesterday, markets were pricing in a 98% chance of a November rate hike.
Looking at the day ahead now, data releases include the US weekly initial jobless claims, and the European Commission’s preliminary consumer confidence indicator for the Euro Area in October. Otherwise from central banks, we’ll hear from the ECB’s Kocher, Panetta, Pereira and Escriva.
1b European opening report
Crude benchmarks stronger after the IRGC warned US bases; TSLA falls post-earnings – Newsquawk US Market Open
Thursday, Oct 22, 2026 – 06:35 AM
- Iran’s IRGC Navy warned that US efforts to encourage passage could result in strikes on US bases.
- Iran’s Major General Rezaei said Iran has presented seven new conditions through mediators and will neither reopen the Strait of Hormuz nor resume negotiations until they are met.
- NQ underperforms, as Tesla’s cut in spending plans weighs on the Tech/AI space.
- DXY modestly lower; JPY and CHF supported by haven demand while NZD lags on cooler CPI.
- Fixed income benchmarks helped by risk aversion.
- Energy benchmarks climb as Iran warns of strikes on US bases (Brent +2.9%)
- Looking ahead, highlights include US Jobless Claims (Oct/17), CBRT Policy Announcement (Oct). Supply from the US. Earnings from American Airlines, Blackstone, Valero Energy, Bloom Energy, L’Oreal.
SNAPSHOT

EUROPEAN TRADE
EQUITIES
- European bourses are under pressure this morning, following on from the weakness seen in Asia. In Hong Kong, the likes of Alibaba (-6.1%) and PDD (-3.6%) slipped after China’s CMRC urged e-commerce platforms to strengthen product quality controls and consumer protection.
- Sectors highlight the negative bias. Telecoms, Food, Beverages & Tobacco and Health Care are the sector gainers. The underperformer is Basic Resources, followed by Banks and Tech.
- Key earnings include: SAP -0.9%, despite Q3 metric beats and sees FY26 cloud revenue at the upper end of its guided range; Nestle +1.6%, Q3 sales beat and reaffirms its FY26 sales growth target; Roche -0.5%, despite Q3 sales topping estimates and reaffirms FY outlook; Nokia -5.3%, despite Q3 profit beating expectations and expects supply chain constraints to continue in 2027.
- US equity futures follow the broader space lower, with underperformance in the NQ, pressured by Tesla (-4.5% pre-market) after reporting slower deliveries growth. Meta (-1.2% pre-market) follows sentiment lower, despite reporting strong Q3 results, but with potential focus on the Co. being ordered to pay a USD 25bln penalty to New Mexico.
- Meta Platforms Inc (META) Q3 2026 (USD): EPS 3.83 (exp. 6.67), Revenue 64.6bln (exp. 63.31bln). Q3 includes a USD 9.89bln charge related to the teen mental health litigation agreement; excluding the charge, EPS would have been 7.40. Q4 revenue guidance 73-76bln (exp. 73.64bln); FY26 capex guidance 135-145bln (prev. 130-145bln). Announced new non-voting Class C shares, distributed one-for-one to Class A/B holders.
- Tesla (TSLA) Q3 2026 (USD): Adj. EPS 0.48 (exp. 0.45), Revenue 28.0bln (exp. 28.1bln). Gross margin 19.6% (exp. 17.8%). FCF 1.53bln (exp. -4.99bln). On the call, CEO Musk said the company is aiming to produce approximately 5mln vehicles annually by 2030, while FY capex guidance was revised to approximately USD 20bln (prev. USD 25bln).
- Click for the sessions European pre-market equity newsflow
- Click for the additional news
FX
- Snapshot: G10s are mixed against the USD. JPY is the clear outperformer, joined closely by the CHF, benefiting from haven flows. On the flip side, the Antipodeans have been hampered by the risk tone, whilst the Kiwi digests cooler-than-expected CPI.
- DXY is on the back foot this morning, pressured by lower yields, which comes despite elevated energy prices. The index currently holds at the upper end of a 101.44 to 101.73 range; price action today will likely be dictated by cross-asset relationships, given that the data docket remains light today. Some of the pressure today may also be facilitated by poor results from Tesla.
- The JPY is the outperformer this morning, benefiting from its safe haven status. USD/JPY currently holds at the bottom end of a 156.76 to 158.25 range, a move which will no doubt be welcomed by Japanese officials. Focus for geopolitics was on an IRGC warning to US bases, that they may be a target if the US continues to allow ships to pass through the Strait of Hormuz. Aside from geopolitics, the JPY is digesting reports that Japan is considering the resumption of energy subsidies. Whilst this does reduce the inflationary implications of recent energy price rises, the overarching question is how Japan intends to finance this; of course, options include a supplementary budget, which could involve bond issuance, further fuelling fiscal woes. Elsewhere in Japan, the RENGO union is reportedly seeking a 6% wage increase for 2027, an increase from the 2026 figure of 5.01%; for reference, the union had demanded 5.94% in 2026.
- The Antipodeans are the slight laggards this morning, given the subdued risk tone. The Kiwi mildly underperforms vs the Aussie following a cooler-than-expected CPI report, but still remains at elevated levels. Therefore, money markets still expect the RBNZ to hike rates at next week’s meeting; Westpac sees rates to be hiked by 25bps.
FIXED INCOME
- In brief, a haven bid is seen across most core fixed income, as the geopolitical situation escalates and yields prove somewhat resilient to the energy upside, as much of that is priced by this stage, with focus instead increasingly on the growth side of the equation.
- USTs just off a 105-19+ peak, firmer by 16 ticks at best. The docket ahead is relatively light, but the focus is firmly on geopolitics after the activity seen in APAC hours and the continued dissemination of punchy rhetoric in the European morning.
- Bunds also bid, and in-fitting with USTs for the most part. At a 121.90 high, firmer by 50 ticks. As above, specifics are relatively light and the focus is firmly on geopolitical developments for core counterparts.
- In brief, while the focus for core debt is increasingly on the growth implications of the ongoing Middle East situation, this is not to a degree that is likely to dissuade policymakers from tightening in the weeks ahead, with the BoE for instance expected to start its tightening cycle; though, it is expected to be brief.
- Continuing with the UK, Gilts opened with modest gains, given the above haven allure factoring initially, before then being briefly unwound/offset by energy’s influence. However, Gilts broadly conform to peers, with gains of around 15 ticks currently, some 10 off the 84.73 peak.
- More pertinently, those under significant fiscal scrutiny are seeing a selloff as the growth-hit and inflationary angle combine to further knock the fiscal backdrop. A point that is particularly evident in France, with OATs down by over a point at most, lifting the 10yr yield to a 5.14% high, and widening the OAT-Bund spread to 1.73%, the highest since January 2011.
- The UK sells GBP 1bln 0.125% 2031 I/L Gilt: b/c 3.99x (prev. 4.26x), real yield 1.141% (prev. 0.933%).
COMMODITIES
- Crude benchmarks have climbed throughout the APAC session and continue as Europe steps in. Iran’s IRGC Navy said four vessels transferring oil cargoes were struck in the Persian Gulf, while three other vessels hit sea mines yesterday west of the Strait of Hormuz, warning that US efforts to encourage passage could result in strikes on US bases. With repeated airing of these comments, it has continued to support the energy complex. WTI briefly topped USD 100/bbl, but currently holds at the upper end of its USD 97.72-100.09/bbl range, while Brent trades in a USD 109.81-112.68/bbl range. All being said, the crude complex remains contained within Tuesday’s broad range.
- Elsewhere, the NYT reported that the US and Israeli militaries have developed plans for renewed strikes on Iran after the US midterm elections, targeting energy infrastructure, nuclear facilities and missile and drone arsenals, while Israeli press cited US official comments that there has apparently been a change in the American position in favour of a pre-emptive strike on Iran.
- Spot gold has come under pressure in the European morning, as it resides at the lower end of its USD 4067-4146/oz range. Zooming out to the range formed over the past month, the yellow metal sits at the bottom of that range (USD 4066-4228/oz). The precious metal has not been favoured by usual risk-off flows or a weaker dollar, but instead found headwinds from escalating Middle East hostilities, which have raised inflation risks ahead of the Fed decision next week.
- 3M LME Copper slid overnight and currently holds at the bottom end of its USD 14.09k-14.37k/t range. The red metal is tracking the losses in the equity space, over continued worries of the AI trade. Copper has benefited recently due to its use in data centres and power infrastructure.
- US waived Russian diesel tax record requirements for buyers.
- Russia’s Novatek is to redistribute its LNG globally when the ban on its imports into Europe comes into effect, RIA reported.
- Iraq is looking to charter tankers to ship fuel oil outside of the Strait of Hormuz.
- Saudi Aramco CEO expects oil demand to increase by 3mln BPD once the Middle East conflict ends. The CEO added that oil could have been higher during the crisis; one factor that offset it was the east-west pipeline.
- Libya’s NOC said unidentified people have entered the crude-receiving station near the Zawiya refinery (120k BPD) and closed the pipeline valves.
TRADE/TARIFFS
- China’s MOFCOM said it is to improve its trade friction response mechanism.
NOTABLE EUROPEAN DATA RECAP
- French Business Confidence (Oct) 105 vs. Exp. 101 (Prev. 101).
- French Business Climate Indicator (Oct) 98 vs. Exp. 96 (Prev. 96).
- UK CBI Industrial Trends Orders (Oct) -32 vs. Exp. -20 (Prev. -9).
CENTRAL BANKS
- BoK left its rate unchanged at 3.0% as expected. BoK said today’s rate decision was unanimous, while the timing and pace of further rate hikes will depend on inflation, economic conditions and financial stability. It is essential to assess domestic and external risks and the impact of the previous two rate hikes. Expects inflation to remain above its target for an extended period. Stock price volatility has increased amid concerns over slowing semiconductor sector profitability and investment. Financial imbalances related to the housing market and household debt require continued attention. Expects exports and investment to sustain strong growth. SNB Minutes (Sept): The rise in inflation since the beginning of the year has been largely attributable to the increase in oil product prices, but there are still no signs of second-round effects, and core inflation has risen only slightly. At the same time, medium-term inflationary pressure is only slightly higher, and the new conditional inflation forecast shows that inflation is within the range consistent with price stability over the entire forecast horizon. On FX, the Minutes state that the SNB is also willing to be active in the foreign exchange market as necessary to ensure appropriate monetary conditions, but that the increased willingness to intervene is no longer necessary in the current environment.
NOTABLE US HEADLINES
- BofA Total Card Spending (week to October 17th) +4.9% Y/Y (prev. +5.1%); lower-income spending growth has consistently outpaced higher-income spending growth over the past several weeks.
- Some US banks are reportedly detecting unauthorised AI agents operating within accounts, Axios reported citing sources. The report added that the banks affected include Morgan Stanley (MS), Bank of America (BAC), JPMorgan (JPM), Wells Fargo (WFC).
GEOPOLITICS
MIDDLE EAST
- Iran’s IRGC Navy said four vessels transferring oil cargoes were struck in the Persian Gulf, while three other vessels hit sea mines yesterday west of the Strait of Hormuz, warning that US efforts to encourage passage could result in strikes on US bases. Furthermore, Fars reported similar commentary by the IRGC Navy, stating that confrontation could extend to US bases if Washington continues “encouraging” vessels to use an “illegal” route in the Strait of Hormuz.
- Iran’s Major General Rezaei said if diplomacy can create this understanding, Iran prefers diplomacy but warned that continuing the current situation will have strategic consequences, including that energy markets will not calm down for the next three years.
- Iran’s Major General Rezaei said Iran has presented seven new conditions through mediators and will neither reopen the Strait of Hormuz nor resume negotiations until they are met.
- Israeli PM Netanyahu said 90% of the mission has been accomplished in Iran and that striking Iranian nuclear facilities is not enough as long as the regime remains in power, Channel 12 reported. Additionally, Israeli PM Netanyahu said he will inform US President Trump of Israel’s plans regarding Iran but will not seek his approval for any strikes, according to Al Arabiya.
- US and Israeli militaries have reportedly developed plans for renewed strikes on Iran after the US midterm elections, targeting energy infrastructure, nuclear facilities and missile and drone arsenals, NYT reported, citing sources.
- US military is reducing troop presence at bases across the Middle East, while the State Department is ordering further staff reductions at diplomatic posts amid regional threats and potential US military action against Iran, NBC News reported.
- “The likelihood of a renewed war with Iran is increasing”, Israeli Walla reported citing a security official.
- Explosions were reportedly heard in Iran’s port city of Sirik, with claims that US forces struck an anti-ship missile launcher targeting vessels in the Strait of Hormuz, Israel’s Channel 12 reported.
- Saudi Civil Aviation said King Fahd Airport in Dammam was attacked on Wednesday evening, Al Arabiya reported.
- Saudi Arabia’s Eastern Province was reportedly targeted by four drones, Naya for Iraq reported.
- An Aramco facility in Saudi Arabia was on fire, Sabereen News reported.
- Saudi Aramco has reportedly instructed staff to evacuate its Dhahran headquarters and work from home, according to sources.
RUSSIA-UKRAINE
- Russian Kremlin said there are no current plans for a conversation between President Putin and US President Trump, but it could be organised quickly if required.
- A drone struck energy infrastructure in Ukraine’s Poltava region near Kremenchuk, according to a local official.
CRYPTO
- Bitcoin slips below USD 82k, from an earlier peak of USD 84.3k as the downside coincides with the renewed pressure on risk assets.
APAC TRADE
- APAC stocks were pressured and extended on losses throughout the session despite the positive lead from Wall Street, as AI and semiconductor names were sold after Tesla cut capex guidance, Lam Research fell after-hours, and Meta’s results stoked concerns over the financial strain of heavy AI investment. Middle East tensions also remained in focus, with the US preparing ordered departures at embassies across the Gulf and reports of renewed attacks on Saudi Arabia.
- ASX 200 was lower, with energy and retail stocks leading the declines as Nick Scali slumped after its profit warning and weighed on fellow retailers, although the index pared some of its earlier losses.
- Nikkei 225 extended on losses, with AI and semiconductor names such as Tokyo Electron, SoftBank Group, Ibiden and Fujikura pressured.
- KOSPI underperformed as concerns over investment in the AI value chain sparked a selloff in chip stocks, with Samsung Electronics and SK Hynix both pressured, while Samsung Electro-Mechanics reversed the opening gains it saw on its NVIDIA tie-up. The BoK held rates unanimously, as expected, while Governor Shin said the recent stock market correction weighs on consumption.
- Hang Seng led the declines in the region with Lenovo and Hua Hong Semiconductor each down around 7% and CATL extending its losing streak to a seventh day, while the Shanghai Comp declined amid uncertainty over the Middle East, with semiconductor names sold.
NOTABLE ASIA-PAC HEADLINES
- BoJ’s October lending survey: Corporate loan demand DI rose to +3 (prev. -1), led by small firms (+5), while banks’ lending stance DI for large firms remained unchanged at +3 and corporate loan margins continued to narrow.
- Japan’s RENGO set 2027 wage negotiation target centred on a 6% pay increase, while maintaining a minimum benchmark of at least 5%, aiming to sustain wage growth momentum following three consecutive years of average pay rises exceeding 5%.
- Japan is reportedly considering broadening the definition of defence-related spending to include AI, satellites, R&D and infrastructure such as ports and railways, amid US pressure to increase defence outlays and domestic fiscal constraints, according to sources.
NOTABLE APAC DATA RECAP
- New Zealand CPI (Q3 QQ) 0.7% vs. Exp. 0.8% (Prev. 1.5%); Y/Y 3.7% vs. Exp. 3.8% (Prev. 4.1%).
- Japanese Stock Investment by Foreigners (Oct/17) -66.5B (Prev. 3545.5B).
- Japanese Foreign Bond Investment (Oct/17) -161.6B (Prev. -339.9B).
1 c) Asian opening report
Crude benchmarks gain on continued punchy IRGC rhetoric; European bourses are set for a lower open – Newsquawk EU Market Open
Thursday, Oct 22, 2026 – 01:44 AM
- APAC stocks were pressured and extended on losses throughout the session as AI and semiconductor names were sold, despite the gains on Wall Street.
- The Hang Seng and KOSPI led the declines, while the BoK held rates as expected.
- European equity futures indicate a negative cash market open with Euro Stoxx 50 futures down 0.6%.
- JPY strengthened on haven demand, while DXY softened and NZD lagged after cooler-than-expected CPI.
- Crude futures were firmer amid a flurry of Middle East headlines, while precious metals were pressured.
- Looking ahead, highlights include US Jobless Claims (Oct/17), CBRT Policy Announcement (Oct), SNB Minutes (Sep). Speakers include Riksbank’s Jansson. Supply from the UK and the US. Earnings from Lockheed Martin, Comcast, American Airlines, Blackstone, P&G, Valero Energy, Bloom Energy, Thales, L’Oreal.
SNAPSHOT

LOOKING AHEAD
- Highlights include US Jobless Claims (Oct/17), CBRT Policy Announcement (Oct), SNB Minutes (Sep). Speakers include Riksbank’s Jansson. Supply from the UK and the US. Earnings from Lockheed Martin, Comcast, American Airlines, Blackstone, P&G, Valero Energy, Bloom Energy, Thales, L’Oreal.
- Click for the Newsquawk Week in Focus.
US TRADE
EQUITIES
- US stocks gained with the Nasdaq outperforming, while NVIDIA’s GTC keynote saw the Co. announce a raft of partnerships, including Google Cloud scaling NVIDIA Vera Rubin infrastructure to 960k GPUs, and outlined plans with supply chain partners to expand substrate and packaging capacity. Risk-on trade was seen after a US official said Russia accepted a US proposal for a trilateral meeting with Ukraine, although risk appetite was dented late in the session after US officials said the State Department is preparing ordered departures of some personnel at US embassies across the Gulf. On the earnings front, Elevance Health beat and raised its FY guidance, Danaher beat but cut its FY core sales growth outlook, Abbott announced plans to separate its Nutrition business, and Philip Morris guided FY EPS below expectations. After-hours, Meta beat on revenue with EPS hit by a litigation charge, Tesla topped EPS forecasts, IBM and Texas Instruments beat, while Lam Research fell despite beating.
- SPX +0.60% at 7,759, NDX +1.20% at 29,845, DJI +0.69% at 52,857, RUT +0.32% at 2,782.
NOTABLE HEADLINES
- US President Trump said he had a good meeting on cyber.
- US Treasury Secretary Bessent shrugs off ‘systemic’ AI risks at closed-door investor conference, FT reported.
- US authorises offloading cargo involving some blocked vessels. Authorising wind down activities, limited safety and environmental transactions, and the offloading of cargo involving certain persons or vessels blocked on October 21, 2026.
NOTABLE US EQUITY HEADLINES
- US President Trump said Apple (AAPL) is committing to purchase USD 100mln worth of Pennsylvania titanium for its new iPhone.
- SpaceX (SPCX) and Tesla (TSLA) are reportedly pushing for a merger deal by H1 2027, Bloomberg sources say; merger is reportedly intended to close before the end of US President Trump’s term. The combined company would have an implied market value of about USD 3.7tln.
- Meta Platforms Inc (META) Q3 2026 (USD): EPS 3.83 (exp. 6.67), Revenue 64.6bln (exp. 63.31bln). Q3 includes a USD 9.89bln charge related to the teen mental health litigation agreement; excluding the charge, EPS would have been 7.40. Q4 revenue guidance 73-76bln (exp. 73.64bln); FY26 capex guidance 135-145bln (prev. 130-145bln). Announced new non-voting Class C shares, distributed one-for-one to Class A/B holders.
- Meta (META) must pay USD 25bln in penalties, a New Mexico judge ruled after jury found company misled consumers about privacy.
- Tesla (TSLA) Q3 2026 (USD): Adj. EPS 0.48 (exp. 0.45), Revenue 28.0bln (exp. 28.1bln). Gross margin 19.6% (exp. 17.8%). FCF 1.53bln (exp. -4.99bln). On the call, CEO Musk said the company is aiming to produce approximately 5mln vehicles annually by 2030, while FY capex guidance was revised to approximately USD 20bln (prev. USD 25bln).
- Lam Research (LRCX) Q1 2027 (USD): Adj. EPS 2.20 (exp. 2.18), Revenue 8.22bln (exp. 8.13bln). Q2 revenue outlook 8.2-9.0bln (exp. 8.533bln). On the call, said its preliminary CY27 wafer fabrication equipment outlook exceeds USD 200bln (exp. CY26 USD 150bln).
- International Business Machines (IBM) Q3 2026 (USD): Operating EPS 2.95 (exp. 2.86), Revenue 17.1bln (exp. 16.81bln); reaffirms FY revenue guidance; Raises outlook for full-year free cash flow.
- Texas Instruments (TXN) Q3 2026 (USD): EPS 2.62 (exp. 2.42), Revenue 6.06bln (exp. 5.92bln), Next Qtr. Rev. 5.8-6.3bln (exp. 5.75bln), Next Qtr. EPS 2.45-2.79 (exp. 2.30).
TRADE/TARIFFS
- Canadian PM Carney said he spoke to US President Trump on Wednesday for quite some time; he discussed a wide range of issues with US President Trump, including Iran.
- Canada and Ontario unveil joint CAD 9bln support package to help steel and auto sectors deal with US tariffs, and also boost critical minerals supply chain.
APAC TRADE
EQUITIES
- APAC stocks were pressured and extended on losses throughout the session despite the positive lead from Wall Street, as AI and semiconductor names were sold after Tesla cut capex guidance, Lam Research fell after-hours, and Meta’s results stoked concerns over the financial strain of heavy AI investment. Middle East tensions also remained in focus, with the US preparing ordered departures at embassies across the Gulf and reports of renewed attacks on Saudi Arabia.
- ASX 200 was lower, with energy and retail stocks leading the declines as Nick Scali slumped after its profit warning and weighed on fellow retailers, although the index pared some of its earlier losses.
- Nikkei 225 extended on losses, with AI and semiconductor names such as Tokyo Electron, SoftBank Group, Ibiden and Fujikura pressured.
- KOSPI underperformed as concerns over investment in the AI value chain sparked a sell-off in chip stocks, with Samsung Electronics and SK Hynix both pressured, while Samsung Electro-Mechanics reversed the opening gains it saw on its NVIDIA tie-up. The BoK held rates unanimously, as expected, while Governor Shin said the recent stock market correction weighs on consumption.
- Hang Seng led the declines in the region with Lenovo and Hua Hong Semiconductor each down around 7% and CATL extending its losing streak to a seventh day, while the Shanghai Comp declined amid uncertainty over the Middle East, with semiconductor names sold.
- US equity futures were lower with the NQ underperforming amid the pressure in semiconductor names, while Bloomberg reported SpaceX and Tesla are pushing for a merger deal by H1 2027.
- European equity futures indicate a negative cash market open with Euro Stoxx 50 futures down 0.6%, after the cash market closed with gains of 1.5% on Wednesday.
FX
- DXY softened and drifted lower throughout the session, with the USD weakest against the JPY as US yields eased and Asian stocks slumped, while Middle East headlines remained in focus, including reports of Iranian missiles launched towards the Strait of Hormuz and the NYT reporting that the US and Israel have developed plans for renewed strikes on Iran after the US midterms.
- EUR/USD edged higher amid the softer dollar, with French unrest and the wider OAT-Bund spread still in focus ahead of Moody’s review on Friday.
- GBP/USD was marginally firmer after Wednesday’s gains on hotter-than-expected UK CPI.
- USD/JPY initially edged higher as elevated oil prices fuelled concerns over Japan’s trade balance, before the JPY strengthened on haven demand as Asian stocks slumped and US yields eased.
- Antipodeans underperformed, with NZD/USD lagging after Q3 CPI came in cooler than expected, while AUD/USD gave back some of Wednesday’s outperformance amid the risk-off mood.
- PBoC set USD/CNY midpoint at 6.7195 vs exp. 6.6756 (prev. 6.7172).
FIXED INCOME
- 10yr UST futures extended on gains throughout the session amid the risk-off tone in APAC, more than recovering Wednesday’s late dip on reports of US ordered departures across the Gulf, while the 20yr bond auction tailed by 0.9bps.
- Bund futures were firmer in tandem with USTs, after Wednesday’s losses when ECB’s Kazaks said some more tightening might be necessary if inflation stays above target, while French 10yr yields rose above 5% for the first time in 24 years.
- 10yr JGB futures were firmer but off their highs, with the 10yr JGB yield briefly rising as higher oil prices stoked inflation concerns, while super-long bonds were supported.
- Australia sold AUD 150mln 2.0% 2035 I/L bond; b/c 3.47x (prev. 4.89x); Average yield 2.8373% (prev. 2.759%).
- US Treasury sold USD 13bln of 20-year bonds; tails 0.9bps. High Yield: 5.469% (prev. 5.420%, six-auction avg. 5.120%); WI: 5.460%. Tail: 0.9bps (prev. 2.0bps, six-auction avg. 0.2bps). Bid-to-Cover: 2.73x (prev. 2.57x, six-auction avg. 2.62x). Dealers: 10.3% (prev. 16.9%, six-auction avg. 11.9%). Directs: 31.6% (prev. 30.7%, six-auction avg. 22.9%). Indirects: 58.2% (prev. 52.5%, six-auction avg. 65.2%).
COMMODITIES
- Crude futures were firmer and gradually climbed throughout the session amid a flurry of Middle East headlines. This includes the IRGC Navy saying four vessels transferring oil cargoes were struck in the Persian Gulf and three others hit sea mines west of the Strait of Hormuz, reports of Iranian missiles launched towards the Strait of Hormuz, drones targeting Saudi Arabia’s Eastern Province, and the NYT reporting that the US and Israel have developed plans for renewed strikes on Iran after the midterms. Elsewhere, EIA data on Wednesday showed a larger-than-expected crude draw.
- Spot gold was pressured despite the risk-off tone and softer USD, while silver underperformed.
- Copper futures declined alongside the weakness in regional equities.
- US waives Russian diesel tax record requirements for buyers.
- China and Russia agree to support firms to expand oil cooperation, Xinhua reported.
- Gulf Keystone Petroleum CEO expects gross output in Iraqi Kurdistan’s Shaikan oilfield to increase to over 90k BPD from about 45k BPD by 2030 if drilling commences next year. Merger with Shamaran Petroleum to double Gulf Keystone’s working interest production to 53k BPD of oil, up from 28k BPD. Hamrin oil field in Iraq estimated to have about 7bln bbls of oil in place, of which 10-15%, or 0.5-1bln bbls, is recoverable. CEO expects there to be other opportunities in Iraq, which company will take on merit.
- US posted license for Lukoil international GMBH sale talks.
- IRGC said Saudi and UAE pipelines cannot replace the Strait of Hormuz and Hormuz Strait has no alternative for oil transit, reported SNN.
- Exxon (XOM) shuts catalytic reformer at Joliet, Illinois refinery (275k BPD).
CRYPTO
- Bitcoin and Ethereum were lower.
CENTRAL BANKS
- BoJ’s October lending survey: Corporate loan demand DI rose to +3 (prev. -1), led by small firms (+5), while banks’ lending stance DI for large firms remained unchanged at +3 and corporate loan margins continued to narrow.
- BoK left its rate unchanged at 3.0% as expected. BoK said today’s rate decision was unanimous, while the timing and pace of further rate hikes will depend on inflation, economic conditions and financial stability. It is essential to assess domestic and external risks and the impact of the previous two rate hikes. Expects inflation to remain above its target for an extended period. Stock price volatility has increased amid concerns over slowing semiconductor sector profitability and investment. Financial imbalances related to the housing market and household debt require continued attention. Expects exports and investment to sustain strong growth.
- BoK Governor Shin said the recent stock market correction weighs on consumption, while a strengthening won likely helps boost consumption, Yonhap reported.
- New Zealand CPI (Q3 QQ) 0.7% vs. Exp. 0.8% (Prev. 1.5%); Y/Y 3.7% vs Exp. 3.8% (Prev. 4.1%).
DATA RECAP
- Japanese Stock Investment by Foreigners (Oct/17) -66.5B (Prev. 3545.5B).
- Japanese Foreign Bond Investment (Oct/17) -161.6B (Prev. -339.9B).
GEOPOLITICS
RUSSIA-UKRAINE
- A drone struck energy infrastructure in Ukraine’s Poltava region near Kremenchuk, according to a local official.
- US President Trump said they are the closest they’ve ever been to settling Ukraine/Russia war.
- Ukrainian President Zelensky said supports US proposal for trilateral talks at level of negotiators as soon as possible; Ukraine hopes for meeting not later than early November; Meeting could discuss peace and possible leaders’ summit.
- US envoy Witkoff said will continue with trilateral talks between the US, Russia, and Ukraine at the technical level.
MIDDLE EAST
- Iran’s IRGC Navy said four vessels transferring oil cargoes were struck in the Persian Gulf, while three other vessels hit sea mines yesterday west of the Strait of Hormuz, warning that US efforts to encourage passage could result in strikes on US bases.
- US President Trump said the US is doing very well against Iran, while Russian President Putin did not ask for anything in return over Hubbard.
- Flights have reportedly been suspended at Kuwait Airport, with no aircraft arrivals or departures recorded, Tasnim reported, citing unofficial sources.
- Yemeni forces reportedly targeted Saudi Arabia’s Jeddah airport, suspending operations and leaving four aircraft circling overhead, SNN reported, citing Arab sources.
- Three drones were reportedly launched from Houthi-controlled areas north of Al-Dhale towards Aden, Yemen, Al Hadath reported, citing sources.
- US warplanes were reportedly flying over northern Iraq, Sabereen News reported.
- US and Israeli militaries have reportedly developed plans for renewed strikes on Iran after the US midterm elections, targeting energy infrastructure, nuclear facilities and missile and drone arsenals, NYT reported, citing sources.
- Saudi Civil Aviation said King Fahd Airport in Dammam was attacked on Wednesday evening, Al Arabiya reported.
- Saudi Arabia’s Eastern Province was reportedly targeted by four drones, Naya for Iraq reported.
- A large explosion was reportedly detected in the Strait of Hormuz near an area where tankers have previously been struck, Fars reported, citing OSINT sources.
- Explosions were reportedly heard in Iran’s port city of Sirik, with claims that US forces struck an anti-ship missile launcher targeting vessels in the Strait of Hormuz, Israel’s Channel 12 reported.
- Iranian missiles were reportedly launched towards the Strait of Hormuz, Sabereen News reported.
- US military is reducing troop presence at bases across the Middle East, while the State Department is ordering further staff reductions at diplomatic posts amid regional threats and potential US military action against Iran, NBC News reported.
- Iran threatens to target US political figures if strikes resume, Fars News reported.
- US President Trump said on embassy staff told to depart, said don’t know that they are; we continue to beat Iran. On Russia-Ukraine, said I have the right to do sanctions any day.
- In the past few hours, there has apparently been a change in the American position in favour of a pre-emptive strike on Iran, according to a Haaretz correspondent, citing White House sources. White House sources explain the change mainly due to the great weight that President Trump gave to the assessments and intelligence that Defense Secretary Pete Hegseth presented to him upon his return from the meeting with Prime Minister Netanyahu.
- US State Department issued an ordered departure for non-emergency US Government employees and their family members in Saudi Arabia only.
- Two people killed in drone attack on oil wells in Al-Shaybah, reported Fars.
- No impact on operations in Saudi Aramco’s Shaybah oilfield following drone attack.
- Saudi’s Energy Ministry said air defences intercept drone attempting to target the facility at Aramco’s Shaybah oil field.
- Oil tanker being targeted near Iraqi territorial waters, reported Sabereen News.
- US officials said the US State Department is preparing to issue an ordered departure of some personnel and family members at US embassies across the Gulf. The move was due to a possible resumption of hostilities, particularly with Iran-aligned Houthi militia in Yemen.
- A few minutes ago, several explosions were heard from Sirik, Iran; the origin and nature of these sounds are still unknown, Fars reported.
- Saudi-led coalition said it is intercepting a drone launched towards the eastern region, Al Arabiya reported.
- Iran’s Foreign Minister said Iran is prepared to give diplomacy another chance if they see strong evidence of a sincere desire by US to build trust and reach solution, but if US chooses war over diplomacy, it’ll result in an even greater strategic failure.
- Houthi official said all negotiations have reached a deadlock because Saudi Arabia seeks to impose its demands on the Yemeni people, and this is not something that Sanaa will accept, Fars reported. This war has been imposed on us, and we will not accept that Saudi Arabia will delay and play with Yemen.
- Yemeni sources say Houthis launched a drone attack near Al-Dhaba oil port in Al-Shihr, Hadramawt, Sky News Arabia reported.
- US issues new Iran-related sanctions on entities and vessels.
- Several explosions in southern Saudi Arabia, reported SNN citing Arabic sources.
- Israeli helicopters flying in the sky of southern Syria, and continued transfer of military forces, equipment and deployment of early warning systems, are being carried out within the framework of preparation for a possible war with Iran, reported Mizan.
- Iran’s parliamentary speaker Ghalibaf met with the Supreme Leader, and discussed the latest developments of the US-Israel war against Iran.
EU/UK
DATA RECAP
- European New Car Registrations (Sep YY) 9.3% (Prev. 4.5%).
2.NORTH AND SOUTH KOREA/
NORTH KOREA
SOUTH KOREA/USA
JAPAN//
JAPAN CHINA/USA
3 CHINA
4. EUROPEAN AND SCANDINAVIAN COMMENTARIES PLUS NATO
FRANCE/
“Mobilization Will Be Massive”: French Govt Plans To Send Soldiers To The Streets After Admitting Failures
Thursday, Oct 22, 2026 – 02:45 AM
French soldiers will take over guard duty so that police and gendarmes can be moved onto the streets for Saturday’s expected protests, Interior Minister Laurent Nuñez told parliament on Tuesday.
Nuñez said troops from Operation Sentinelle, the anti-terror deployment, would replace internal security forces mainly on static guarding duties. Prime Minister Sébastien Lecornu said the same day that Saturday’s mobilization of forces “will be massive,” Remix News reported, ahead of a major protest planned for October 24.
Sentinelle was launched in January 2015 and keeps about 10,000 soldiers across France to guard against terrorist attacks, usually at places of worship, schools, tourist sites, railway stations and airports. It also covered the Paris 2024 Olympics and Paralympics. Nuñez described a post-holding role for the troops in this case, not a crowd-control one.
The government now admits it failed to contain last Saturday’s riots. Lecornu acknowledged lapses in intelligence gathering, said police had been positioned too rigidly and said authorities chose not to cancel planned police leave, Reuters reported. He blamed far-left groups and framed the crisis as a choice “between violence and the Republic”; those groups say the government underestimated anger over living costs and declining public services. Nuñez told parliament: “I deeply regret what happened. I accept my share of responsibility.” He offered his resignation, and Macron rejected it.
About 60,000 police and gendarmes were on duty nationwide on Saturday, October 17, when roughly 500,000 people marched against the cost of living (authorities told Remix 550,000; organizers claimed over 800,000). Nuñez called that too few for the large crowds of rioters and looters on the edges of the marches. He said police had “lost control” in some cities and admitted a “lack of anticipation.” Riots and looting hit Paris, Marseille, Lyon and other cities, and in Limoges an arson attack brought down the roof and tower of the historic town hall.
The toll so far is large. Euronews counts more than 2,500 arrests and Remix more than 2,400 detained, while Justice Minister Gérald Darmanin put the number in custody at over 2,330, 70% of them adults. Almost 1,000 members of the security forces were injured. Alain Di Crescenzo, president of the chamber of commerce, said more than 2,000 shops were hit and put the damage at “hundreds of millions of euros.” On Monday Lecornu asked regional authorities for “localised and partial curfews” and said nearly 200 Paris police investigators would comb footage to identify looters. Parliament is also setting up a commission of inquiry into the causes of the unrest. As we reported, 8 p.m. curfews followed in northern cities.
Nuñez is also considering banning demonstrations that have not been declared and could lead to public disorder. Declared marches could be caught too, he said, but only if organizers or their stewards give authorities reason to think things will get out of hand. For marches judged low-risk, routes should steer clear of public buildings and high streets, and intelligence services are to step up estimates of turnout, especially of the most radical participants. He said security forces need more “responsiveness and mobility” against “scattered” and “extremely mobile” groups, and told parliament: “We will be there.”
The playbook has a precedent. In March 2019, for the 19th Saturday of the yellow vest protests, Sentinelle troops guarded sensitive sites so police could focus on order, and demonstrations were banned on the Champs-Élysées and in central districts of Bordeaux, Toulouse, Marseille, Nice and Rouen. Police made 31 arrests and issued 15 fines for entering banned areas, out of 2,322 street checks in Paris, NBC News reported. Macron brushed off opposition criticism of the army’s involvement: “Those trying to scare people, or to scare themselves, are wrong.”
Ministers of that period drew a line at confrontation. Armed forces minister Florence Parly said it was “hors de question” to put soldiers face to face with protesters, and said Sentinelle would relieve police and gendarmes of counter-terrorism tasks. Nuñez’s description of static duties fits that model, though the government has not said where in the country the troops will be posted.
The unrest is also reaching the bond market. We reported this week that French 10-year yields hit 24-year highs near 5%, with the spread over German Bunds close to 160 basis points and Moody’s due to review France’s Aa3 rating, which carries a negative outlook. Earlier, we described the country as entering a “point of no return” as the riots spread.
END
FRANCE:
French Counterterror Police Arrest ‘Ultra-Left’ Activist Over Limoges City Hall Fire
Thursday, Oct 22, 2026 – 04:15 AM
French police on Tuesday arrested a 34-year-old man suspected of taking part in the October 17 arson of Limoges city hall, three days after the riots that gutted the 1883 building. The elite RAID unit’s Bordeaux branch took him at 6:15 a.m. in a small, isolated house at Val d’Issoire, in the Haute-Vienne department, according to the Limoges prosecutor’s office. The prosecutor called him a “person suspected in the fire.” He is presumed innocent and has not been charged.
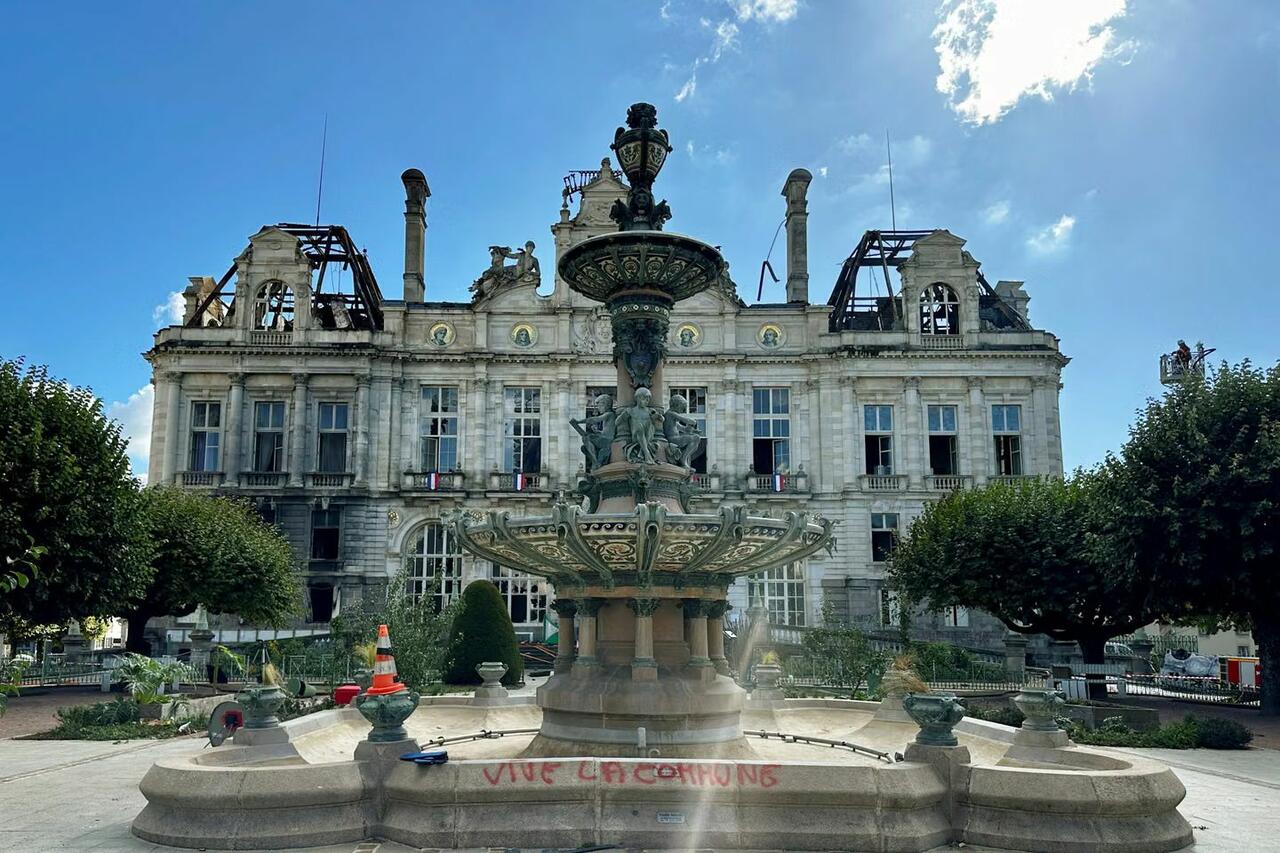
A source close to the case told Franceinfo he is an “ultra-left activist” already on the “fiché S” security watchlist. Some outlets first reported his age as 40; Franceinfo corrected it to 34. The prosecutor said investigators identified him through “painstaking” cross-checking of images and videos. ICI, the public radio network, reports that he is from the neighboring Creuse department and is suspected of earlier sabotage of TGV overhead lines and construction sites. His record was clean until an appeal court convicted him of violence against a police officer at an October 2024 protest in Guéret, a ruling he has taken to the Court of Cassation, so it is not final.
The Justice Ministry says he was not alone. Spokesman Sacha Straub-Kahn told ICI that “we are certain, from the images, that this person did not act alone,” calling it a “manifestly concerted action” and putting the crowd in front of city hall at 500 to 700 people with “fairly substantial pyrotechnic means.” No accomplice has been named or arrested. The only source for the ultra-left label is an unnamed one, and neither the prosecutor nor the ministry has said what role the suspect is accused of playing.
Custody, which began Tuesday, can run to 96 hours because the case falls under the special regime for organized crime. The investigation is run jointly by Haute-Vienne police and the national counterterrorism sub-directorate (SDAT). The national anti-terrorist prosecutor’s office has not taken the case, but is following it. Justice Minister Gérald Darmanin said Monday that anti-terror prosecutors would soon decide whether to treat the fire as a suspected terror attack.
The fire itself began around 6 p.m. Saturday, when masked protesters entered the town hall and set it alight, according to the prefecture. Prefect Maurice Barate said the fire was set deliberately. Overnight the roof and belfry collapsed, and only the modern rear section was saved. Nineteen people were taken into custody that day, and four police officers were seriously hurt. Prosecutors opened an inquiry into destruction of property by dangerous means by an organized group.
Mayor Guillaume Guérin says the state left his police to face the mob. Guérin, of the center-right Republicans, told Sud Radio that national police ran out of crowd-dispersal grenades at about 3:30 p.m. and fell back, and that he saw about 700 infiltrators among a march of roughly 5,000 (a figure the outlet did not verify). He told Public Sénat that 400 rioters faced only 30 municipal police officers, and that the state is “in part responsible” for what happened. He has asked for a special rebuilding plan like the one for Notre-Dame, full state funding of what insurance does not cover, and has said he may resign if he does not get it.
Reacting to the arrest, Guérin said he expects the courts to be “up to the task” and wants the suspect jailed, while noting the presumption of innocence, because “he destroyed the house of all Limousins.” He has secured a riot-police company for next Saturday, saying he needs national police and CRS officers “to maintain order.” Prime Minister Sébastien Lecornu is due to visit Limoges on Friday.
BRANDON SMITH…
The Turd-Eaters: France Gives Us A Lesson On The Pillager Class
Wednesday, Oct 21, 2026 – 11:50 PM
Authored by Brandon Smith via Alt-Market.us
Over the years I have written frequently about what I call the “Pillager Class” and the “Producer Class” in an attempt to explore the reasons why certain people, groups and cultures always seem to turn to looting and destruction rather than building anything of value of their own.
It is a threat the west has been dealing with for thousands of years: We engineer and create and plan for the future, and instead of doing the same, the pillager class decides it’s easier to take what we have. Sometimes they are subtle like a parasite, and sometimes they’re not so subtle, like a swarm of locusts.
There are numerous theories on why this happens. Some think it stems from genetics, others from low IQ, others think it’s purely a cultural phenomenon, and some people argue that it’s a mere reactionary response to poverty. I suspect it’s a combination of all these things. At bottom though, it seems that certain groups are simply born with the pillager instinct; a subset of the populace perpetually stuck in scavenger limbo.
A good comparison to understand this is the classic “lottery winner” dilemma. Data suggests that around 70% of all lottery winners lose every dime they won in 5 years or less. It doesn’t matter if it’s thousands of dollars or millions of dollars; they can’t seem to keep their hands on wealth.
They go from cash windfall to bankruptcy and financial failure so quickly, winning the lottery is often treated like a curse rather than good luck. This happens because they are incapable of planning for tomorrow. Their brains are ostensibly stunted, and they can only think in terms of the present moment. They are doomed to live in poverty because they are incapable of growing beyond their most base desires.
The pillager class is very similar. You can take them out of the global ghettos, bring them to your home and give them every opportunity imaginable to improve their circumstances, and yet, they will always choose thievery and barbarism instead. The only thing that might change is the complexity of their crimes.
Somali daycare and medical fraud in the US is a prime example. Fake college degrees and the H-1B theft of American jobs by Indian scammers is another. The Muslim “Silent Jihad” – a strategy of invasion through false integration, is also a pressing threat.
These people aren’t thankful for the opportunities handed to them. They believe they are entitled. In every case they argue that it is Americans who should be grateful for the migrants on our soil, for it is they who “built our country” (Third world immigration to the US was highly restricted until the mid-1960s, so this claim is nonsense). They don’t care that their invasions will eventually kill the golden goose. Some of them WANT to kill the golden goose.
In France right now, migrant rioters say they are looting and burning because they want more. More access to education. A better cost of living standard. More influence in government. All of this is a lie; what they really want is an excuse to steal whatever isn’t bolted down and then tear apart the rest. But it’s interesting that their moral argument for ransacking Paris is that they are owed more freebies in a country that already took them in. This tells us all we need to know about them.
Beyond the average pillager’s tendency to covet what the west has, there is an element of conspiracy which feeds the multicultural influx. In my article “Pillagers vs Producers: There’s Only Two Ways To Save The Western World”, I look specifically at the alliance between third world cultures and Marxist activism. This alliance is the source of the radioactive sludge that is giving the west cancer. It is this partnership that fuels the rise of migrant incursions into the western world.
Those of us trying to fight against the organized demolition of our society are certainly not the first to see the danger coming. I recently came across a book which I can only call prophetic – A book which describes almost everything happening in the world today, and it was published back in 1973.
“The Camp Of The Saints”, by French author Jean Raspail, has been banned in many libraries around the world while the writer was accused of “racism” and “xenophobia” for his fictional depiction of a migrant onslaught in Europe, starting in France and leading to the fall of the west. The story is set in the near future and reads like a timeline of current events.
The root premise of the The Camp Of The Saints is that a demonic partnership exists between the liberal left and third world pillagers. The nihilistic progressives, reveling in atheism, Marxism and globalism, are represented by the character of “Ballan”, an arrogant and godless leftist philosopher very similar to the French Marxist, Jean Paul Sartre.
Ballan travels to the squalor of India as part of a “humanitarian mission” to send tens-of-thousands of migrant children to be adopted in Europe. The group is eventually accused of having nefarious motives to use pity and guilt to undermine the west. Ballan essentially admits to the plan, and screams at his accusers that borders, nations and cultures are “rubbish” that must be destroyed.
In his fury, Ballan marches onto the streets of Calcutta and stumbles across an Indian man referred to as the “Turd-Eater”; an absolutely pathetic specimen of a human being. The Turd Eater is part of the “untouchable class” in India and he works as a “dung roller”; a person who collects human feces from the streets and rolls the manure into bricks to be used as fuel for fires. He is also known to eat the bricks in times of starvation (all of this comes from very real practices in the recent history of India, unfortunately).
The Turd Eater is a large man charged with the care of his deformed son, who he often carries on his back. The child cannot speak and only makes incomprehensible noises. (Until the past decade, consanguineous marriages or inbred marriages in India represented around 23% of all marriages in the country. That rate has now supposedly fallen to 11% but remains an ongoing issue in rural areas).
Ballan sees the encounter as a miracle, a profound moment. He reasons that this man and his child have experienced the pinnacle of suffering and thus they possess the ultimate knowledge of humanity (This is a common delusion among leftists – the notion that the “oppressed classes” posses a superior knowledge of life and should thus be treated as precious, or perhaps even worshiped).
The Turd Eater dreams of going to the west, and Ballan seeks to help him. In the process, Ballan turns the Turd Eater into a demagogue, a leader of the migrant masses. The philosopher whispers dark rhetoric into the man’s ear, which the man then repeats, mixing eastern and Christian religious concepts into a theosophical gibberish about the East coming to save the Christian west. His deformed child becomes a messianic symbol of the movement, an “inspiration” for mass immigration.
Again, this is brilliantly prophetic. Today, the political left constantly feeds talking points to third worlders, teaching them to appeal to our Christian and Constitutional principles. How often in the US have we heard migrant representatives talk about the First Amendment, freedom of religion, America as a “melting pot”, and the conservative “Christian duty” to help those in need?
These are all carefully scripted manipulations designed to use our own ideals to destroy us. As I have covered in past articles, these claims are based on false and twisted versions of Biblical teachings and misrepresentations of the intentions of the Founding Fathers. At no point ever has western heritage called us to accept responsibility for the pillager class.
Ultimately, the character of Ballan falls victim to his own creation. A massive migrant army sets out under the command of the Turd Eater to ride an armada of flotillas to France, and Ballan seeks to join them. Instead, they beat him and drown him in the dirty and disgusting Ganges river simply because he is white.
Meanwhile, leftist politicians and activists in Europe welcome the migrant invasion with open arms in the name of empathy and humanitarianism. This leads to more flotillas and caravans flooding into the west. Eventually, westerners are culturally replaced as victims of genocide. The people who do try to fight back are accused of racism and their efforts are undermined by lack of strong leadership.
The leftists treat the destruction of the west as justified and they cheer the replacement, only to be replaced themselves. The story is about the ideological self-sabotage of the west through liberalism. It is a warning from 50 years ago that is coming true today.
The one thing that The Camp Of The Saints misses is the reality of an underlying and malicious agenda – The globalist influence, the NGO funding, the UN backing, all the elements of power that are maneuvering and helping the third world replacement to happen. They aren’t creating the pillager class, it already exists and has always existed. Rather, the globalists have identified the pillager class as a useful weapon and they are aiming the barbarian horde at the US and Europe to fulfill the Marxist vision of a borderless, homogenized socialist empire.
This is a righteous act according to progressives, because of the West’s colonial past. In their minds, westerners ARE the pillagers. As Marxist Jean Paul Sartre once said:
“But to become natives altogether, our soil must be occupied by a formerly colonized people and we must starve of hunger…”
“You will be convinced that it would be better for you to be a native at the uttermost depths of his misery than to be a former settler.”
The demonization of western settlement relies on an ignorance of history and a romanticized image of “indigenous peoples.” The west brought technology, infrastructure and an alternative to the savagery of the ancient world. There are many disturbing accounts of these archaic cultures written by explorers, missionaries and native witnesses. They read like the most grotesque horror stories you can imagine.
Brutal slavery, torture, mass murder, child sacrifice, rivers of blood, the stench of death permeating the air, all of it at the hands of more powerful tribes subjugating smaller tribes. The old world was a pagan hell on Earth. The average leftist growing up in the unprecedented security and sanity of the modern west cannot comprehend the nightmares that existed before settlers arrived on the shores of Africa, Asia and the Americas.
When we exited some of these places in the name of “social justice”, we left behind stunning infrastructure. Billions upon billions of dollars in advanced systems and industry, clean water, waste management, healthcare and transportation.
The natives ended up dismantling all of it out of greed or they let it rot out of laziness. Many countries reverted economically and technologically. Even nations like India which still maintain deep trade and political ties to the west are giant dung heaps otherwise, with mountains of garbage and feces in the streets. They simply cannot run their civilizations properly, and so, they all want to travel to the west.
It is time to put an end to the western self-loathing and nihilism championed by the political left. We need to accept the fact that our culture is superior in design, or at least it was until the progressives got hold of it. And, ultimately, we need to adopt a philosophy of selectivity, merit and a refusal to compromise. If this means deporting third worlders in large numbers, so be it. If it means booting out militant leftists and sending them to an island somewhere, so be it.
They declared war on us first. There is no rule that says we have to let them win. As Jean Raspial notes in The Camp Of The Saints:
“In the strange war that was coming, victory would go to those who loved themselves the most…”
The novel describes the death of the west as suicide by empathy; a condemnation of the liberal tendency to view the dregs of the world as our moral responsibility. But it is not the responsibility of the west to save the world. If we did save it, the only practical method would be colonialism.
Bringing the west to the third world is the only way to pull them out of the gutter. Bringing the third world to the west is a sure way to drag us all into the gutter. After a decade of invasion by the pillager classes into the US and Europe, after the recent infestation of the Spanish enclave of Ceuta, after the riots and looting we are seeing in France this week, the terrible end result is predictable and undeniable.
The truth is, if the downfall of our civilization continues, it is only because we allowed it to happen.
We publish a variety of perspectives. Nothing written here is to be construed as representing the views of ZeroHedge.
END
FRANCE
French Police Identify Antifa As The “Ideologically Distinct Group” Behind The Riots Despite Democratic Denials
Thursday, Oct 22, 2026 – 08:45 AM
Authored by Jonathan Turley via JonathanTurley.org,
Years ago, I called Antifa the Keyser Söze of the left, after the character in “The Usual Suspects.” In the film, the character Virgil explains how Söze stayed in the shadows to be portrayed as a myth: “becomes a myth, a spook story that criminals tell their kids at night.” The strategy was too simple: “the greatest trick the devil ever pulled was convincing the world he did not exist.”
Democratic leaders have long fostered the myth around Antifa, the largest and most violent group on the political left. For years, they have denied the existence of the group even as members were charged with crimes (including terrorism). Now, the French authorities have found that the nonexistent group is the largest of three “ideologically distinct groups” responsible for the violence in France. It appears that either the entire French security system is delusional or the trick is up for the American left.
I have testified before Congress about Antifa, run columns on the organization for over a decade, and written a book discussing Antifa. Yet, Democratic members continued to insist that there is no such group, while other leading Democrats have praised Antifa for instilling fear in MAGA.
It was a curious claim even then, when other Democratic leaders were actively pandering to the violent group.
Former Democratic National Committee deputy chair Keith Ellison – now the Minnesota attorney general – proclaimed that Antifa would “strike fear in the heart” of Trump. His own son, Minneapolis City Council member Jeremiah Ellison, declared his allegiance to Antifa in the heat of the protests this summer.
However, Democratic leaders and pundits have repeated the mantra that there is no such group despite political violence on the left spreading across the country.
Rep. Dan Goldman (D., N.Y.) dared anyone to name a single member of Antifa despite the charging of Antifa members with various serious crimes.
Former House Judiciary Chair Jerrold Nadler (D-N.Y.) was widely ridiculed for denying the existence of Antifa.
Others on the left have joined Goldman in this absurd claim. Late-night host Jimmy Kimmel devoted part of his monologue to assuring viewers that Antifa is no more than a mythical “chupacabra.” “You understand there is no Antifa,” he said. “This is an entirely made-up organization.”
The denials continued even as FBI Director Christopher Wray debunked deniers like Goldman. “Antifa is a real thing.” European countries have banned Antifa site due to their criminal conduct while Antifa candidates have been elected to office as members of the group.
Now, French authorities identified Antifa as the largest of three “ideologically distinct groups” responsible for the violence in France. It appears that Keyser Söze is in the open, but Democrats maintain the FBI, Justice Department, and various countries are simply delusional.
The problem is when the myth becomes reality. Left-wing pundits and politicians are caught in this denial web where they have to maintain the absurd idea that Antifa is just an idea.
Some of us have been writing about Antifa for years after watching them intimidate and threaten faculty and students on campuses. One such student came from my campus and proclaimed that Antifa was winning after his arrest for property destruction.
When another radical was arrested after taking an axe to a congressional office, he self-identified as a member of Antifa.
Before Kyle Benjamin Douglas Calvert, 26, implanted an IED device outside of Alabama Attorney General Steve Marshall’s office in downtown Montgomery, he put up stickers reading “support your local Antifa.”
Numerous Antifa members have been arrested, including some who claimed to be journalists.
Many protesters belong to Antifa groups that have names like “Rose City Antifa” and offshoots like Love and Rage and Mexico’s Amor Y Rabia. Antifa members have been elected to the French and European parliaments.
Rutgers Professor Mark Bray’s “Antifa: The Anti-Fascist Handbook,” called by some the “Antifa bible,” explains that the group is united in its opposition to free speech. “Most Americans in Antifa have been anarchists or antiauthoritarian communists,” he writes. “From that standpoint, ‘free speech’ as such is merely a bourgeois fantasy unworthy of consideration.”
Yet, Democratic leaders seemed to be adopting the 1967 ‘Guide for the Married Man’ when caught with Antifa allies or associations:
EUROPE
European Regimes Renew Their Attacks On Free Speech
Thursday, Oct 22, 2026 – 05:00 AM
Authored by Ryan McMaken via Mises Institute,
In recent weeks, German and French politicians have denounced free speech, and especially the concept of “freedom of speech” as long envisioned in the libertarian tradition of natural rights. French President Emmanuel Macron on September 29 stated that”The so-called American ‘free speech’ today, which some people have promoted, is the opposite of free speech.” Macron compared speaking freely as comparable to walking down the street assaulting other people.
A week earlier, German Chancellor Friedrich Merz declared,”Don’t anyone come to me with free speech!” He asserted we must “still be able to protect citizens from false information.”
Both were speaking on issues related to online speech through social media and similar platforms. Both see a grave danger to the ruling class posed by the ability of unvetted or anonymous users to post opinions freely.
In both cases, these attacks on freedom have been in the context of European regimes’ repeated efforts to impose new regulations on social media platforms to limit speech.
This has been going on for several years. For example, back in February, Macron stated that “free speech is pure bullshit.”
In Europe, the anonymity issue is no minor affair. In Germany, there are literal speech police who will arrest ordinary citizens merely for saying things online or reposting memes. It’s easy to see why anonymity could be an essential tool in posting ideas and facts the regime doesn’t like.
A European regime insisting on abolishing online anonymity is essentially tantamount to announcing that these regimes want the ability to make more arrests for wrongspeech. This is a growing problem across Europe, and a 2025 study concluded that British police were making 30 arrests per day for non-violent “offensive online messages.” Under British law, one can be prosecuted for hurting someone else’s feelings. That’s not how British apologists describe it, of course, but that is the essential reality.
Euphemisms for Censorship
Whether we’re talking about France, the UK, or Germany – all places where the despotic enemies of free expression have seemingly free rein – the regimes’ forces do not, of course, come right out and say that they support censorship.
They couch their censorship in the soft language of Leftwing ideology. The claim is that speech must be regulated in order to combat “hate speech” or to reflect the “common good” or to combat “disinformation.”
To wit, in recent years, European politicians have insisted that speech be made to fit into “a common framework” – to use Macron’s phrasing – and to be subject to some standard determining what is “false information.”
But here is the rub: Who is to determine what falls within this common framework? Who is to determine what constitutes “false information”? It is the ruling oligarchy and its political allies, of course, that will determine if some proposed fact or idea is to be allowed to be spoken freely.
The ruling elites will decide if some sentiment or phrase is to be defined as “hate speech” and thus will be punished by state police and regime jailers. The ruling elites will determine what is “science,” and therefore what constitutes “disinformation.” This was on full display in the United States during the Covid Panic, when the government bureaucrat Anthony Fauci effectively declared “I am the science.”
It is through these state-created and reasonable-sounding “exceptions” to free speech that the regime smuggles in its despotism.
For example, this has been the case for many years with defamation laws. Those who defend legal sanctions for “defamation” essentially advocate for government censorship to combat hurt feelings. Moreover, for centuries, governments have used defamation laws as a means of punishing criticism of the regime. Laws against “seditious libel” – employed by absolutist kings of old – have always essentially been laws against free speech.
An Assault on Truth Itself
The individuals who are directly punished will not be the only victims of this censorship. Truth and critical thinking themselves will be the victims as the regime’s subjects will no longer be allowed to fully and publicly examine the veracity of claims made by the ruling elites. It means that “truth” will be whatever the regime says it is.
This problem of using free speech to hide and distort reality itself was well described more than 100 years ago by the radical free-market libertarian Vilfredo Pareto. Pareto was no naive democrat who thought that freedom could necessarily be protected by elections or written constitutions. But he did understand that freedom of speech is at the very foundation of a free society, regardless of the type of regime or whatever other freedoms might be protected in writing.
Even as Pareto was facing the rise of violent radical socialists in Italy – and thoroughly doubted the ability of the liberal state to deal with it – he never wavered on the key importance of free speech. That is, Pareto remained a dogmatic hardliner on free speech, and in this was like nearly all libertarians before him, from the anarcho-capitalist Molinari to the American Revolutionaries.
Not surprisingly, then, Pareto concludes there were no “mitigating factors” that could legitimately limit speech in the name of some common good. Writing in 1916 he stated:
[B]efore a theory can be considered true, it is virtually indispensable that there be perfect freedom to impugn it. Any limitation, even indirect and however remote, imposed on anyone choosing to contradict it is enough to cast suspicion upon it. Hence freedom to express one’s thought, even counter to the opinion of the majority or of all, even when it offends the sentiments of the few or of the many, even when it is generally reputed absurd or criminal, always proves favourable to the discovery of objective truth (accord of theory with fact). …
Pareto goes on to insist that there can be no exceptions, even for the sake of protecting “truths” long held to be precious. Not even those assertions said to be essential to humanitarianism can be considered protected from the scrutiny of free speech. He continues:
Nor can an exception be made for humanitarian dogmas, nor for the dogmas of the sex religion so dear to Senator Berenger and other geniuses of the same magnitude. Let us keep the point strictly before us: There is no scientific liberty unless everything is open to doubt – even Euclid’s geometry and three-dimensional space. It is ridiculous to say that one is disposed to grant liberty for “truth” but not liberty for “error”; for the point at issue is none other than to discover where the “truth” lies and where the “error”; and it cannot be settled if “error” cannot be defended by every possible reason that can be advanced in its favour. Only after such reasons have been validly refuted is judgment of error affirmed – pending further investigation. Many people fail to understand that, because in judging of truth or error they substitute a criterion of sentiment for the logico-experimental criterion.
Clearly, the fact that free speech is now so under siege in Europe is simply the latest evidence of how far out of favor old historical liberalism has become in Europe. Every year, Europe more enthusiastically embraces its worst tendencies in which human rights are repeatedly jettisoned to protect the “rights” of those who rule over the continent. Yet, the antipathy toward free speech also demonstrates the weakness of the European regimes and their political programs. Were the German, French, and British states not so hampered by political division, economic decline, and public dissatisfaction, they would not be so fearful.
Americans have no yet traveled so far down this road. But the foundation is already being built. Republicans support laws deeming all criticism of a certain foreign government to be “anti-semitism” and therefore “hate speech.” Covid laid bare the American Left’s enthusiasm for anti-speech tyranny. All that is necessary for the First Amendment to be wiped away is for a handful of federal judges to agree with the enemies of freedom. There is no guarantee.
END
EUROPE
EU Better Hope Global Warming Is Real As NatGas Withdrawals Begin With Dangerously Low Reserves
Thursday, Oct 22, 2026 – 06:55 AM
European natural gas futures climbed for a second day as countries began drawing on stockpiles already at exceptionally low seasonal levels.
Brussels is now left hoping that Greta Thunberg’s global warming narrative is real to ease pressure on the region’s fragile energy balance. Even then, one or two severe cold snaps could accelerate inventory depletion, intensify competition for LNG cargoes and push the energy-stricken continent toward another winter crisis, particularly if disruptions around the Strait of Hormuz continue to constrain LNG supplies.
Gas Infrastructure Europe data showed that EU NatGas inventories declined for the first time this year.
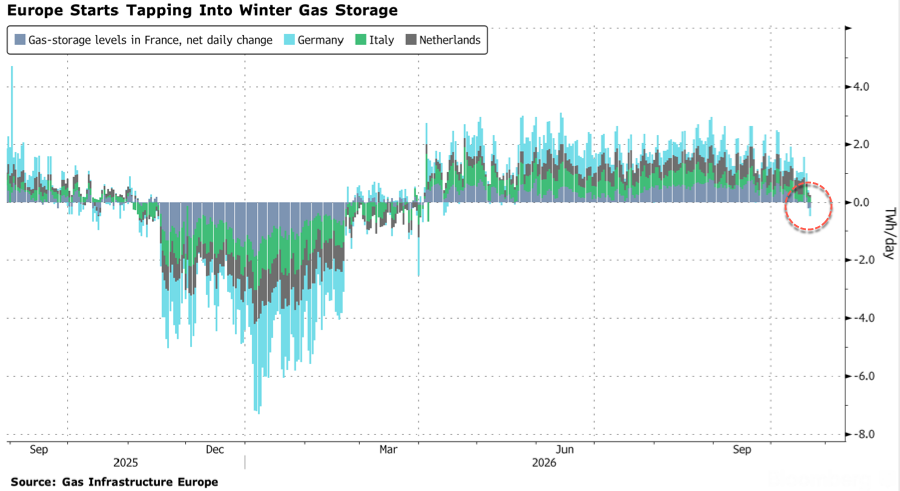
Storage sites are about 74% full, well below the 15-year average for this time of year and, according to Bloomberg data, at the lowest seasonal level in records dating to 2009. Germany’s gas storage sites are just 61% full.
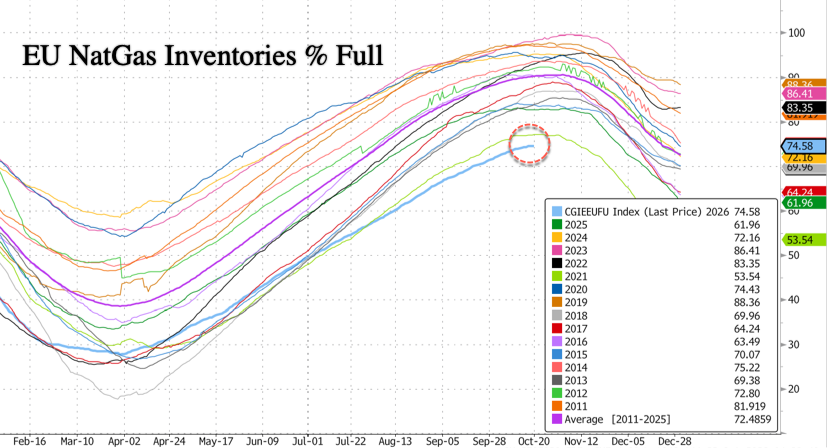
Dutch front-month futures, Europe’s benchmark, breached 90 euros a megawatt-hour around 9:42 London time. Prices reached their highest since late 2022 earlier this week (read report) and have nearly tripled compared with last winter, increasing pressure on industry, freight and, of course, households.
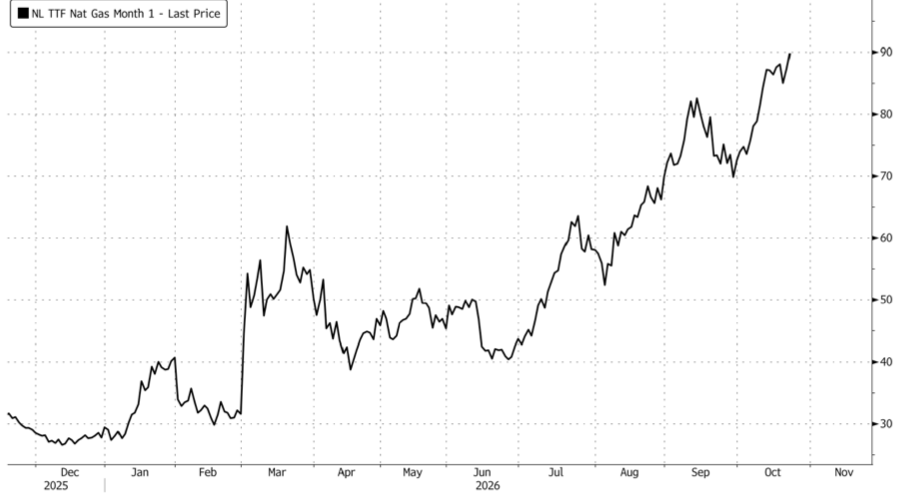
The smaller buffer leaves Europe increasingly dependent on the international market, where it must compete with Asian buyers. This suggests TTF prices will have to rise sharply as the Hormuz maritime chokepoint remains chaotic.
Mild October weather across the bloc has eased heating demand and allowed utilities to stockpile additional reserves. The latest forecasts show warmer conditions returning to northwest Europe next week, though temperatures will fall next month, offering a warning of what lies ahead as the Northern Hemisphere enters the winter period.
Perhaps Europe will experience a slightly warmer-than-average winter because of strong El Niño conditions. But now is when elites in Brussels, who endlessly pushed the global warming narrative for years, must hope they are right. If they are not, all it could take is several cold snaps this winter to deplete inventories across the bloc to dangerously low levels, leaving less cushion to absorb shocks.
Goldman Sachs commodities expert Daan Struyven warned earlier this week that EU natural gas prices could soar to 150 euros if Gulf LNG exports remain at just one-quarter of normal levels and a more severe winter boosts heating demand. The full report can be read here.
END
ITALY
First French Riots, Now Italian Trucker Blockades: What’s Driving Europe’s Rapid Descent Into Chaos?
Thursday, Oct 22, 2026 – 08:05 AM
Social unrest in France has plunged President Emmanuel Macron’s government into turmoil, while demonstrations elsewhere in Europe are converging with mounting concerns about sovereign debt. Italy’s trucker blockades now threaten critical food supply chains, adding another source of disruption.
Local outlet Italia 24H Live reports that trucker demonstrations in southern Italy are disrupting food deliveries and leaving produce to rot.
“Casertano, police operation to identify protesters at the truckers’ picket lines ahead of the gradual release of the areas. Those near the highways have been removed, while those in industrial and intermodal areas remain,” the outlet reported on X.
X user RadioGenoa said, “Total chaos in Italy today. Hundreds of trucks are stranded on the A1 motorway due to a protest on high fuel prices and the rising cost of living. Southern Italy is paralyzed: supermarkets have been emptied, and gas stations have run dry. It is a disastrous situation.”
The result:
Taken together, these developments raise a very important national security question: are separate movements responding to shared economic pressures, or are networks coordinating or amplifying unrest across borders?
It doesn’t matter whether the groups are on the left or the right. Certainly, a timeline has been accelerated to cause maximum disruption across Europe as it faces the risk of a sovereign debt crisis, social unrest, and unfettered mass migration.
END
NATO/BLACK SEA
NATO To Increase Black Sea Presence Following Drone Attacks On Shipping
Thursday, Oct 22, 2026 – 02:00 AM
Authored by Victoria Friedman via The Epoch Times,
NATO will send additional military equipment and aircraft to the Black Sea, following a series of drone attacks on shipping vessels in the key waterway.
Ships wait in the Black Sea in Constanta, Romania, on Oct. 15, 2026. Andreea Campeanu/Reuters
Allison Hart, NATO’s principal spokeswoman, said in an Oct. 20 post on X that the assets will support surveillance, reconnaissance, and forensic activities.
The decision came after NATO ambassadors met at the North Atlantic Council, the defense alliance’s main decision-making body, to discuss Black Sea security.
“We will continue to stand united and ensure that we are ready and able to address any threat and to keep our one billion people safe,” Hart said.
NATO’s military spokesman, U.S. Army Col. Martin L. O’Donnell, said that in addition to sending the radar systems, drones, and patrol aircraft, allies will send or have sent intelligence agents and teams to conduct forensic examinations of explosives used against shipping vessels.
NATO has not attributed the attacks to any country.
The added presence comes in response to several Black Sea incidents in which drones struck cargo vessels.
Earlier this month, a number of cargo ships were hit off the Bulgarian coast of the Black Sea in the space of one week.
On Oct. 13, the Guinea-Bissau-flagged HS Dignity was sunk, and the Chelsea 3, sailing under a Maltese flag, registered in Odesa, and Ukrainian-owned, was also struck.
Drones struck two other cargo ships in the same waters on Oct. 6.
Bulgaria said that Russia was likely behind recent incidents off its waters. Russia’s ambassador to Bulgaria, Eleonora Mitrofanova, said at the time that she had no information from the Russian Ministry of Defense about attacks on commercial vessels.
Tankers Struck Near Romanian Coast
On Oct. 15, drones struck two chemical tankers near Romania’s Black Sea coast, setting them both ablaze.
The vessels were anchored near the Sulina Canal, which links the Danube River to the Black Sea. It is a major export route for Ukraine.
Romanian President Nicusor Dan called the situation in the waters “serious.”
“Commercial ships are being attacked and sunk. Seafarers killed, injured, and missing, very close to the shores of Romania and Bulgaria,” Dan said. “Lives, global trade, and critical infrastructure are at stake.”
Vladislav Maslennikov, director of the European Affairs Department at the Russian Ministry of Foreign Affairs, told Russian newspaper Izvestia on Oct. 20 that against the backdrop of NATO’s increased reconnaissance activities in the Black Sea, “the risk of incidents, including unintentional ones, is indeed increasing.”
Bulgaria, Georgia, Romania, Russia, Turkey, and Ukraine border the Black Sea, and it is a vital shipping route.
Russia is the world’s largest wheat exporter, and Ukraine is also among the world’s largest producers of grain and seed products – both use the Black Sea to export their goods. Consequently, the waterway has become a target for both sides in the ongoing war.
In recent months, Russian forces struck Ukrainian targets on the Black Sea, including the ports of Chornomorsk and Odesa.
Ukraine, for its part, has been targeting Russian grain and farming infrastructure in the waters.
END
UK
UK Landlords Offered More Than Double Council Rents To House Channel Migrants
Thursday, Oct 22, 2026 – 03:30 AM
Authored by Steve Watson via Modernity.news,
British landlords are being offered thousands more each month to house small-boat arrivals than local councils pay to shelter vulnerable British families, a Daily Mail investigation has revealed.
The deals come from Clearsprings Ready Homes, one of three Home Office contractors operating under multi-billion-pound taxpayer-funded contracts.
In one south London case, a landlord was offered £4,500 a month for a three-bedroom flat he currently rents to Southwark Council for £1,790. That is an extra £32,520 a year, plus bills, council tax and maintenance covered for three years.
The anonymous landlord told the Mail: “I already rent to Southwark Council, and they are able to offer significantly more than the local authority, which to me is bizarre. The council has a ceiling on what they are allowed to pay landlords like myself.”
He continued, “For a three-bed flat I get £1,790 from the local authority to house families, while I would rent it to Clearsprings for £4,500 per month. I didn’t go with them because it would have meant terminating my contract with Southwark Council and putting families at serious risk of homelessness. I am not prepared to do that. But many landlords just see it as an opportunity to earn more, and just go with them.”
Clearsprings is understood to be targeting properties already used for council tenants, students and vulnerable people, including those fleeing domestic abuse.
The firm, run by Graham King (estimated fortune £726 million), houses around 30,000 asylum seekers and reported £62.6 million profit on £1.4 billion turnover in the year to January 2025.
It is one of three contractors (alongside Serco and Mears) with contracts originally awarded under the Conservatives and running until 2029.
The National Audit Office has previously put expected Home Office spending on the main asylum contracts at £1.67 billion for 2024-25.
Shadow Home Secretary Chris Philp called it “a day of shame for Labour” and said: “It is insane that illegal immigrants who have broken our laws, and some of whom go on to commit appalling crimes against women and girls, are being prioritised above law-abiding citizens who work hard and pay their taxes.”
“Over 85,000 illegal immigrants have crossed the Channel under this Labour Government yet only seven per cent of arrivals are removed. This has led to a huge increase in HMOs and flats being used to house them – with over 93,000 people now in asylum accommodation,” Philp further urged.
A Home Office spokesman claimed that the department pays a capped contractual rate and that “any amount above that is covered by the contractor and not taxpayers.”
Officials pointed to hotel closures and claimed savings of more than £1 billion on asylum support since the election, along with 80,000 removals.
Meanwhile, Border Security Commander Duncan Capps has warned that nearly 3,800 migrants are currently waiting in camps between Calais and Dunkirk – almost double the usual number of around 2,000.
Capps told MPs: “I think the French estimate at the moment is that there is almost 3,800 people between those two camps. Previously it was broadly about 2,000 between them.” He added that larger boats and higher occupancy mean “it is only a matter of time till we have a mass casualty event in the Channel.”
Crossings so far this year are down on last year’s total, but the backlog in northern France shows demand remains high. Migrants typically make multiple attempts; French intercepts do not lead to detention, so the same people can try again.
Since Labour took office in July 2024, more than 83,000 people have crossed in small boats – more than the roughly 83,000 personnel in the British Army.
Total small-boat arrivals since records began in 2018 now exceed the combined strength of the Army, Navy and RAF. Former Royal Navy officer Chris Parry has described the intake under Labour as the equivalent of “six-and-a-half divisions of fighting-age men.”
Boat Migrants Who Have Entered The Country Now OUTNUMBER British Soldiers
It’s an ARMY…
Arrivals have at times averaged one every minute during peak periods. The system processing them has been described by a Home Office decision-maker who assessed thousands of claims as fundamentally broken.
ONE EVERY MINUTE: These Numbers Are UNSUSTAINABLE…
Record grants, a £4.3bn asylum bill and a coming wave of 1.3 to 2.2 million settlers
Speaking to The Times, the official known as J said: “At best 1 per cent of asylum seekers are genuine. There’s almost no aspect of the asylum system that isn’t either a massive fraud or just really dysfunctional. Nothing works as it should.”
Common patterns include package claims from the same nationalities using near-identical stories, staged photographs, and networks charging thousands of pounds to coach applicants to claim they are gay or face political persecution. BBC undercover work has documented advisers offering fabricated evidence for sexuality-based claims.
Proof: Britain’s Asylum System Is A Massive SCAM
They’re letting anyone into the country
The housing pressure is not new. Earlier this year the government signalled that every area of the country should expect to take a share of arrivals as hotels are closed and people are dispersed into residential property.
Watch: UK PM Wants EVERY Area In Britain To House Migrants
Telling Channel crossers they’ll be housed in leafy villages is the ultimate pull factor
Projections have suggested migrants could account for 40 per cent of new UK homes by 2030 under current trajectories.
Migrants Set To Swallow 40% Of New UK Homes By 2030
Amid welfare BILLIONS and crime surges
Local residents have repeatedly protested when HMOs or former military sites are converted for this purpose.
The current Clearsprings offers simply accelerate the same displacement dynamic with higher guaranteed rents funded through the contractor model.
The pattern is consistent: record crossings, low removal rates, an asylum system described by its own officials as riddled with fraud, and now private contractors using the resulting demand to outbid councils for ordinary housing.
British families on the housing list, students, and people fleeing domestic abuse are being asked to compete against a taxpayer-backed premium for people who arrived illegally.
The contracts were set under previous governments; the volume and the political choice to keep the system running at this scale sit with the current one.
Without a sustained reduction in arrivals and a higher removal rate, the housing pressure and the cost will surely spiral out of control.
END
FRANCE
French Budget Rejections Fuel Debt Crisis Fears As Yield Spread Over Germany Hits 15-Year High
Thursday, Oct 22, 2026 – 07:20 AM
French government bonds sold off earlier today, pushing 10-year yields above 5% as budget concerns and social unrest sent the country’s borrowing premium over Germany to its highest since 2011.
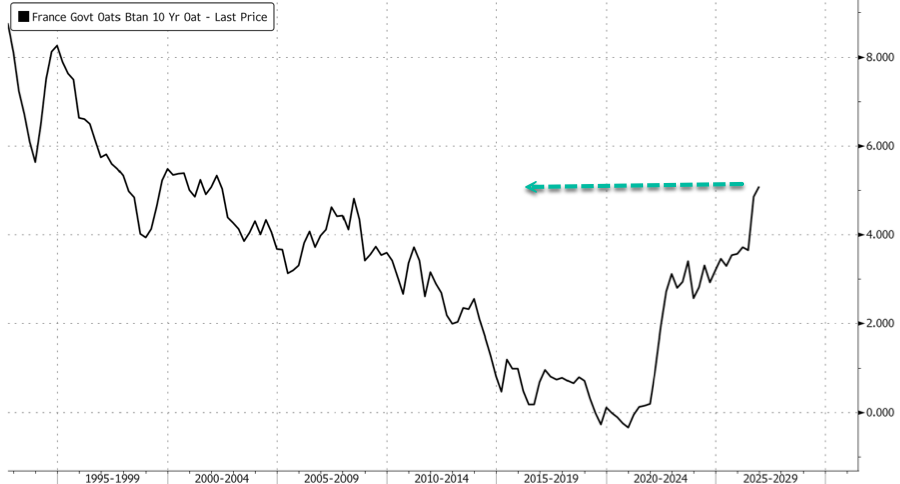
The French 10-year yield climbed to 5.11%, its highest since 2002, while the spread over equivalent German debt widened to 174 basis points, according to Bloomberg data.
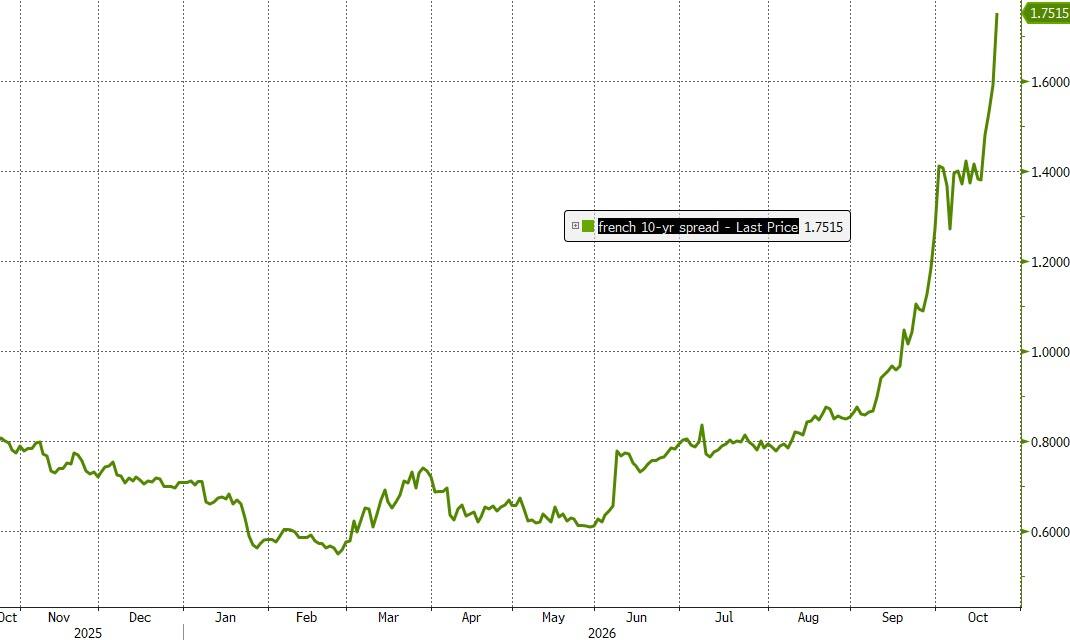
Separately, across the Atlantic, the 10-year US Treasury yield declined to 5.07% as EU equities weakened and US stock futures fell on concerns about an AI bubble.
UBS macro strategist Simon Penn wrote in a note to clients that the surge in French yields and the widening spread were due to “budget rejections.”
Penn added more color:
The French 10-year yield has opened Thursday higher, at 5.05%, up 3.6bp on the day so far. That’s pushed the spread to Germany out another 5.5bp.
The news flow has moved away from street protests and back to the roots of the budget. The government isn’t finding any takers for its budget proposals so far. Though full formal votes on the entirety of the budget are still to take place, this week has already seen MPs reject reduced spending measures.
News that the rejections mean some EUR10 bn of deficit reductions have already been cast to one side, and the most contentious budget matters are still to be discussed has raised further the prospect of budget failure.
A week ago the working assumption in the markets had been that MP’s would vent their frustrations with budget measures but stop short of outright rejection. That is not proving to be the case. The bond market is hence reacting accordingly. The next threat comes later Thursday afternoon if MPs indicate today’s proposals to cut spending are also to be rejected.
In a separate update, Penn said:
The biggest argument in the French parliament on Thursday is likely to be on the government’s proposal to limit pension indexation. Under the current plan, only around one-third of pensioners, primarily those on lower incomes, would continue to receive full inflation-linked increases, with larger pensions facing partial indexation or a freeze. The proposal is one of the largest sources of planned savings and has already encountered significant resistance during the committee stage. Healthcare measures are also likely to attract intense scrutiny, with MPs debating changes aimed at slowing the growth of health and pharmaceutical spending. More broadly, the debate will test whether the government can preserve enough of its fiscal consolidation programme to maintain its target of reducing the overall public deficit to 5.0% of GDP in 2027 from an expected 5.4% in 2026.
UBS global head of economics and strategy research Arend Kapteyn asked, “A Slowdown in European Fiscal Support?”
EU draft budgets suggest Eurozone stimulus drops sharply next year, but that assumes France delivers its planned tightening and it ignores the spending boost from the final RRF disbursements.
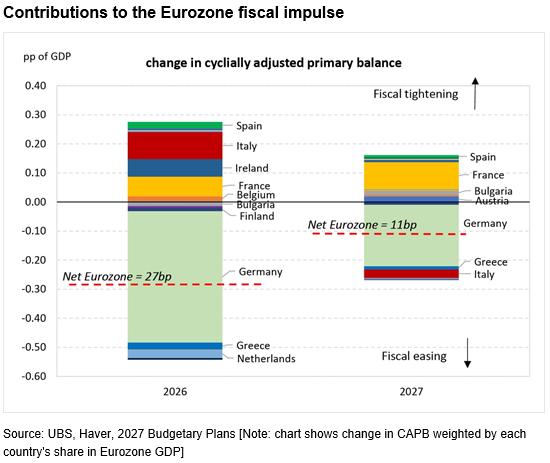
France’s mounting debt load is reviving a familiar European nightmare: the potential for another sovereign debt crisis, 15 years after the last one scared parts of the eurozone for years. This time, the warning signs are flashing at the heart of the bloc, with investors demanding a much higher premium to finance one of Europe’s largest economies, now combined with unfettered mass migration and social unrest, certaintly a new dynamic.
5.RUSSIA AND ISRAEL AND MIDDLE EASTERN AFFIARS
ISRAEL/IRAN/USA //THURSDAY
Brent Tops $112 As Tanker Attacks And Saudi Strikes Fuel Escalation Fears
Thursday, Oct 22, 2026 – 07:45 AM
Despite our overnight note titled “More Oil Is Leaving The Gulf Than Before The War”: And Here Comes The Shocking Freight Bill, Brent crude futures topped $112 a barrel early Thursday as fears of escalation in the Gulf area mounted and chaos and turmoil continued.
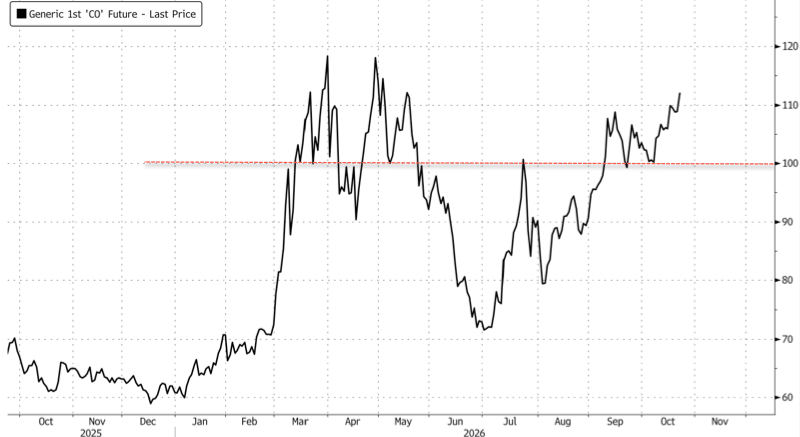
There’s a bunch of overnight news pushing Brent prices higher.
Let’s begin with news that the Iranian military claims it hit four “violating” oil tankers with projectiles while they were transporting crude in the northern Persian Gulf. The semi-official Fars news agency first published the report, citing an IRGC statement.
A separate report by Bloomberg says a drone strike on Saudi Aramco’s Shaybah oil field killed two people but left operations unaffected at the field, which has a production capacity of 1 million barrels a day. The risk is that further drone attacks could disrupt production at the oil field, which produces high-value crude.
There were also reports of a drone attack on King Fahd International Airport in Dammam that killed one person. Other news included a report that the US ordered some embassy personnel and family members to leave Saudi Arabia, further suggesting that security risks have intensified and/or could worsen.
“Continued kinetic activity and the risk of renewed escalation following the midterms are keeping a floor under prices,” said Rebecca Babin, a senior energy trader at CIBC Private Wealth Group. “The result is a market struggling to sustain rallies, but with limited conviction behind the selloffs as well.”
UBS energy specialist Dominic Ellis briefed clients earlier this morning on the latest developments in the energy sector:
A fresh wave of Houthi attacks on Saudi Arabia are keeping markets focused on escalation risk, along with reports that the US and Israel may be planning new strikes on Iran after the US midterm elections. Oil prices climbed on Thursday around these worries, and Brent was last up 3% to $112.25/bbl. US WTI crude gained 2.79% to $99.86/bbl.
A fresh wave of Houthi attacks on Saudi Arabia are keeping markets focused on escalation risk, along with reports that the US and Israel may be planning new strikes on Iran after the US midterm elections. Oil prices climbed on Thursday around these worries, and Brent was last up 3% to $112.25/bbl. US WTI crude gained 2.79% to $99.86/bbl.
The Hormuz Tracker on Wednesday showed a slight upward revision to Middle East oil exports based on a higher volume of dark transits, but volumes are well below the recent highs and prospects for a sustained improvement seem remote. Still, volumes have trended steadily up from the extreme lows of the April-June period. While the focus on an expanding geopolitical risk premium partly explains why oil prices remain elevated despite a higher level of Middle East energy exports (relative to the lows of a few months ago) there’s also an interesting demand datapoint which may be relevant: As UBS analyst Henri Patricot and team showed in the latest recent energy macro snapshot, China’s crude imports have risen by almost 3mb/d since the low in June (see chart below). China has played a crucial role in balancing international oil markets, and if oil imports continue to trend up or even remain stable at the current level, a tighter global market will limit downside for oil and leave risks skewed to the upside.
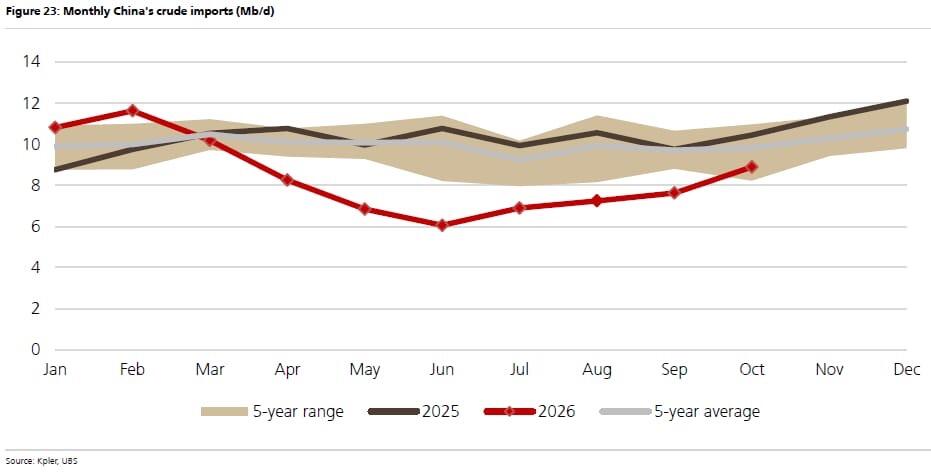
Even with ongoing security threats from Iran and its regional proxies, Middle Eastern oil flows averaged more than 24 million barrels a day in the week through Oct. 18, surpassing prewar levels, as we reported overnight. That recovery is encouraging, but there is a costly catch: tanker freight rates have ballooned as tankers navigate the critical waterway. The rebound in volumes provides only partial relief, with a substantial war premium still embedded in the cost of getting those barrels out to the international market, nevertheless, an ongoing global refining crisis.
END
US & Israel Prepare Post-Election Strikes On Iran Despite Escalation Warnings
Thursday, Oct 22, 2026 – 09:30 AM
At this point it seems both sides believe another major round of the US-Iran war is imminent. There’s been ample speculation of late whether President Trump will initiate another bombing campaign before or after the November midterm elections.
The White House may throw its hands up in the air and reason that Republicans are going to do bad in the elections anyway, and a pre-election bombing could be a Hail Mary effort at resetting the board, though one that will probably make it worse for the US force posture in the Middle East.
At the moment, the US State Department is evacuating further diplomats and their families from the embassy in Saudi Arabia, as Houthi attacks keep threatening airports, energy sites, and cities. A heightened state of alert is in effect for American citizens across the whole region.
Fresh reporting in the NY Times says indicates a renewed bombing campaign is likely to happen after the elections on November 3. The US and Israeli militaries have drawn up detailed plans for an attack, The New York Times reported on Wednesday evening, citing American officials.
It indicates that the plans focus on a short, intensive military operation that could last approximately three days – though we’ve all seen how ‘trustworthy’ these war timelines have been.
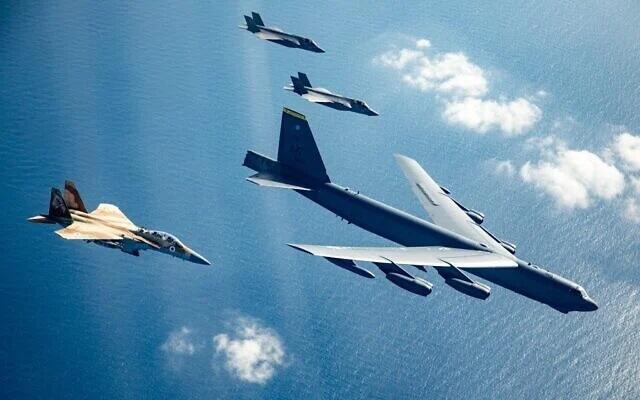
The NYT report notes, “As planning for a short but intensive operation progresses, the U.S. and Israeli militaries have stepped up exercises, flying planes over Iraq to practice strike maneuvers. Defense Secretary Pete Hegseth met with Prime Minister Benjamin Netanyahu in Israel this week to discuss new strikes, U.S. officials said.”
There has been increased aerial activity spotted over Iraq and Syria over the last days as well. These are speculated to be practice bombing runs.
For all the planning, even the NYT must point out: “Still, there are reasons to be skeptical that a renewed war would be any more successful than the first phase of intense U.S.-Israeli strikes between February and April. Those rounds of fighting drove up energy prices and inflation around the world, eroded security in the Middle East and severely strained the Pentagon’s supply of missile interceptors.”
This seems yet more ‘bombing campaign in search of a strategy’. It remains anything but clear what the admin’s ‘mission accomplished’ endpoint in Iran will be.
Iran has been defiantly signaling that it is ready for a prolonged campaign, and has at times boasted that it has kept up its missile and drone production throughout the entirety of the lull in fighting since at least mid-summer. Given we are month number eight of this quagmire, the following lines in the NYT report are somewhat laughably naive:
So far, however, Iran’s negotiators have been unwilling to make concessions on the nuclear program, insisting on deferring that issue until later in the talks.
Some U.S. planners are convinced that an intensive three-day campaign could cause enough economic damage to change the Iranian position.
Iran’s top security official, Gen. Mohsen Rezaei, the Secretary of Iran’s Supreme National Security Council and personal representative of Supreme Leader Ayatollah Mojtaba Khamenei, has stated the following to Drop Site News:
“If the question is whether Iran still has the ability to continue missile and drone operations, the answer is yes,” Rezaei said in an exclusive written interview. “The United States has valuable assets in the region. In the event of war, cables, data centers and artificial intelligence facilities could also come within range. If the conflict begins again, we will have a broader plan.”
“Everyone must understand that action against Iran carries a cost,” he added. “If diplomacy can bring about that understanding, we prefer diplomacy. But if the war continues, Iran has the tools it needs to keep responding.”
So whatever US-Israeli attack plan is triggered, it is very unlikely to be confined to a mere few days, as US officials are claiming once again.
More Latest Developments
via Newsquawk…
- For most of the war, Iran had an invaluable cushion: dozens of oil tankers holding millions of barrels of crude sitting safely in waters in Asia. Tehran steadily sold the oil to China, bringing in billions of much-needed cash. Now, that floating storage is gone. By mid-October, the reserves were fully depleted, according to analysts at Kpler, as a U.S. naval blockade prevented Iran from replacing the crude it normally sells to Chinese refineries. WSJ
- The US ordered some diplomats and their families to leave Saudi Arabia because of the threat from Houthi militants, as the Iran-backed group carried out more strikes from Yemen; four people were killed in two attacks on an Aramco oil field and an airport in Saudi Arabia’s Eastern Province. BBG
- The US and Israel have drawn up plans for renewed strikes on Iran after the midterm elections, with targets likely to include Iran’s energy infrastructure, nuclear facilities and missile and drone arsenals. NYT
- Aramco told staff to leave its headquarters in Dhahran and work remotely. RTRS
- Iran’s IRGC threatened US bases in the region if Washington keeps escorting ships through what it calls an “illegal” Hormuz route. BBG
- Saudi Arabia is in talks with foreign governments to give state-owned Aramco access to their strategic oil storage, as the kingdom seeks to make its supplies to customers more resilient during disruptions, Chief Executive Officer Amin Nasser said. BBG
ISRAEL TBN
END
IRAN
Pezeshkian Now Says Sanctions Must Be Peeled Off Before US Dialogue Returns
Wednesday, Oct 21, 2026 – 09:45 PM
Iranian President Masoud Pezeshkian appeared to add yet another stipulation to Tehran’s growing list of demands that must be met if it is to get back to the negotiating table with the US.
Pezeshkian stated that some Washington-led sanctions must be peeled back before direct dialogue can resume again. He voiced that the constantly ratcheting economic warfare is closing diplomatic avenues, and so there must be a ‘practical’ easing of pressure to set an atmosphere of honest talks.
“Threats and sanctions must be removed in practice to pave the way for dialogue. We cannot increase the intensity of sanctions and pressure every day, close the avenues of interaction, and at the same time talk about negotiations,” he wrote on X.
He is perhaps taking note of what’s happening in US-Russia relations, where President Trump just waived the sweeping Graham sanctions package just ahead of when they were expected to be enacted. Trump also earlier this month facilitated the diesel release deal with Putin.
Out of these overtures has come an increase in direct Moscow-Washington dialogue. It seems Pezeshkian is holding out for the possibility of a scenario like this, depending on how desperate the White House becomes for a peace deal.
While there’s no doubt that Iran’s economy is under immense pressure, and average people are feeling the pain on a daily basis – especially given the plunging Rial amid runaway inflation – Iranian leaders say the country can endure in this wartime state of survival for at least years more.
The Pentagon and the Trump administration have been saying something different, however.
US Central Command chief Brad Cooper claimed last week that “The financial strain on Iran’s military has become so significant that there are reports of Iran-aligned militia groups across the region withholding payments to their soldiers in order to funnel money back to the IRGC, which also is not paying its troops.”
At various times over the last several months, Iranian officials have admitted the deep financial pain within society and impacting government coffers, also amid the US naval blockade which prevents Iranian oil from reaching global markets.
Yet Iranian leaders have remained defiant…
For example, Iran’s Central Bank chief Abdolnaser Hemmati said earlier this month, “Despite all these pressures, the Iranian economy has demonstrated very good resilience, and the claim that Iran’s economy is collapsing is nothing more than an illusion.”
It continues to be a high stakes standoff and game of each warring side waiting the other out, seeing how much economic and political cost can be inflicted.
END
SAUDI ARABIA VS HOUTHIS
Saudi Aramco Evacuates HQ, All Staff Put On Remote Work
Thursday, Oct 22, 2026 – 03:00 PM
Saudi oil giant Aramco has evacuated its headquarters in Dhahran after it recently came under a Houthi ballistic missile attack out of Yemen.
Sources told the AFP and Reuters that the company told remaining staff to evacuate from its headquarters amid two weeks of intensified Houthi attacks across the region.
The City of Dhahran is in the Eastern Province of the country, and is the administrative center for the Saudi oil industry. There are sprawling residential areas for employees near the HQ, but there’s nothing to indicate the residential areas have been evacuated too.
Saudi-coalition spokesman Turki al-Maliki had announced on Oct.13: “Interception and destruction of a ballistic missile launched by the terrorist Houthi militia towards the city of Dammam.”
Reuters reported at the time, “A source with direct knowledge of the matter told Reuters the Aramco headquarters had been struck, though it was unclear if the building had been hit directly or by falling debris.”
The Saudis have released little information on what kind of damage was left in the wake of the strike on the Aramco HQ; however, there’s this new reporting in AFP and regional media:
Last week, two company employees who also spoke to AFP on condition of anonymity said a tower in the headquarters was struck. The “top three floors were gone,” one of them said.
Houthi attacks on Saudi civilian infrastructure, especially oil facilities and airports, have reached an unprecedented scale in recent weeks.
Twenty-two people have been killed in attacks on Saudi airports this month, according to an AFP tally of official figures.
Much of the staff at Saudi Aramco headquarters had already been working remotely, and it appears more and more are to going to remote desks on an indefinite basis.
“There was an evacuation order issued for these staff, no specific reason was given,” a source told AFP.
Airports in the region, and across the Saudi kingdom – including in the capital of Riyadh – have also been under frequent attack. The US Embassy in the capital is currently also evacuating more diplomats and their family members.
END
IRAN/KURDS
Iran Deploys Artillery, Troops To Kurdish Border Areas Amid Renewed War Fears
Thursday, Oct 22, 2026 – 02:00 PM
Kurdish and Middle East regional news sources are saying Iran’s military is building up artillery and personnel in the country’s northwest Kurdish regions bordering Iraq amid an intensifying crackdown on Kurdish opposition groups, and as Israel and the US threaten new attacks.
In particular, the Kurdistan Free Life Party (PJAK) is being targeted, amid reports of recent clashes with security forces in the Shaho Mountains and other areas along the border with Iraqi Kurdistan.
The Kurdish population of Iran is a very sizeable minority of the country, commonly estimated at 10-15 million people primarily living in the northwestern and western areas of the country. Millions of Kurds also live on the Iraqi side of the border
There’s been an intensified target on Kurdish dissident groups given that in the opening months of Trump’s Operation Epic Fury, US and Israeli officials openly talked about arming Kurdish groups along the Iran-Iraq border area.
Some reports said this external covert weaponization and funding campaign in order to put pressure on Tehran was already in full swing, but a slew of Kurdish political leaders in Iraq vehemently denied the reports.
Rudaw news reports from Irbil, “Iran has deployed artillery and heavy weaponry to Kurdish areas in the west of the country amid growing fears of a wider conflict with Israel and the United States, as the Islamic Revolutionary Guard Corps (IRGC) intensifies operations against armed opposition groups along the country’s western and southeastern frontiers.”
According to more from the Kurdish media report:
The Kurdistan Human Rights Network (KHRN) reported late Wednesday that IRGC forces and military convoys carrying heavy and semi-heavy weapons had been deployed from other provinces to several cities in Iran’s Kurdish region, including Sanandaj, Kamyaran, Sarvabad, Marivan and Baneh.
An informed source in Kamyaran told the rights network that “hundreds of IRGC special forces, believed to be members of the entity’s Saberin Unit, have been dispatched over the past few weeks in military convoys to areas surrounding villages on the slopes of Mount Shaho in Kamyaran County.“
There have been prior reports of sporadic drone activity and artillery fire in the areas of Shaho and Marivan.
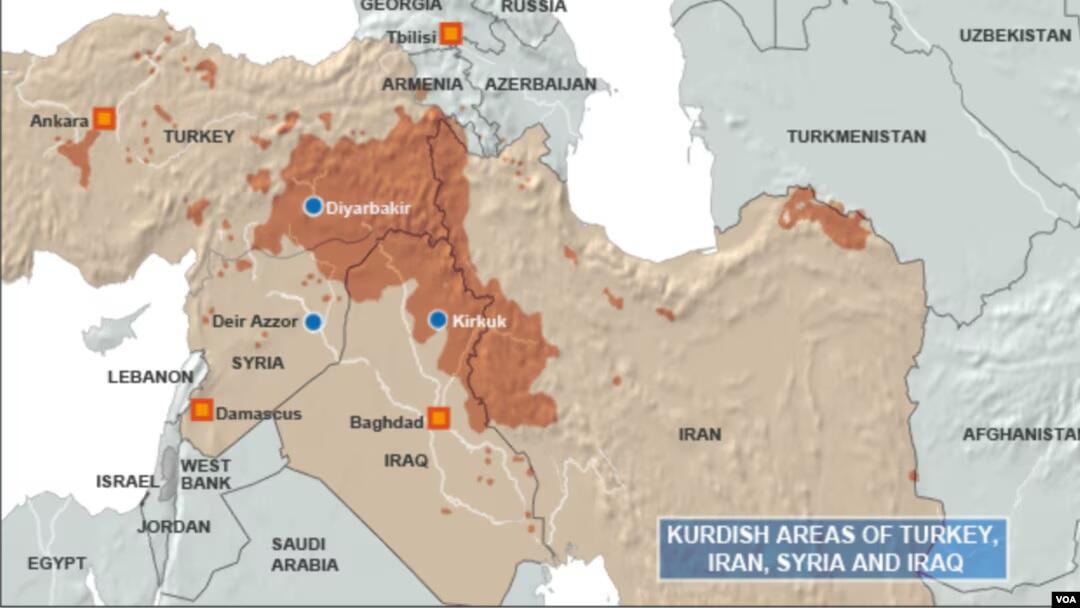
These flare-ups have long predated the current US-Iran war, but the heightened state of alert and growing temperature of the region could bring an intensification to Tehran’s anti-Kurdish opposition crackdown.
END
RUSSIA VS UKRAINE
UKRAINE//CENTRAL BANK
INTERESTING!!!
Ukraine’s Anti-Graft Cops Raid The Central Bank… So Where’s The Gold?
Wednesday, Oct 21, 2026 – 11:07 PM
Ukraine’s wartime corruption saga, which so far has swept through the state nuclear monopoly, the president’s former chief of staff and the prosecutor general’s office, has now reached the one institution that was supposed to be above it all: the central bank.
On Wednesday morning, detectives from the National Anti-Corruption Bureau (NABU), working with the Specialized Anti-Corruption Prosecutor’s Office (SAPO), searched the National Bank of Ukraine (NBU) headquarters in Kyiv and the home of what the bureau coyly called “one of its employees.” According to a law enforcement source cited by the Kyiv Independent, the premises searched belonged to Governor Andriy Pyshnyi himself, and MP Danylo Hetmantsev said as much publicly: the “employee” was the governor.
The NBU confirmed the searches and said it was operating as usual. By evening, Pyshnyi was on Facebook insisting that, per the court order, the criminal case concerns neither the central bank’s activities nor his duties as governor, and that the searches turned up no evidence of wrongdoing by him or any NBU staffer. The central bank also denied rumors that he had resigned. Which, as anyone who has followed Ukrainian politics knows, is usually what happens right before someone resigns, or is resigned.
Follow The Sense Bank
So what are the detectives actually looking for? NABU hasn’t said, but lawmaker Yaroslav Zhelezniak, who first publicized the raid, says it is tied to two cases: the Karpatnaftokhim petrochemical complex in western Ukraine, and the running of state-owned Sense Bank by outside individuals. Zhelezniak also called on Pyshnyi to step down.
Sense Bank is the thread worth pulling. The lender, formerly Alfa-Bank Ukraine and part of Mikhail Fridman’s empire, was nationalized after Russia invaded. It has since become a recurring character in the Energoatom kickback probe, the largest corruption case of Zelensky’s tenure. Prosecutors say a Hr 150 million ($3.4 million) bail payment for former Energy and Justice Minister Herman Halushchenko was routed through Sense Bank with allegedly laundered money, and in August they charged Zelensky’s former deputy chief of staff Iryna Mudra, Sense Bank CEO Oleksiy Stupak and others over the scheme. The NBU, as supervisor, has been criticized for not stopping it.
The direct link to Pyshnyi: Sense Bank’s former supervisory board chairman told a parliamentary inquiry that Vasyl Veselyi, a figure in the leaked NABU “Mindich tapes,” was appointed to the bank on Pyshnyi’s recommendation. Pyshnyi denies making any such recommendation. In those same tapes, Veselyi and businessman Oleksandr Tsukerman reportedly discussed influencing board appointments at the bank and talking to Zelensky’s then-chief of staff Andriy Yermak about it.
That last name matters, because Pyshnyi got the job in October 2022 as a Yermak ally, after his predecessor Kyrylo Shevchenko abruptly resigned and then said NABU had accused him in a Hr 206 million embezzlement case at a state lender. Pravda reported in August that Zelensky was already unhappy with Pyshnyi and that his dismissal had been discussed. So two of the last two NBU governors have now had anti-graft detectives at the door. Not a great hit rate for the institution that also happens to guard the nation’s gold reserves.
And as a bizarre coda, on the very same day Hungarian authorities detained György Matolcsy, Viktor Orbán’s longtime central bank governor, whose son is the subject of a separate probe into corruption at the Hungarian central bank. Central bankers across the region probably had a quiet dinner tonight.
Speaking Of Reserves… Where Is The Gold?
Which brings us to the question nobody in Kyiv was asked today. To be clear upfront: nothing reported so far ties the NBU probe to Ukraine’s reserves, and Pyshnyi says the case has nothing to do with the bank’s operations. What follows is speculation, labeled as such. But if the central bank’s supervisory function was compromised by people with access to the president’s office, it seems fair to ask what else was sitting within reach.
On paper, the answer is reassuring. Ukraine’s international reserves hit a record $57.7 billion as of Feb. 1 (unclear how much of that is US “donations”) and monetary gold made up 8.5% of them, up from 5.7% a year earlier, thanks largely to gold’s price surge rather than any buying spree. The World Gold Council puts Ukraine’s holdings at 27.37 tonnes, unchanged through the second quarter, worth roughly $4.9 billion as of January per CEIC data.
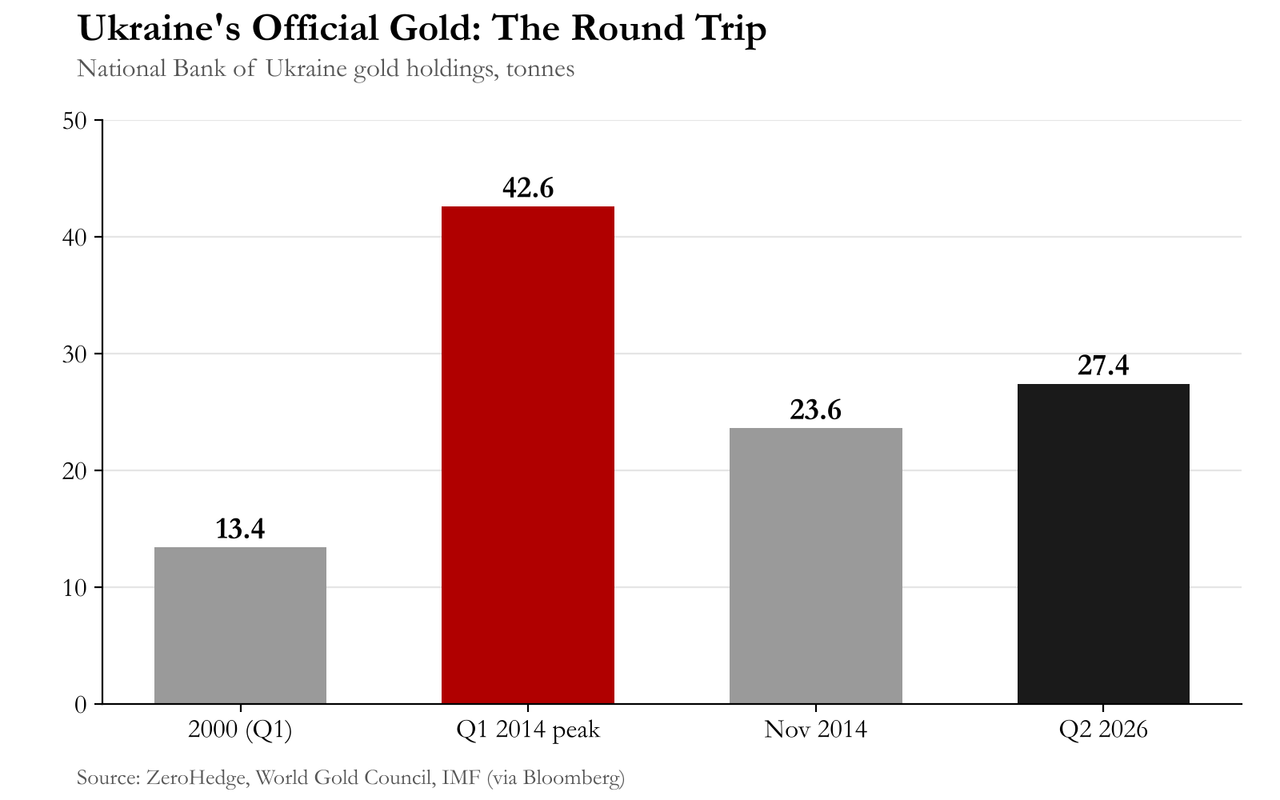
Holdings peaked at 42.6 tonnes in early 2014, fell to a nine-year low within months, and have only partly recovered since.
Long-time readers will recall that Ukraine’s gold has a habit of wandering off at moments of political upheaval. On March 10, 2014, days after Yanukovych fled, we flagged an entirely unsubstantiated report from pro-Russian outlet Iskra that the reserves had been loaded onto an unmarked plane at Boryspil and flown to the US, and asked whether the price of Ukraine’s “liberation” was the handover of its gold to the Fed.
The NBU denied it. Then in November 2014, then-Ukraine Central Bank chief Valeria Gontareva casually admitted on TV that gold was down to about $1 billion of reserves, which, on our math at the time, implied far less than that, and we wrote that Ukraine admits its gold is gone (Gontareva currently now faces Up to 12 Years in Prison and Confiscation of Property in Case Involving Collaboration with Russia).
Here is a transcript of the clip above:
- 0:00 The NBU firmed the hryvnia by only 2 kopecks, to 15.75 per dollar. On the interbank market the dollar sold at 16.05 and the euro at about 20.
- 0:14 The devaluation sent gold up 5% in a day. A gram of top-purity gold now costs 665 hryvnias, an all-time high, and the price has nearly doubled since January.
- 0:38 Gold is disappearing from the NBU’s vaults and is only a tiny share of the reserves. Gontareva said so herself on Channel 5 (5 Kanal).
- 0:49 Gontareva says “Actually, practically, if you want to know, physically there isn’t any. There’s a small amount of gold bars, but it’s literally, probably, up to 1%.”.
- 1:00 She didn’t explain how it happened. Official NBU data show almost $1B of gold at the end of October, about 8% of reserves, or eight times what she says.
- 1:20 Even by the official figures, holdings fell by more than a third in October alone. Gold prices are falling, so the NBU is selling into the drop and losing money.
- 1:38 The gold was built up under former governor Serhiy Arbuzov, who decided in early 2011 to raise gold’s share of reserves.
- 1:57 Arbuzov, in an archive clip, says: “Roughly 21 tonnes of gold. That’s several billion dollars… these are reserves that aren’t subject to the changes paper money goes through, so the value will only grow.”
- 2:08 The bet made several hundred million dollars by late 2012, and the gold sat in a secure vault that journalists toured two years earlier.
- 2:35 How the gold is now vanishing from the vaults is unclear.
A week later the central bank admitted the outflow and called it an “optimization of reserve structure,” which is probably the most central-banker phrase ever coined for “it’s gone.”
IMF data later showed holdings dropping to 23.6 tonnes in November 2014, a nine-year low, from over 42 tonnes at the start of the year. The official explanation was sales to prop up reserves, and by December lawmakers were turning on their own central bankers over it. Weeks later came the cherry on top: the NBU had been conned into buying painted lead bricks as gold, about $300,000 worth, allegedly with help from someone on the inside.
So where is the gold now? Probably in one of three places, and here’s where the speculation starts:
1. Where they say it is. The boring and most likely answer: the bulk sits in NBU vaults or, more plausibly given a war with missiles landing on Kyiv, in custody abroad. Wartime central banks routinely park bullion at the Bank of England, the New York Fed or the BIS, and the NBU has never published a bar list or a vault-by-vault breakdown. That opacity was a feature during the war. It looks a bit different on the day detectives are walking out of the governor’s office with (heavy) boxes.
2. On the road. Ukraine’s physical gold and cash do move, and we know this because one shipment got hijacked. In March, Hungary’s counterterrorism unit stopped two Oschadbank armored vans near Budapest carrying $40 million, €35 million and nine kilograms of gold from Vienna to Kyiv, with Orbán accusing Kyiv of bankrolling the Hungarian opposition. Hungary’s own tax authority later traced it to a documented Raiffeisen deal and closed the money-laundering case, and it is now Orbán, not Ukraine, facing a potential criminal case over the seizure. Still, it was a rare look at the logistics of state-owned precious metal moving across Europe in vans, and a reminder that gold, unlike a SWIFT transfer, actually has to be driven somewhere.
3. Pledged, swapped or lent. This is the one worth watching. Central banks under funding stress have a long history of quietly using gold as collateral, via swaps or leasing, while still reporting it as reserves. Nothing suggests the NBU has done this (or that it hasn’t). But if the institution’s governance was porous enough for outsiders to steer board seats at a state bank, independent confirmation that 27 tonnes are allocated, unencumbered and physically where they’re supposed to be would seem like cheap insurance. Maybe the IMF, which has a seat at every Ukrainian table these days, could ask.
A Run On Trust, Not On Gold
For now, the more immediate risk is institutional rather than metallic. The NBU’s independence is one of the few things Western lenders have consistently praised in Kyiv, and the IMF program and the EU’s Ukraine Facility both lean on it. A governor ousted under a corruption cloud, with the president’s office reportedly already wanting him gone, would hand critics of continued aid exactly the narrative they’ve been building since the Energoatom tapes leaked.
And if it turns out the case really does have nothing to do with the central bank, well, NABU just raided the head of the monetary authority of a country at war for a case unrelated to his job. Either way, someone in Kyiv is about to have a very uncomfortable meeting with the IMF mission.
END
6/.GLOBAL ISSUES, COVID ISSUES, VACCINE INJURIES/HEALTH ISSUES
GLOBAL ISSUES
COVID VACCINE INJURY REPORTS; DR MARK CRISPIN MILLER
RABOBANK/MICHAEL EVERY/OR OR PICTON/GIFFIN OR RABOBANK EXECUTIVE/COMMENTARY ON WORLDLY AFFAIRS
7. OIL AND NATURAL GAS/ENERGY COMMENTARIES
IT NOW COSTS OVER 20 DOLLARS PER BARREL FOR FREIGHT ON OIL:
AI:
“More Oil Is Leaving The Gulf Than Before The War”: And Here Comes The Shocking Freight Bill
More oil is currently leaving the Persian Gulf/Middle East than just before the U.S.-Israeli war with Iran began in late February 2026, but the cost of moving it has surged dramatically due to ongoing Iranian attacks, longer/riskier routes, and insurance premiums.
wsj.com
According to ship-tracking data from Kpler (cited by the Wall Street Journal, Bloomberg, and others), Middle East oil flows (crude, condensate, and related shipments via the Strait of Hormuz plus alternative routes) averaged more than 24 million barrels per day in the week through October 18, 2026. This edged above the pre-war baseline of about 23.3 million b/d (or roughly 24.4 million in some weekly comparisons). Bloomberg’s Julian Lee noted a Kpler figure of 24.6 million b/d for crude and condensate in that week—a high for the conflict period.
bloomberg.com
How flows recovered despite the war
- Strait of Hormuz workarounds: An improvised system of short “shuttle” runs has developed. Tankers (often older vessels, some previously used for sanctioned Russian/Venezuelan crude) load inside the Gulf, transit Hormuz (sometimes with AIS tracking off and under U.S. military air/naval protection along an Omani corridor), then transfer cargo ship-to-ship in the Gulf of Oman to larger vessels bound for Asia or elsewhere. Preliminary data put Hormuz-related flows (including offshore transfers) at around 14 million b/d, or ~82% of pre-war levels. wsj.com
- Bypass pipelines: Saudi Arabia and the UAE have sharply increased use of pipelines that avoid Hormuz. In September, ~40% of non-Iranian Gulf crude bypassed the strait (up from ~17% pre-war).
- Iran’s own exports: These remain near zero under a U.S. maritime blockade (Iran previously exported close to 2 million b/d). Iran has intensified attacks—roughly 30 reported on ships in October alone (about 20% of the war’s total)—using drones, missiles, and small-boat tactics. Attacks continue, but deterrence has weakened as risk appetite and profits rose. wsj.com
Flows are lumpy (convoys on some days, quieter periods on others), and monthly averages for October remain below the pre-war peak in some trackers. Refined products (especially diesel) lag further behind crude recovery. Oil prices stay elevated (Brent around $108/bbl in recent days), with thin inventories leaving little buffer.
wsj.com
The “shocking freight bill”Getting the oil out is extremely expensive, shifting the bottleneck from physical shortage (earlier in the war) to transport costs:
- Freight for a VLCC (very large crude carrier) carrying Gulf crude to China recently hit near-record levels of about $37 per barrel (Kpler).
- War-risk insurance has climbed to as much as 10% of a vessel’s value (from under 3% pre-war).
- Shuttle runs can cost up to $40 million for a multiday trip. Crews are offered large hazard bonuses (up to $25,000 for a round trip, or 2–3× normal monthly pay).
- Producers absorb some costs via discounts to keep buyers, while landed prices in Asia have been pushed toward $140/bbl in extreme cases. High rates have spilled over to other routes (e.g., U.S. Gulf to Asia). wsj.com
Traders note that the higher margins (e.g., ~$20/bbl extra on some Iraqi oil) can justify the risk for shipowners—three such voyages might repay a secondhand tanker’s cost—but many question long-term sustainability if attacks escalate further, especially ahead of U.S. midterms. JPMorgan’s Natasha Kaneva summarized the shift: “In April, the problem was a shortage of crude. In October, it is the cost of moving it.”
wsj.com
This draws primarily from recent Wall Street Journal and Bloomberg reporting based on Kpler and other tracker data, plus related coverage of freight markets. The situation remains volatile.
END
8. EMERGING MARKETS//AUSTRALIA NEW ZEALAND ISSUES
CANADA
U.S./GOLD AND SILVER PRICING/ASIAN CLOSING MARKETS AND EUROPEAN BOURSE OPENING AND CLOSING/ INTEREST RATE SETTINGS THURSDAY MORNING 6;30AM//OPENING AND CLOSING\
OPENING LEVELS OF CURRENCIES// AND CLOSING ASIAN STOCK MARKET AND OPENING EUROPEAN STOCKS:6 AM EST
EURO VS USA DOLLAR: 1.1241 UP 0.0006
USA/ YEN 157.09 DOWN 1.043 NOW TARGETS INTEREST RATE AT 1.75% AS IT WILL BUY UNLIMITED BONDS TO GETS TO THAT LEVEL…//YEN STILL FALLS//END OF YEN CARRY TRADE BEGINS AGAIN DEC 2024/Bank of Japan raises rates by .25% TO 1.75 ..TAKAICHI NEW PM AS YIELDS RISE//JAPAN DEEPLY IN TROUBLE WITH RISING RATES AND A FALLING YEN!! BANK OF JAPAN WILL NO LONGER DO QE. URGES PENSION AND INSUANCE FUNDS TO BUY JAPANESE BONDS//
YEN CARRY TRADERS MURDERED
GBP/USA1.3413 UP 0.0013 OR 13 BASIS PTS
USA/CAN DOLLAR: 1.4019 DOWN 0.0023 //CDN DOLLAR UP 23 BASIS PTS//
Last night Shanghai COMPOSITE CLOSED DOWN 55.00 PTS OR 1.48%
Hang Seng CLOSED DOWN 731.37 PTS OR 3.09%
AUSTRALIA CLOSED DOWN 0.49%
// EUROPEAN BOURSE: ALL RED
Trading from Europe and ASIA
I) EUROPEAN BOURSES: ALL RED
2/ CHINESE BOURSES / :Hang SENG CLOSED DOWN 731.37 PTS OR 3.09%
/SHANGHAI CLOSED DOWN 55.00 PTS OR 1.48%
AUSTRALIA BOURSE CLOSED DOWN 0.49%
(Nikkei (Japan) CLOSED DOWN 1551.24 PTS OR 2.40%
INDIA’S SENSEX IN THE RED
Gold very early morning trading: $4090.50
silver:$56.02
USA DOLLAR VS TRY (TURKISH LIRA): 49.63 UP 3 BASIS PTS AND NOW WE SEE THEIR STUPIDITY OF SELLING SOME OF THEIR GOLD AND ALL OF THEIR USA DOLLAR RESERVES. THE COUNTRY IS IN BIG FINANCIAL TROUBLE
USA DOLLAR VS RUSSIAN ROUBLE: 81.27 ROUBLE// UP 0 ROUBLE AND 64 BASIS PTS.
UK 10 YR BOND YIELD: 5.3787 DOWN 1 BASIS PTS
UK 30 YR BOND YIELD: 5.777 DOWN 1 BASIS PTS
FRENCH OAT 10 YR BOND YIELD: 5.091 UP 10 BASIS PTS.
CDN 10 YR BOND YIELD: 3.865 DOWN 3 BASIS PTS
CDN 5 YR BOND YIELD; 3.595 DOWN 3 BASIS PTS
USA dollar index early THURSDAY MORNING: 101.36 DOWN 24 BASIS POINTS FROM WEDNESDAY’s CLOSE
THURSDAY MORNING NUMBERS ENDS
And now your closing THURSDAY NUMBERS 10.00 AM
Portuguese 10 year bond yield: 3.926% DOWN 1 in basis point(s) yield
JAPANESE BOND 10 yr YIELD: +2.867% DOWN 2 FULL POINTS BASIS POINTS /JAPAN losing control of its yield curve/
JAPAN 30 YR: 3.875 DOWN 3 BASIS PTS//
SPANISH 10 YR BOND YIELD: 4.064 DOWN 1 in basis points yield
ITALY 10 YR BOND: 4.612 UP 4 points in basis points yield ./
GERMAN 10 YR BOND YIELD: 3.3643 DOWN 6 BASIS PTS
IMPORTANT CURRENCY CLOSES : MID DAY THURSDAY
Closing currency crosses for day /USA DOLLAR INDEX/USA 10 YR BOND YIELD/10:00 AM
Euro/USA 1.1136 DOWN 0.0038 OR 38 basis points
USA/Japan: 157.19 DOWN 0.950 OR YEN IS UP 95 BASIS PTS// HIGHLY INFLATIONARY TO JAPAN
Great Britain 10 YR RATE 5.3728 DOWN 1 BASIS POINTS //
GREAT BRITAIN 30 YR BOND; 5.7501 DOWN 4 BASIS POINTS.
FRANCE 10 YR: 5.065 UP 7 BASIS PTS
CANADIAN DOLLAR UP 12 BASIS PTS TO 1.4057
xxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxxx
The USA/Yuan CNY 6.6746 ON SHORE ..UP
THE USA/YUAN OFFSHORE// CNH UP TO 6.6748
TURKISH LIRA: 49.63 UP 3 EXTREMELY DANGEROUS LEVEL/DEATH WATCH/HYPERINFLATION TO BEGIN.//
Your closing 10 yr US bond yield DOWN 12 in basis points from WEDNESDAY at 5.028% //trading well ABOVE the resistance level of 2.27-2.32%)
USA 30 yr bond yield 5.340 DOWN 10 basis points /10:00 AM
USA 2 YR BOND YIELD: 4.721 DOWN 10 BASIS PTS.
GOLD AT 10;00 AM $4057.00
SILVER AT 10;00: $55.18
Your 11:00 AM bourses for Europe and the Dow along with the USA dollar index closing and interest ratesTHURSDAY
DAY CLOSING TIME/ 12:00 AM///
London: CLOSED DOWN 27.85 PTS OR 0.26%
GERMAN DAX: CLOSED DOWN 273.29 PTS OR 1.07%
FRANCE: DOWN 110.42 OR 139 PTS
Spain IBEX CLOSED DOWN 410.00 PTS OR 2.12%
Italian MIB: CLOSED DOWN 572.69 PTS OR 1.17%
WTI Oil price 1,260.03 PTS OR 2.54% 10.00 EST/
Brent Oil: 111.77 10:00 EST
USA /RUSSIAN ROUBLE: 81.12/// ROUBLE UP 0 AND 78/ 100
CDN 10 YEAR RATE: 3.811 DOWN 5 BASIS PTS.
CDN 5 YEAR RATE: 3.543 DOWN 5 BASIS PTS
CLOSING NUMBERS: 4 PM//
Euro vs USA 1.1217 DOWN 0.0017 OR 17 BASIS POINTS//
British Pound: 1.3398 UP 0.0005 OR 5 basis pts/
BRITISH 10 YR GILT BOND YIELD: 5.3342 DOWN 4 FULL BASIS PTS//
BRITISH 30 YR BOND YIELD: 5.7323 DOWN 9 IN BASIS PTS.
FRENCH 10 YR BOND: 5.082 % UP 8 BASIS PTS
JAPAN 10 YR YIELD: 2.868 % DOWN 2 FULL BASIS PTS (DANGEROUS TO THEIR ECONOMY
JAPANESE 30 YR BOND: 3.882 DOWN 2 PTS AND STILL VERY DANGEROUS TO THEIR ECONOMY
USA dollar vs Japanese Yen: 156.82 DOWN 1.326 OR YEN UP 133 BASIS PTS//GETTING FURTHER AWAY FROM 160.00/ EXTREMELY DANGEROUS
USA dollar vs Canadian dollar: 1.4007 DOWN 0.0035 PTS// CDN DOLLAR UP 35 BASIS PTS
West Texas intermediate oil: 99.45
Brent OIL: 113.40
USA 10 yr bond yield DOWN 20 BASIS pts to 4.949
USA 30 yr bond yield: DOWN 15 PTS to 5.284%
USA 2 YR BOND 4.646 DOWN 18 PTS
CDN 10 YR RATE 3.781 DOWN 8 BASIS PTS
CDN 5 YEAR RATE: 3.503 DOWN 9 BASIS PTS
USA dollar index: 101.45 DOWN 16 BASIS POINTS
USA DOLLAR VS TURKISH LIRA: 49.62 UP 2 BASIS PTS GETTING QUITE CLOSE TO BLOWING UP/IDIOTS SOLD GOLD
USA DOLLAR VS RUSSIA//// ROUBLE: 81.90 UP 0 AND 1 /100 roubles //
GOLD $4,027.50 3:30 PM)
SILVER: 54.65 3;30 PM)
DOW JONES INDUSTRIAL AVERAGE: UP 10.76 POINTS OR 0.02%
NASDAQ 100 DOWN 863.83 PTS OR 2.90%
VOLATILITY INDEX 19.85. UP 3.17 PTS OR 19%
GLD: $ 369.00 DOWN 9.95 PTS OR 2.63%
SLV/ 49.34 PTS DOWN 2.92 OR 5.59%
TORONTO STOCK INDEX// TSX INDEX: CLOSED DOWN 351.54 PTS OR 0.97%
END
end
TRADING today ZEROHEDGE 4 PM: HEADLINE NEWS/TRADING
Zuck’d: Tech Wrecks As AI Credit Cracks Widen; Bonds Panic-Bid, Bitcoin & Bullion Battered
WRAP UP
Tech hit on AI concerns, while Middle East tensions grow – Newsquawk US Market Wrap
Thursday, Oct 22, 2026 – 03:59 PM
- SNAPSHOT: Equities down, Treasuries up, Crude up, Dollar down, Gold down.
- REAR VIEW: US and Israeli militaries have reportedly developed plans for renewed strikes on Iran after the US midterm elections; META earnings beat, yet guidance underwhelms; Trump said Iran driving up oil before midterms; Aramco facility in Saudi Arabia reportedly goes on fire; US Initial Jobless Claims little changed W/W; TSLA revenue growth disappoints; Soft NZ CPI; Kering ADR sinks after earnings.
- COMING UP: Data: Global Flash PMIs (Oct), Japanese CPI (Sep), UK Retail Sales (Sep), Canadian Retail Sales (Sep). Events: CBR Policy Announcement (Oct). Speakers: ECB’s Cipollone. Supply: Australia. Earnings: American Express, SLB, Autoliv, Safran. Credit Ratings: Moody’s on France; S&P on Germany; Scope on Italy.
More Newsquawk in 3 steps:
1. Subscribe to the free premarket movers reports.
2. Trial Newsquawk’s premium real-time live audio squawk for 7 days.
3. Check out Newsquawk’s US Midterm Election dashboard.
MARKET WRAP
US equity indices were hit on Thursday as weakness in AI-related names weighed, despite gains in the equal-weight gauge (RSP +0.7%). Earnings beats from Lam Research (LRCX -11.8%) and Meta (META -7.0%) were not well received, with the latter’s limited FY27 guidance sparking concerns over Meta’s spending, margins and funding, resulting in its 5yr CDS hitting a new all-time high. SpaceX (SPCX) fell 9.1%, reversing Wednesday’s post-earnings gains, with Tesla (TSLA -3.0%) also seeing weakness post-results.
Yields fell sharply once again, with 7yr and 10yr yields plunging below 5.0% as the haven bid remained in full force. JPY was again saw a haven bid, as the dollar juggles downside risks to growth and yields, though French fiscal concerns have left EUR/USD little changed this week. NZD underperformed following a softer-than-expected Q3 CPI reading, although a rate hike at next week’s RBNZ meeting remains the consensus.
Oil prices were supported by a geopolitical risk premium following renewed Houthi attacks on Saudi Arabia’s Aramco facility in Yanbu that resulted in a fire, though the Saudis are yet to confirm. From Iran, the IRGC Navy said four oil-transfer vessels were struck in the Gulf and three hit mines near Hormuz, warning that US efforts to encourage passage could prompt strikes on US bases.
Precious metals were dragged lower by the risk-off mood, bringing spot gold to lows of USD 4,021/oz and silver to new YTD lows of USD 54.53/oz.
FIXED INCOME
T-NOTE FUTURES (Z6) SETTLED 1 POINT AND 9+ TICKS HIGHER AT 106-13
7- and 10yr yields plunge beneath 5% amid persistent haven bid due to AI concerns. At settlement, 2-year -16.8bps at 4.640%, 3-year -17.7bps at 4.713%, 5-year -18.0bps at 4.771%, 7-year -18.2bps at 4.848%, 10-year -16.6bps at 4.953%, 20-year -14.0bps at 5.326%, 30-year -12.5bps at 5.285%.
THE DAY: Yields continued their heavy decline as AI growth concerns remained the driving factor, leaving tech stocks down over 3%. One potential factor behind the Treasury bid is the high-yield market being effectively on hold until after the midterms, with investors wanting permitting and regulatory issues “substantially resolved”, CNBC reported, citing credit desks. Meta’s Q3 earnings beat, but little detail on FY27 sparked concerns over spending, margins, and funding, ultimately resulting in Meta’s 5yr CDS hitting an all-time high.
US data was a non-event, as Initial and Continuing Claims signalled a low-hire, low-fire environment. In the US afternoon, the 5yr TIPS auction tailed by 0.7bps, notably weaker than the prior 0.5bps stop-through. This reflects the recent sharp shift in sentiment on the inflation outlook, as weaker demand from an AI drawdown is seen as more than offsetting the inflationary upside from higher oil prices, as highlighted by money markets paring year-end Fed rate hike bets, no longer fully pricing a 25bps hike (now 20.3bps vs. 25.3bps yesterday).
In Europe, French turmoil persisted, with French yields rising despite European government bond yields being largely lower on the day (BTP yields also higher), leaving the OAT:Bund 10yr spread exceeding 175bps.
Supply
- US sold USD 26bln of 5yr TIPS; tailed 0.7bps.
- US sold 4-wk bills at a high-rate of 3.945%, B/C 2.82x; sold 8-wk bills at a high-rate of 4.015%, B/C 2.57x.
- US to sell USD 69bln in 2-year notes, USD 70bln in 5-year notes, USD 44bln in 7-year notes and USD 28bln in 2-year floating-rate notes
- US to sell USD 95bln of 13-wk bills and USD 82bln of 26-wk bills on October 26th; USD 95bln of 6-wk bills on October 27th; all to settle on October 29th.
STIRs/OPERATIONS
- Fed Hike Pricing via CME FedWatch: Oct 1.8bps (prev. 3.7bps), Dec 20.3bps (prev. 25.3bps)
- EFFR at 3.88% (prev. 3.88%), volumes at USD 110bln (prev. USD 110bln) on October 21st
- SOFR at 3.88% (prev. 3.88%), volumes at USD 2.942tln (prev. USD 2.925tln) on October 21st
- NY Fed RRP op demand at USD 0.351bln (prev. USD 0.237bln) across 2 counterparties (prev. 13) on October 22nd
CRUDE
WTI (Z6) SETTLED USD 2.32 HIGHER AT 99.47/BBL; BRENT (Z6) SETTLED USD 4.35 HIGHER AT 113.17/BBL
The crude complex saw notable gains on Thursday amid renewed Houthi attacks on Saudi Arabia, which fuelled escalation worries in the region. On that, the Houthis said they attacked the Defence Ministry in Riyadh and an Aramco facility in Yanbu, albeit with no Saudi confirmation. However, following these reports, Aramco reportedly instructed staff to evacuate its Dhahran HQ and work from home. Along similar lines, the US ordered non-essential diplomatic staff and their families to leave Saudi Arabia. Overall, the Middle East situation remains very fragile as the IRGC Navy stated four vessels transferring oil cargoes were struck in the Persian Gulf, while three other vessels hit sea mines yesterday west of the Strait of Hormuz, warning the US that efforts to encourage passage could result in strikes on US bases. WTI and Brent hit peaks of USD 100.17/bbl and USD 113.40/bbl, respectively, against earlier troughs of USD 97.72/bbl and USD 109.81/bbl.
EQUITIES
CLOSES: SPX -1.43% at 7,646, NDX -2.90% at 28,959, DJI +0.02% at 52,867, RUT -0.17% at 2,776
SECTORS: Communication services -3.00%, Technology -3%, Consumer discretionary -1.71%, Industrials -0.91%, Energy -0.74%, Materials +0.33%, Real estate +0.92%, Financials +1.18%, Health +1.33%, Utilities +1.98%, Consumer staples +3.11%.
EUROPEAN CLOSES: Euro Stoxx 50 -1.96% at 6,086, Dax 40 -1.10% at 25,362, FTSE 100 -0.30% at 10,721, CAC 40 -1.39% at 7,811, FTSE MIB -2.54% at 48,381, IBEX 35 -2.11% at 18,916, PSI -1.46% at 9,238, SMI -0.06% at 14,544, AEX -1.10% at 1,130
STOCK SPECIFICS:
- Meta Platforms (META): Earnings beat, raised low-end of FY capex range; FY27 outlook limited.
- Tesla (TSLA): Cautious outlook for Optimus, delayed robotaxi revenue, and high expected chipmaking costs overshadowed EPS beat.
- IBM (IBM): Earnings beat; meanwhile, gross margin declined w/ consulting rev. flat.
- Lam Research (LRCX): Guidance underwhelmed some expectations.
- Blackstone (BX): Revenue missed.
- Procter & Gamble (PG): Earnings beat.
- Comcast (CMCSA): Adj. EPS & rev. beat.
- SAP (SAP): Cloud revenue and backlog growth beat expectations.
- Alibaba (BABA), PDD Holdings (PDD), JD.com (JD): Chinese regulators reportedly summoned major e-commerce platforms over product quality.
FX
The Dollar Index was lower on Thursday amid light currency-specific newsflow, as havens JPY and CHF outperformed given the risk-off tone. As for the Greenback, the geopolitical situation, as expected, remains in focus, and concerns over an escalation continue to increase after further Houthi attacks in the region. Once again, there was no tier-1 data out of the US, while Initial Jobless Claims continued to hover around the 200k mark, reflecting the low-hire, low-fire economy. Earnings remain a key driver, and both Tesla and Meta saw losses after their reports, which weighed on wider risk and fuelled a further AI sell-off.
In G10 FX, safe-haven FX outperformed on the aforementioned risk tone, with USD/JPY trading in a 156.69-158.25 range, while the Loonie was the next best performer on surging oil prices. The Antipodeans were the laggards, with the Kiwi sitting at the bottom of the pile, weighed on by cooler-than-expected inflation metrics. However, inflation remains elevated, and money markets continue to price in a hike at next week’s RBNZ meeting. Back to the Yen, Japan’s Rengo union reportedly seeks a 6% wage increase for 2027 and maintains a minimum wage hike benchmark of 5% or more in its 2027 policy. As a reminder, Rengo is Japan’s largest national trade union confederation, and its wage talks are closely watched by the BoJ given the implications for prices and inflation.
EUR saw slight losses, as concerns in France remain rife. MUFG writes that the sell-off in French government bonds could be extended by Moody’s sovereign credit rating review, scheduled for Friday evening. Moody’s currently rates France at Aa3, one notch above its S&P and Fitch ratings.
USA DATA RELEASES
Jobless Claims Near 60-Year Lows Amid ‘Low-Hire, Low Fire, Low-Inspire’ Economy
Thursday, Oct 22, 2026 – 08:36 AM
The number of American filing for unemployment benefits for the first time dropped (again) last week to 194k – basically in line with 60 year lows…
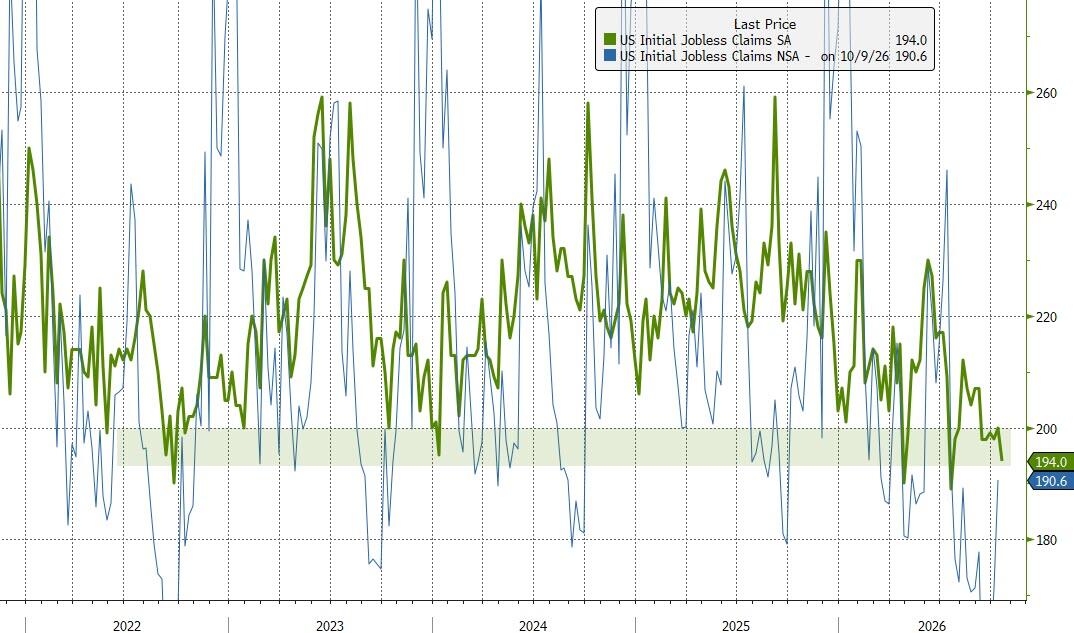
Continuing Claims ticked up but remains very close to 3 year lows…
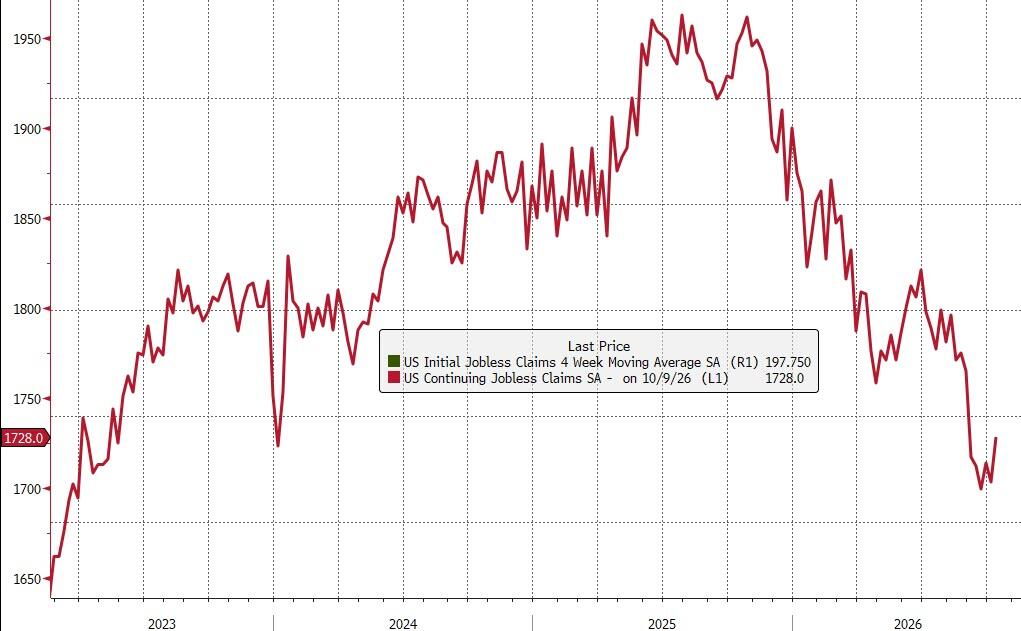
The cleanest way to reconcile it is that this is a “low-fire, low-hire” labor market, with employers hoarding labor, not shedding it.
Of course, claims remain a poor gauge of how hard it is to get hired, since new entrants, re-entrants, and gig workers mostly can’t file.
Low firing plus low hiring means insiders feel secure while anyone outside the job market is stuck.
Of course, sentiment remains disastrously low, but we’d argue it’s mostly a prices story wearing a jobs costume (impacted by political bias within the polling).
The bottom line is that claims tell you a recession isn’t imminent, payrolls tell you momentum is fading, and sentiment tells you the median household is getting squeezed by prices rather than layoffs.
The risk is that this equilibrium breaks non-linearly: low-hire markets can flip to firing quickly once margins compress, and claims would be the last of the three to flag it, not the first.
USA ECONOMIC REPORTS//QUOTH THE RAVEN:
The Economics Are Abysmal”: Harris Kupperman Warns The Crash Is Here
Harris Kupperman lays out why he believes the AI boom is approaching a reckoning, how a wave of bankruptcies could ripple through the broader economy, and where he’s positioning.
I’ve long admired Harris Kupperman, the founder of Praetorian Capital, for his ability to cut through noise and spot big-picture themes before they become consensus.
Harris just released his thoughts on markets, AI and his positions in his Q3 investor letter, which I’m happy to share with my subscribers. Harris warns that the long-awaited AI reckoning is finally here, and a broader market crash may be just beginning.

In his latest Q3 letter, Harris explores the increasingly unsustainable economics of the AI boom, the potential for a wave of bankruptcies to ripple through financial markets and the broader economy, and why he’s positioning his portfolio for a major downturn by raising cash and turning to U.S. government bonds.
He also reviews his current long positions and explains why he remains bullish on precious metals, sees significant upside in one little talked about sector as AI reshapes the labor market, and talks undervalued real estate assets and emerging markets in the future. (Photos, charts and article links added for emphasis by QTR).
“Highly Unlikely” AI Reaches Profitability As Is
I like to say that most things in finance are rather obvious; it’s the timing that’s difficult. In that vein, it’s always been rather obvious that the economics of AI are absolutely abysmal.
I think it’s highly unlikely for the industry to ever reach profitability as currently configured, as it would need a few percent of US GDP annually in revenue to break even on the capital already invested, and may need as much as ten percent of GDP to break even on the capital that many analysts expected to be invested by 2030. The numbers just cannot work—especially as tech tends to be deflationary.
How would anyone ever expect the US to be spending a few trillion dollars annually on AI, when software, which is already ubiquitous, and maturing, is currently around half a trillion of US spending?

Think back to the railroads; they became dominant modes of transport, but they periodically destabilized the US economy as they went bankrupt in repeated waves during the 1800s. Then, someone picked up the pieces, and railroad construction continued. I think we’re at a similar point in the AI journey. I definitely don’t think that AI is over, or that the buildout won’t continue. I just think a phase of rationalization is upon us.
It’s said that you go broke slowly, then all at once. I think this is a good mindset for how the AI sector will also fail. Slowly, then all at once.
The first signpost will be that the funding gets cut off, and I think we’re finally witnessing that. As funding grows more scarce and expensive, the AI sector will struggle to support unprofitable operations, and I expect to see many bankruptcies of neoclouds, followed by the large frontier AI labs. While they may have interesting assets, they also have hundreds of billions of contingent liabilities along with purchase commitments that I cannot imagine anyone wants to fund, especially if chip costs come crashing down with reduced demand.
Following bankruptcy and the rejection of these liabilities, I then assume that they get folded into the hyper-scalers.
However, these will be incredibly messy and complex bankruptcies. Just think back to how messy Enron was, with hundreds of SPVs and all sorts of future commitments over pipelines, utilities and whatnot. This will be worse, as many of the SPVs have guarantees from partners that will want to escape those guarantees.
I assume that all of this will cascade through the economy and the stock market, especially given how material semiconductors and AI have become as a percentage of US equity indexes. If you take away the performance from AI driven sectors, most stocks have done quite poorly over the past few years, and the stock market would be a good deal lower. I think stocks will revert there as AI spending slows.

AI capital expenditures are responsible for roughly three percent of US GDP currently and are predicted to grow further in 2027. While it’s harder to quantify the size of the Wealth Effect on consumer spending, it wouldn’t surprise me if it were over ten percent of US GDP.
Being conservative, I feel pretty confident in saying that the AI mania is responsible for well over ten percent of US GDP, and should anything happen to AI, even if it’s only a slow-down in spending, it would materially slow US GDP, and possibly even send it into decline, especially if the stock market collapsed at the same time.
I have gone through two US economic down-cycles during my investing career, along with a COVID panic. In all three cases, owning almost any part of the yield curve was the winning strategy—even if guys doing more exotic trades got all of the accolades. Having lost money shorting financials too early during the GFC, and then buying volatility too early during the COVID panic, I’ve decided that I’m going to focus on what’s worked in all three prior equity smashes, I’m going to buy US government paper. As of writing this to you, we already own some SOFR futures along with call spreads. I plan to add should the trade start working.

I know that the government is functionally insolvent, and that during “Project Zimbabwe” debt gets debased, but there are moments in time where fixed income can rally further than anyone can ever imagine. While bonds aren’t my favorite asset, they’re a blunt tool to express a view. As far as I’m concerned, outside of AI, the Wealth Effect driven by the AI mania, and health care for aging boomers, the rest of the economy is already effectively in a deep recession. I expect this recession to accelerate and broaden should AI spending slow, and equities sell off as AI businesses fail.
With a Congress that’s likely to swing to the left following November’s elections, I think that a fiscal response will be off the table until things get really bad. Therefore, early in this crisis, the only tool that the government will have to combat the market’s collapse is monetary intervention, and they’re likely to give it all they have. My thinking is we own bonds first, and then after the smash, we switch to debasement assets. (Though I am a bit skeptical on how bonds further out on the duration curve will perform, given current debt levels and the potential for inflation to remain elevated).

In preparation for this, I’ve taken exposure down and built cash. I’ve dramatically dialed down exposure to any businesses that are sensitive to GDP. What’s left on our sheets are businesses…that did surprisingly well coming out of the GFC, businesses tied to volatility…and businesses that do well with lower interest rates. We’ve been preparing for a deep and lasting recession for a while now.
It’s been postponed by the AI mania and the Wealth Effect that has built up around that mania. It’s been frustrating to have reduced exposure and a bearish outlook as equity markets rally. It’s been irritating to have missed out on an unsustainable mania in AI. Now, I think we’re finally at the point where this all tumbles down.
I’ve never thought that we could go fully into “Project Zimbabwe” without one last crash that gives government officials the mandate to blatantly debase. It’s hard to know exactly when this happens, but I have my roadmap, and I’m content to continue with reduced exposure. As of right now, I am far more concerned with the potential for substantial downside from here, the upside can come later.
END
LONDON TRADERS//HEDGE FUNDS
“Everyone Has Blown Up”: London Macro Traders Carried-Out As French Carry Trade Implodes (Again)
Thursday, Oct 22, 2026 – 05:45 AM
For the better part of three years, the hottest seat in London’s multi-manager world was a European rates book: lever up French OATs in repo, clip the carry, collect the seven-figure payout. This month, the French bond market sent the bill.
According to a must-read report from eFinancialCareers’ Sarah Butcher, London’s macro hedge funds are quietly emptying out their EGB desks. Funds aren’t talking about performance, but headhunters and bank traders who have been keeping score say the count of ejected European rates PMs and traders has climbed from the mid-70s a few weeks ago to close to 100 people. One senior trader at a liquidity provider summed it up in four words: “Everyone has blown up… they are all out”
In other words, the most crowded trade in European fixed income just found out what happens when the collateral is the problem.
And the bleeding hasn’t stopped. This morning Bloomberg flashed that the French bond risk gauge is nearing 160bps, a fresh 15-year high, while French 10Y yields hit 5% for the first time since July 2002.
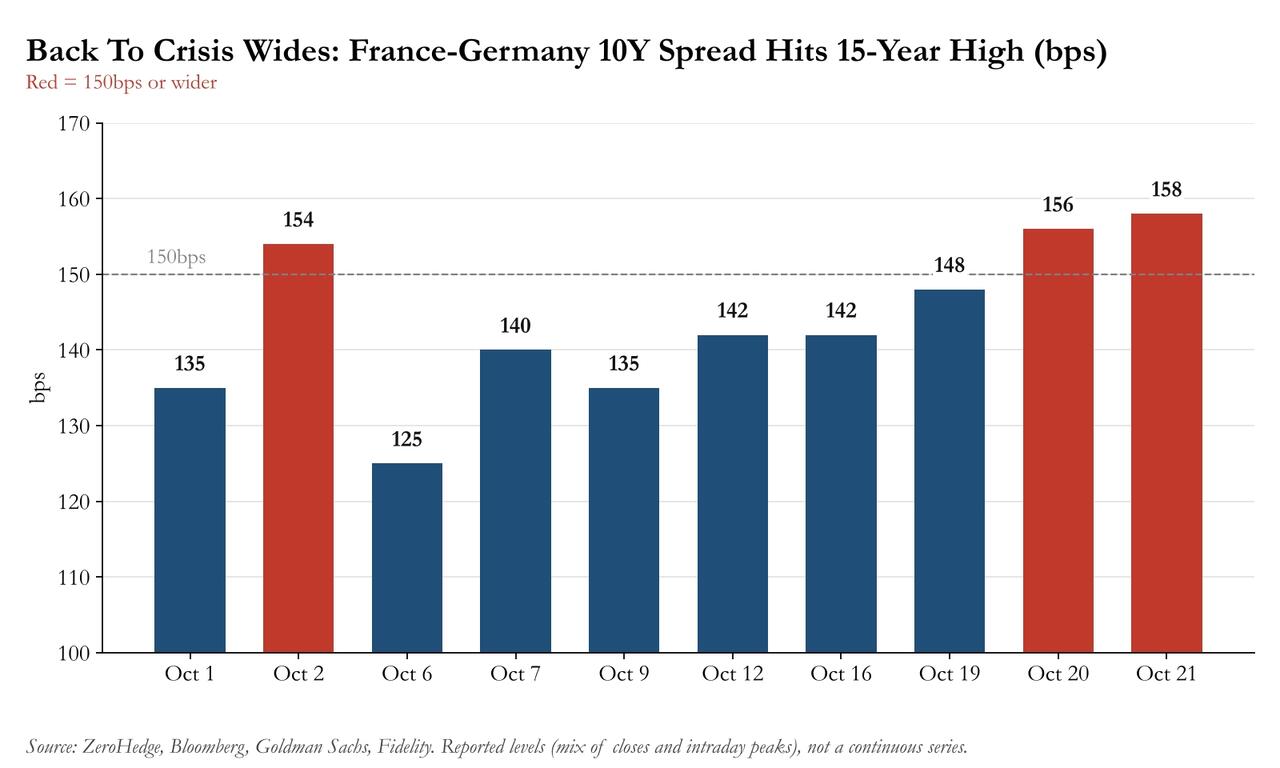
Below we walk through what blew up, why it blew up (twice), what Goldman, Morgan Stanley and the rest of the Street make of it, and why the market’s attention is already drifting to the next domino: Italy.
The Trade: Borrow Against France, Pocket The Difference
The mechanics were simple enough to fit on a Post-it. Funds bought French government bonds, financed them in the repo market using those same OATs as collateral, and pocketed the gap between the bond’s yield and the repo cost. Lever it up enough times and a few basis points of carry becomes a career. Per eFC, as French yields rose amid political chaos, OATs sold off and the whole highly leveraged structure was turned upside down.
A bank trader watching from the sidelines was less charitable:
“These people weren’t even real portfolio managers,” claims one senior trader, watching from the sidelines in a London bank.
“They were just using EGBs as a carry asset. Buying bonds, sitting on the carry and getting a percentage cut. It was fun for a while. You had a lot of PMs who were long France and long Italy, but with inflation coming in and rates high, it wasn’t going to last.”
Another PM in the sector offered a more philosophical take: “every bubble gets its moment.”
The wider version of the trade, as Bloomberg reported on Oct 2, was the OAT asset-swap: funds including Taula Capital and Balyasny had built positions to harvest the spread between French yields and interest-rate swaps. Those were lucrative right up until the budget blowup of Oct 1, when the trades flipped from winners to liabilities and everyone hit the exit at once. RBC BlueBay’s Kaspar Hense told Bloomberg what that looked like from the inside:
“Most typical hedge-fund strategies are in risk reduction mode. There have also been stop-loss levels triggered, partly on the steepener trades and now on long France trades.” (emphasis ours)
— Kaspar Hense, RBC BlueBay Asset Management, via Bloomberg
Fidelity International’s fixed income CIO Marion Le Morhedec went further, estimating that hedge fund activity could explain roughly half of the recent moves in the French-German spread, pointing to particularly heavy Eurex activity. Turns out the “liquidity providers” were also the liquidity takers.
Regular readers will recall that we called this one in real time on the very first day of the month:
…which was followed hours later by “Debt Crisis Back? European Bond Markets Crash, CDS Explode Amid France Budget Panic Contagion” (Oct 1). By the next day, the OAT-Bund spread hit 154bps, the widest since 2011, and the deleveraging was in full swing.
Same Trade, Same Crowd, Same Exit Door
The most damning detail in the eFC piece: according to the liquidity-provider trader, many of the PMs who blew up this month had already blown up in March, on the same positions. That was when the Iran war and the Hormuz shock triggered the first great European rates unwind, and when, per Bloomberg, multi-strats from Millennium to Balyasny to ExodusPoint gave back some or all of their year-to-date gains as crowded trades unwound.
Seven months apart, the same book got carried out twice. Diversification at its finest.
“They’ve blown up twice on the same trades.”
Another trader observes that a lot of funds moved into the European fixed income space in the belief that it was easy money:
“The whole European carry system is now being questioned.”
You can see both episodes in Goldman’s own long-OAT/short-Bund rolling futures basket, which the bank’s Systematic Trading Strategies desk circulated to clients: a steady grind higher for three years, a wobble in March, and then a near-vertical collapse that has wiped out roughly five years of gains as the basket fell from a February peak of ~104.3 to ~99.2.
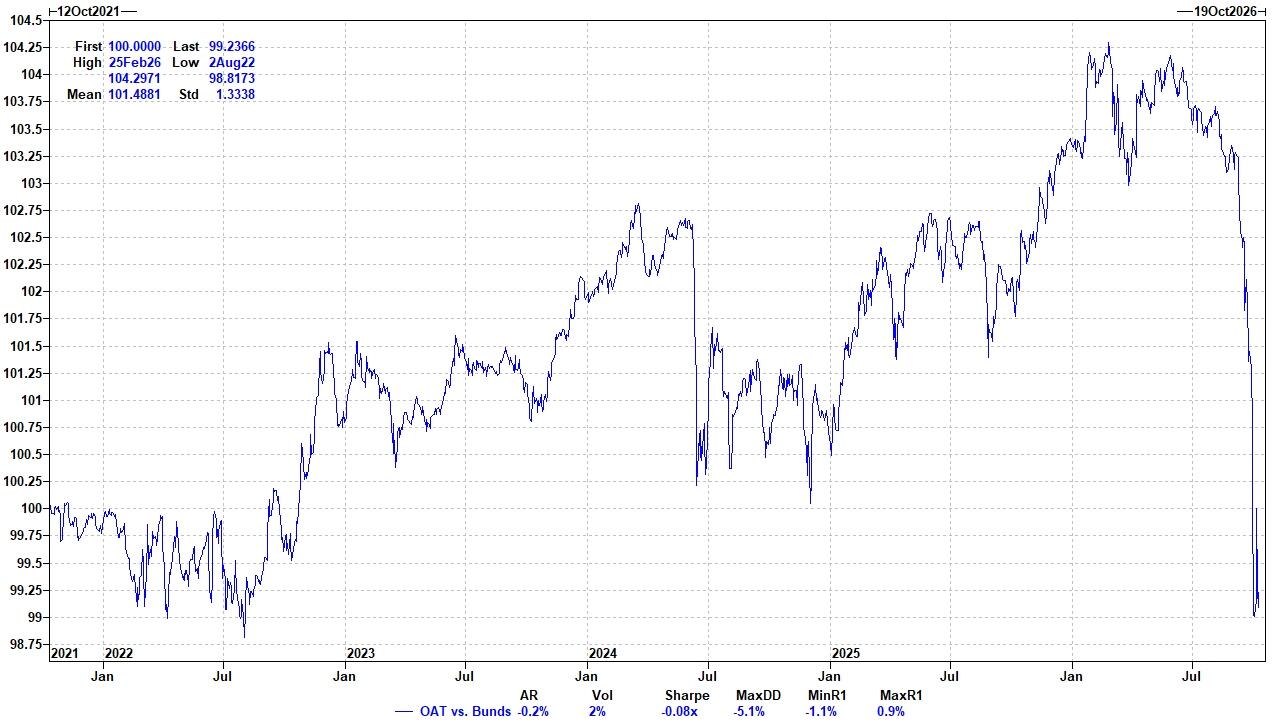
Goldman’s STS desk described the October contagion mechanism in that same note (available to pro subs here):
OATs have come roaring back into market focus over the last month. Where an unwind of popular rates positions following the latest ECB meeting (mostly steepeners), seemed to spread to wider carry trades in the rates space among a bid for volatility. A weak starting position for France with regards to debt and fiscal background and uncertainty into next year’s election as well as challenging budget process didn’t help. (emphasis ours)
— Goldman Sachs STS, Tim Huiszoon, Oct 12
Translation: the steepener crowd got stopped out first, then the losses bled into every other levered carry position on the same risk books. Not a fundamental repricing so much as a margin call with a French accent.
Allianz Trade agrees, noting in an Oct 9 report that speculative shorts, hedge-fund asset-swap unwinds and thin liquidity created a negative loop, with market depth more than 50% below normal:
“The speed reflects a positioning shock, not a pure repricing of fundamentals. Long-term investors are sitting out ahead of the elections… Fragmentation is far from 2012 or 2020 levels, but the ingredients are in place.” (emphasis ours)
— Allianz Trade, “Toasted, not burnt”, Oct 9
Note the second sentence: the real money that would normally buy the dip is sitting on its hands until the election. Which leaves… nobody.
The Plumbing Problem Nobody Wanted To Talk About
It’s not just about P&L. Hedge funds have stepped in as the marginal provider of liquidity in European sovereigns precisely as central banks, pensions and banks stepped back. Per Bank of France data cited by Reuters, French government debt accounts for roughly €100 billion of the €250 billion in euro-area sovereign bonds pledged as repo collateral. In other words, France is the euro repo market.
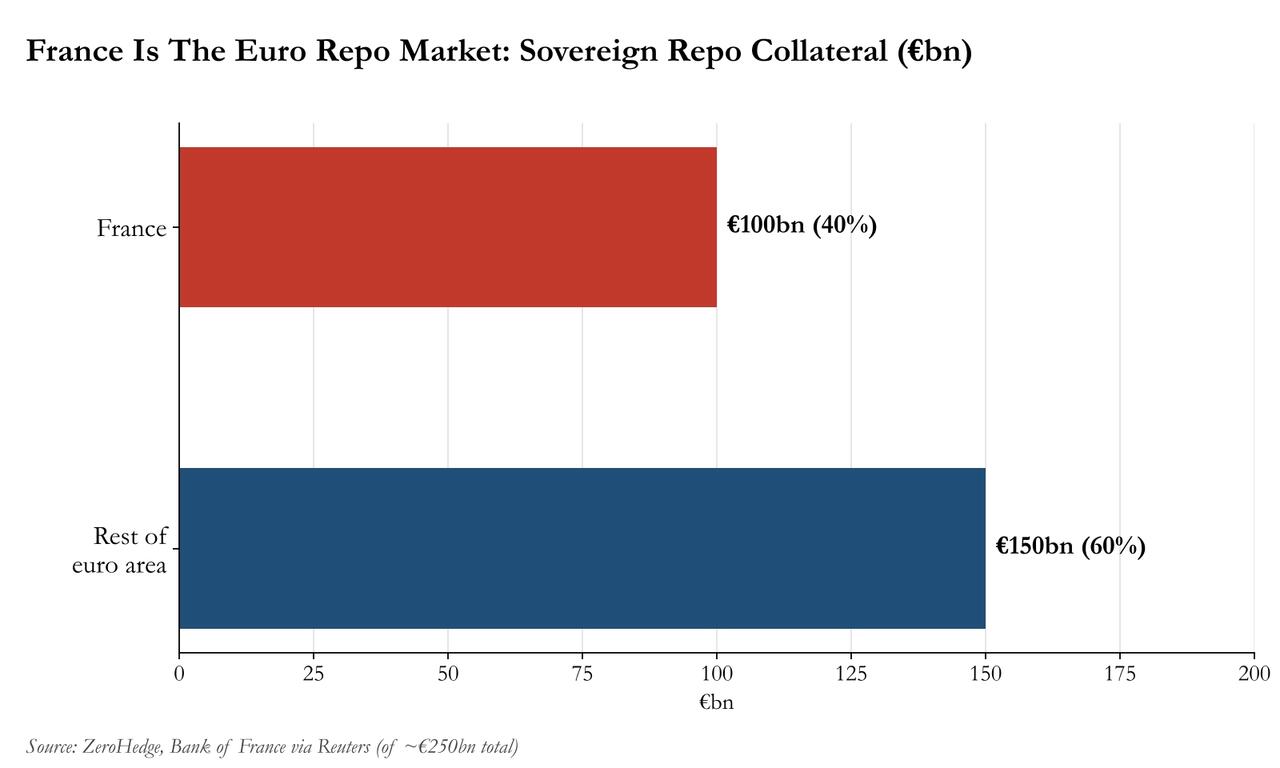
So far the repo market itself has held up, but the risk is obvious: a further ratings cut narrows the pool of institutions able (or willing) to take OATs as collateral, which raises funding costs, which forces more selling. Commerzbank flagged exactly this back in September after Fitch’s downgrade:
“…once a second agency downgrades to single-A, OAT repos may cheapen visibly, similar to BTPs, where more than half of bonds already trade above the depo rate.” (emphasis ours)
— Commerzbank, via MNI, Sep 16
With Moody’s reviewing France on Friday, that is not exactly a theoretical concern. And as we noted when the sell-side spent a day insisting the OAT rout was “just positioning,” the contagion had already jumped to the banks, with the selloff reactivating Europe’s “doom loop” (Oct 7). Goldman’s European financials desk is still hiding under the desk:
“We are staying in risk off mode on banks (topics remains Euro sovereign crisis fear + Rates + Competition + Agentic, ie peak ROTE)… Appetite for French banks is very low given how long it will take to have some clarity.” (emphasis ours)
— Goldman Sachs EU Financials specialist sales, Oct 20
“Overshot Fundamentals”… Says Goldman (Two Weeks Ago)
To be fair to Goldman, the bank has been leaning against the panic. Its strategists argued earlier this month that the OAT selloff appeared to have overshot fundamentals, amplified by positioning, though they conceded France is cheap relative to peers but lacks a catalyst. GS’s STS desk went further on Oct 12, flagging GIR’s expectation that the spread stabilizes at tighter levels and pitching a 1-year principal-protected option on OATs vs Bunds as a reversal trade with the 10Y spread at ~135bps.
The market had other plans. After weekend riots across France (nearly 2,400 arrests), the spread widened another 8bps to ~145bps on Monday, per Goldman’s Daily Monitor, which ran this as its chart of the day: the OAT-Bund spread (inverted) dragging the euro down with it.
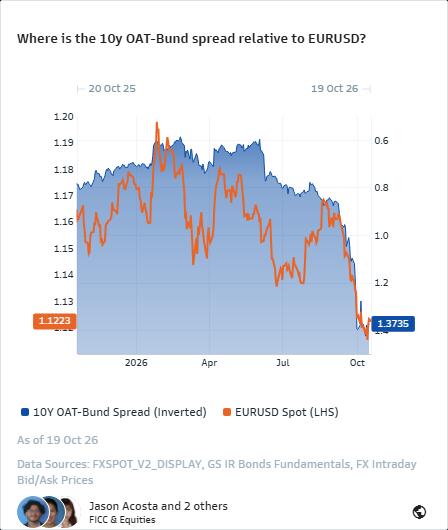
Goldman’s FX desk confirmed the hedge funds were already heading for the exits:
“EUR option volumes – which have been an key indicator for broader portfolio hedges – have also decreased and are more than 30% off the highs. Certainly, a lot of hedges have been put on already and broad de-risking across popular positions was a hallmark of last week’s activity.” (emphasis ours)
— Goldman Sachs FX desk, Oct 19
Bloomberg’s Vassilis Karamanis reads the same options market more darkly: the premium for longer-dated euro downside now exceeds short-dated, suggesting the euro’s weakness “reflects more than a positioning adjustment.” So much for “just positioning.”
By Monday’s close, French 10Y yields had posted their highest close since 2002 (Oct 20), and on Tuesday the spread hit a 156bps peak:
And this morning the milestone everyone was waiting for finally printed: per Bloomberg, French 10Y yields hit 5% for the first time since July 2002, with the OAT-Bund spread out another 5bps to 158bps as Brent traded above $110. So much for stabilizing at tighter levels.
Goldman’s own economists, meanwhile, aren’t buying the government’s numbers either. In Tuesday’s European Daily, Alexandre Stott writes:
“Recent protests over school underfunding and cost-of-living pressures have been among the largest since the pension reform strikes of 2019 and 2023 and the ‘yellow vests’ movement of 2018… we remain sceptical that the government will meet its deficit target of 5.0% of GDP next year… Our poll-based model therefore continues to see Le Pen as the clear favourite to become President next year.” (emphasis ours)
— Goldman Sachs, European Daily: France—Budget Adoption Likely Later This Year, Oct 20
Morgan Stanley’s chief global economist Seth Carpenter, whose note we published on Oct 11, is just as blunt about the arithmetic, and about the cavalry:
At wider than 150bps, the 30yr OAT-Bund spread surpassed the 130bp mark reached in the euro area debt crisis a decade ago… Debt stabilization would require a primary surplus of roughly 2% of GDP, a turnaround of about 5 percentage points. That shift would be larger than the adjustment required in Italy in the early 2010s… We think the bar for direct ECB intervention is very high, but France may not be the last test. (emphasis ours)
— Morgan Stanley, Seth Carpenter, Sunday Start
Put differently: the ECB is not coming to rescue anyone’s carry book, and certainly not before Paris finds a fiscal squeeze bigger than the one Rome needed in 2011. Good luck with that during riots. Bill Blain, for his part, awarded a “No Sh*t Sherlock” prize to anyone who spotted European yields spiking after the riots, warning in Tuesday’s Morning Porridge that the unrest could “metastasise into a potential bond crisis unless the ECB can swiftly demonstrate it is able, willing and stands ready to intervene.”
Where Do 100 Ejected Rates Traders Go?
The career fallout is where the eFC report gets really fun. Some will drift back to the banks, where one headhunter said dealers need them to manage ECB exposure and bond books. The catch, per a bank trader: these PMs were pulling in $1 million-plus, a number that at a bank you only see as a desk head. Many are also tied up in non-competes, and some are still collecting guarantees and in no rush to find work. Good news for the departed PMs; allocators may see it differently.
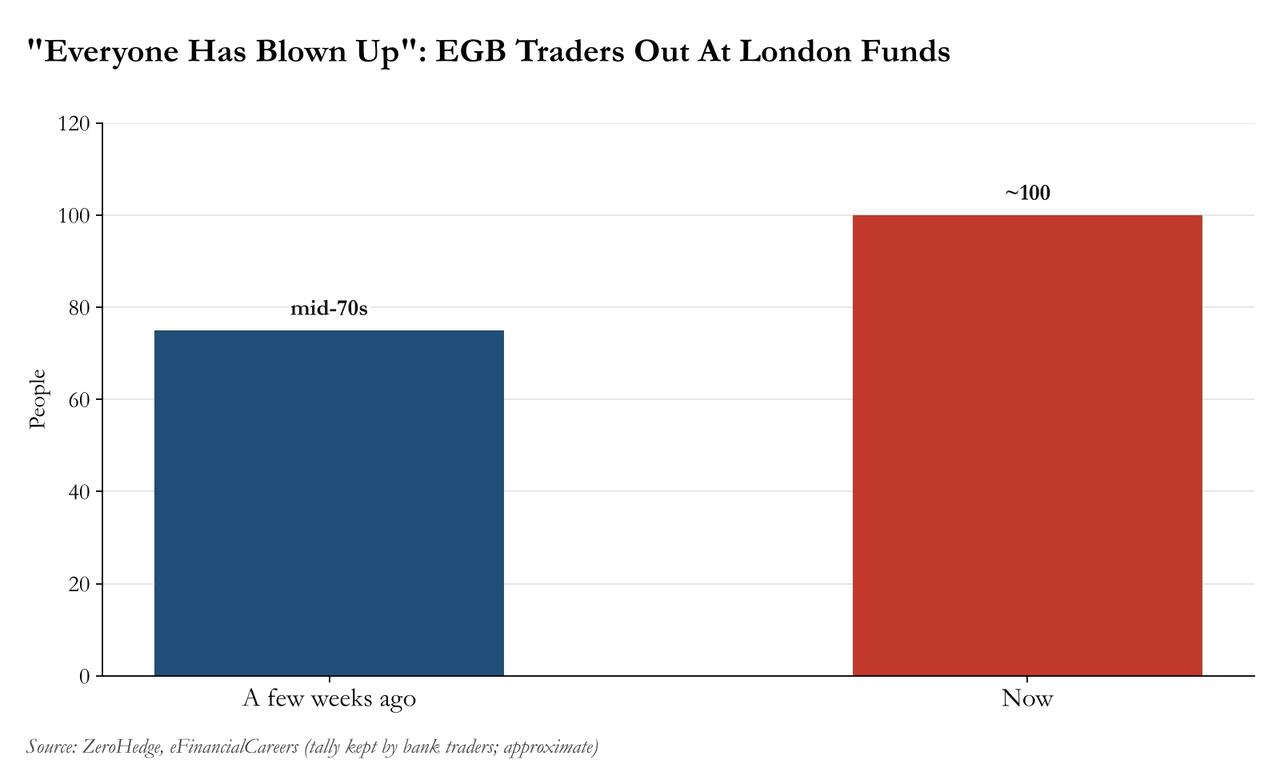
Not everyone was pushed: one source estimated roughly 10% left voluntarily, some to raise their own funds, because allocators are struggling to find people both willing and able to take risk. Which is one way of describing a market where everyone who took risk just got carried out.
More ominous is the verdict from the trading floors: one trader told eFC that funds piled into European fixed income believing it was easy money, and that the whole European carry system is now being questioned. A bank trader called it systemic. And per the headhunter, the big fear now is that Italian BTP spreads go the way of OATs, a risk Morgan Stanley also flags, noting that wider OAT spreads are already putting pressure on BTPs.
Bottom Line
Goldman’s bet is that this was a positioning flush: the levered carry crowd got shaken out, the forced selling is largely done, and spreads should drift back in. Maybe. But consider what has happened since the “overshoot” call: riots, a 5% 10Y, a spread nearing 160bps, a Moody’s review on Friday, and a presidential race where Le Pen polls at 34%-38% in the first round. The forced sellers may be gone, but the natural buyers never came back, and the marginal bid in OATs for the past three years was a levered London pod that is now on gardening leave.
And this was never just about politics. Since the Hormuz crisis began, France has underperformed every major bond market, Italy included:
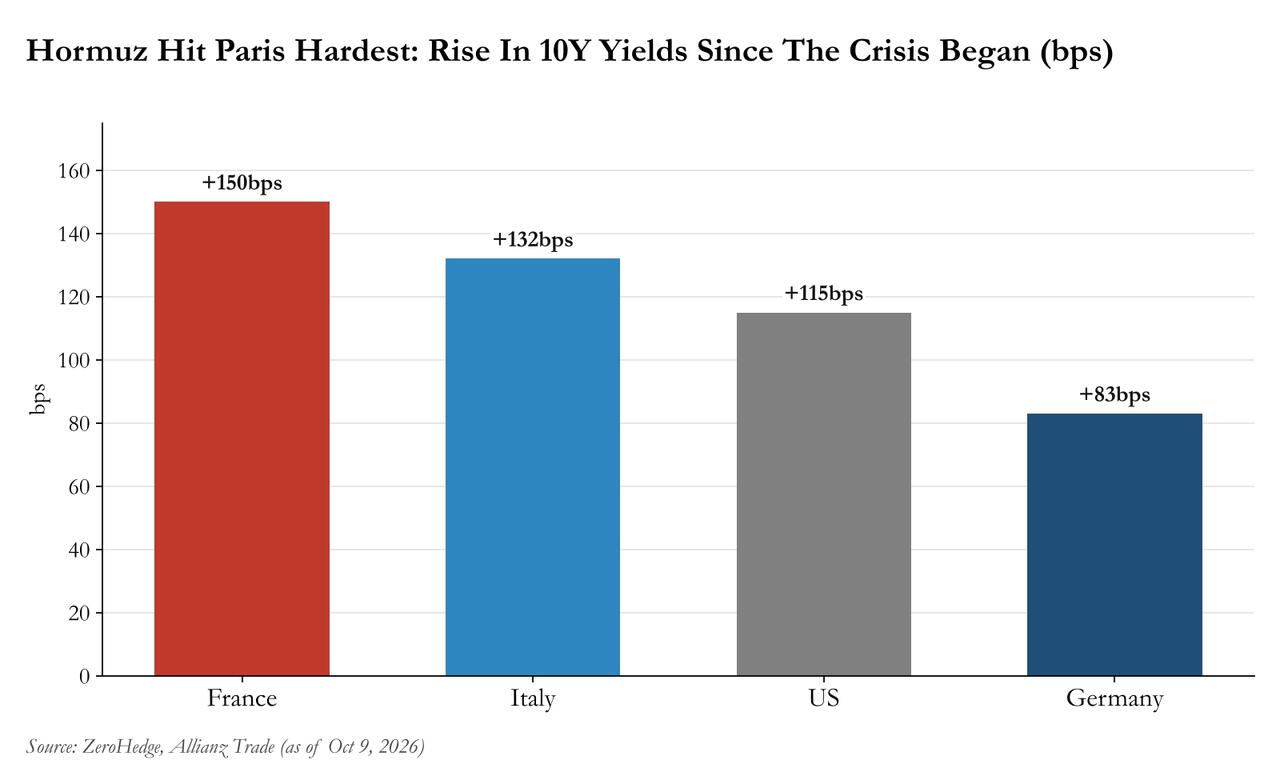
Which is why we lean toward the skeptics: this isn’t the end of a positioning unwind, it’s the beginning of a regime where France trades like the periphery, and where Italy, with the same crowd long it on the same leverage, is next in line. When the people who spent three years harvesting European carry are now warning that the asset class may never look the same, it’s probably worth listening. Expect the ECB monetization chorus to get a lot louder. We’ll check back after Friday’s Moody’s decision.
Much more in the full Goldman GS European Daily “France – Budget Adoption Likely Later This Year” note, both available to pro subs.
END
COREWEAVE…
CoreWe’ve Got Bills To Pay: Bernstein Sees $76 Billion Funding Hole At Imploding Neocloud
Thursday, Oct 22, 2026 – 12:30 PM
Goldman’s CoreWeave upgrade is three days old, and so far it has achieved precisely nothing.
On Monday, Goldman’s Gabriela Borges upgraded CoreWeave (CRWV) to Buy (in the process cutting her price target by almost a quarter) which is a creative way to turn bullish:
The stock spiked to $66 premarket and then, right after the open, gave back the entire pop, prompting us to note that Goldman was gonna need a bigger upgrade:
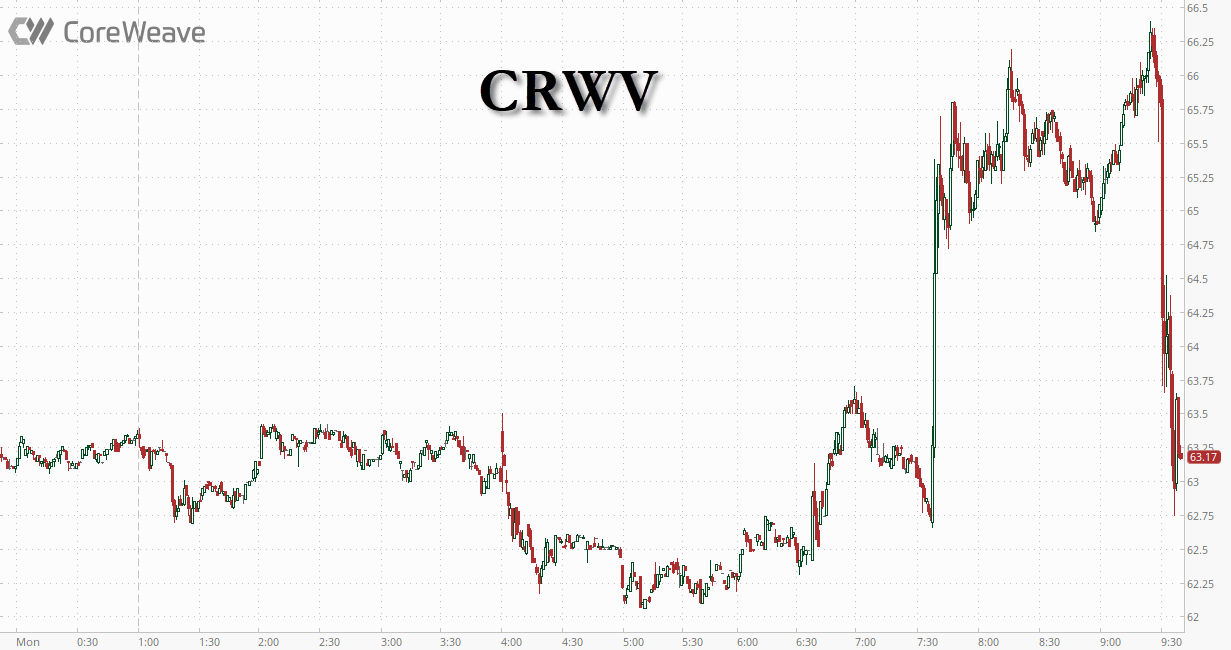
The opposite happened: a day later, HSBC tore apart Goldman’s bull case a new one with a $39 target (“the more it invests, the more the value destruction“), and this morning it’s Bernstein’s turn. CoreWeave is down another 8% this morning to $56.70, below where it traded before Goldman said “Buy”, and below the 52-week low of $57.24.
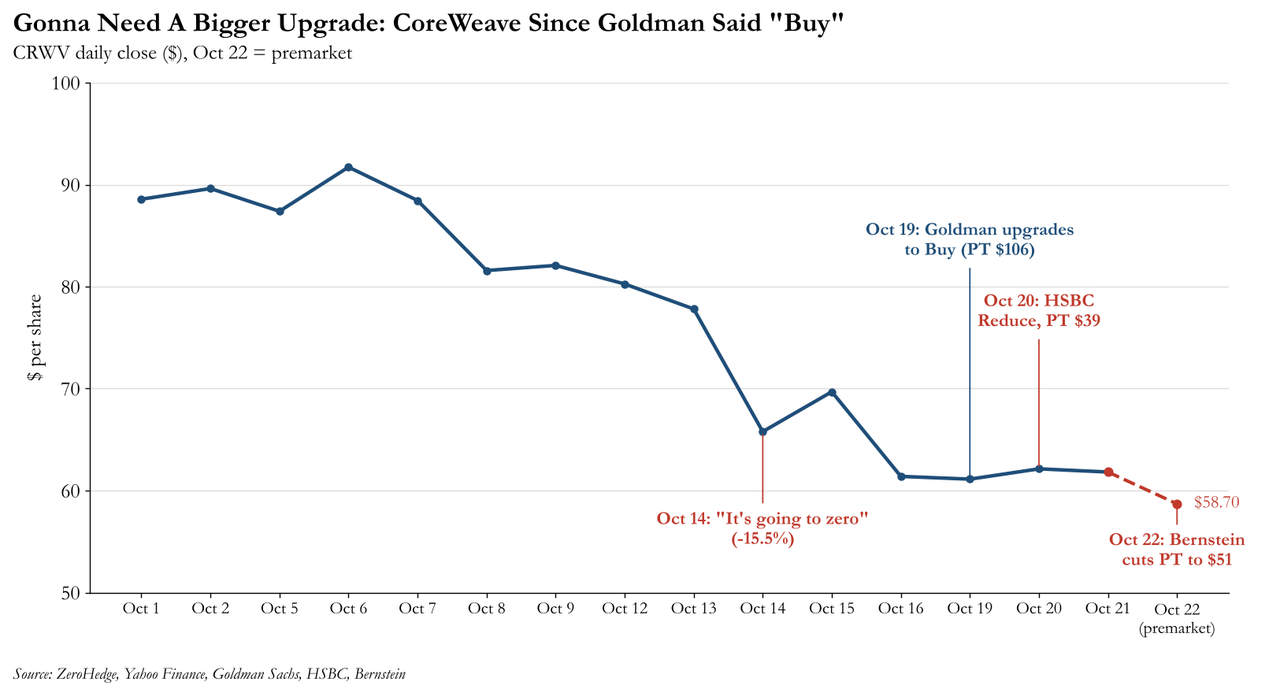
Goldman, meanwhile, doubled down. Late on Wednesday, Borges published a follow-up titled “How big is the funding gap?” (available to pro subs), because, in her words, “the primary question we have received from investors is around the magnitude and viability of future funding needs.” Her answer: about $23 billion. Bernstein’s answer, published a few hours later: $76 billion.
Somebody’s math is off by more than three times. Let’s figure out whose.
“Not Great, Not A Surprise”
Bernstein’s Madison Rezaei, who correctly had an Underperform on CoreWeave since initiating seven months ago, cut her price target to $51 from $74 in a note with what is hands down the best title of the year: “Core-We’ve got bills to pay… lowering our PT” (also available to pro subs). She also cut her target EV/EBIT multiple to 23.5x from 25.5x, “primarily reflecting concerns around its cost of capital, especially as the company moves to shorter-dated contracts.“
The note follows a week of what Rezaei describes as non-stop calls with “hedge funds, LOs, bulls, bears, credit people, REIT investors, and everybody in between.” The first question on everyone’s mind was the same one Goldman tried to answer, and Bernstein’s reply is refreshingly blunt:
“Not great, not a surprise. We estimate CRWV needs to raise $85B to fund the existing committed backlog, $9B of which is already covered by existing facilities. The unsecured credit market are still open to them at rates in the 15%+ range, given where the bonds are trading today, but we think there are a range of more reasonable options.”
In other words, $76 billion of fresh money just to deliver the compute CoreWeave has already sold, before signing a single new contract. And no, CoreWeave can’t simply stop growing its way out of the problem. Bernstein specifically addresses the investors asking whether the company could just slow spending and harvest cash:
“We distinguish stopping new contract wins from stopping investment: even without additional backlog, the company would still need to fund deployment obligations embedded in existing contracts, as well as maintenance and replacement requirements. Even a no-additional-backlog scenario would not produce immediate improvements in profitability given the funding requirements of existing contracts.”
Bernstein models roughly $46 billion of growth capex next year to deliver existing backlog plus about $6 billion of maintenance capex, for a total of $52.5 billion in 2027, actually above consensus. And even in the “no future backlog” scenario, 2027 capex is still $43.5 billion. The good news, if you want to call it that, is that Bernstein’s capex falls off a cliff after 2027 because it is well below the Street on growth in 2028 and beyond. Bulls may not see it that way.
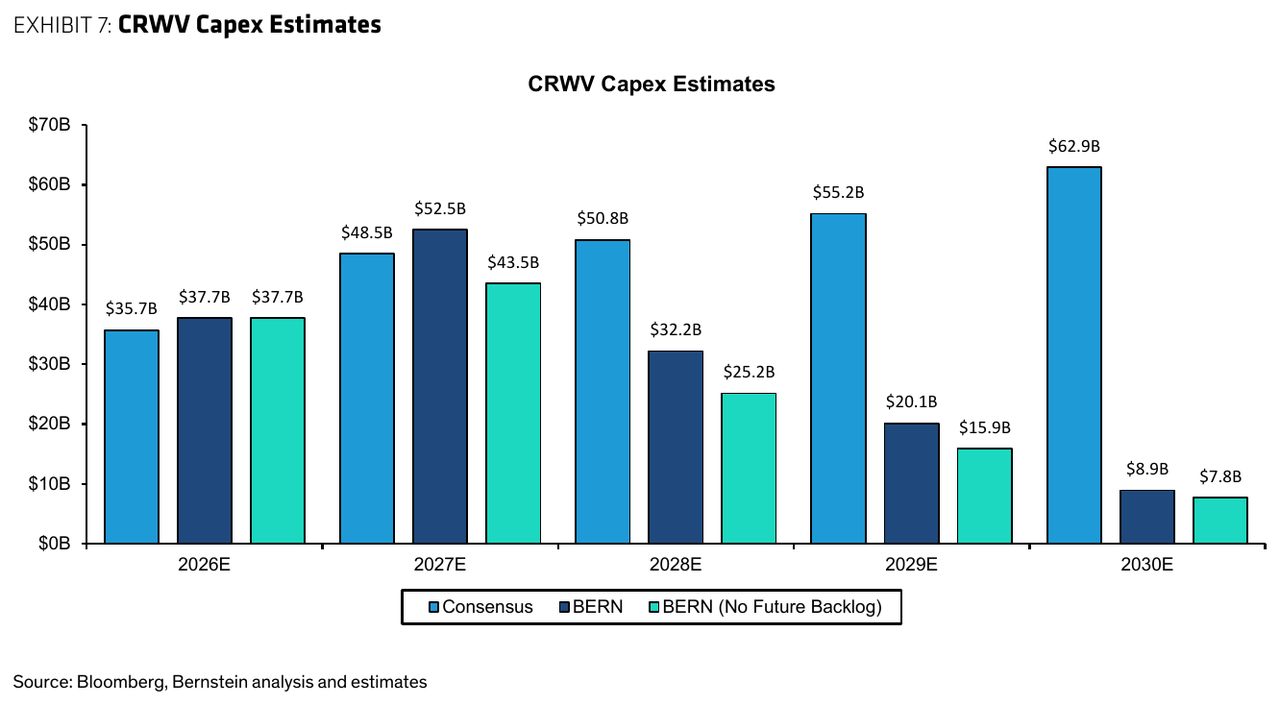
Bernstein also took an axe to earnings: its 2026 adjusted EPS loss widens to -$5.14 from -$4.56, and 2027 to -$6.81 from -$4.77, with adjusted losses persisting through at least 2029 in its model. That’s three more years of losses on top of the $76 billion.
Goldman’s $23 Billion Napkin
Now for Goldman’s version. Borges walks through three illustrative scenarios, and the headline (as per the title of her one and only exhibit) is that debt needed to serve existing $129 billion backlog “could be $20-23bn when including customer prepayments,” while ramping all 4.2GW of secured power would take about $38 billion.
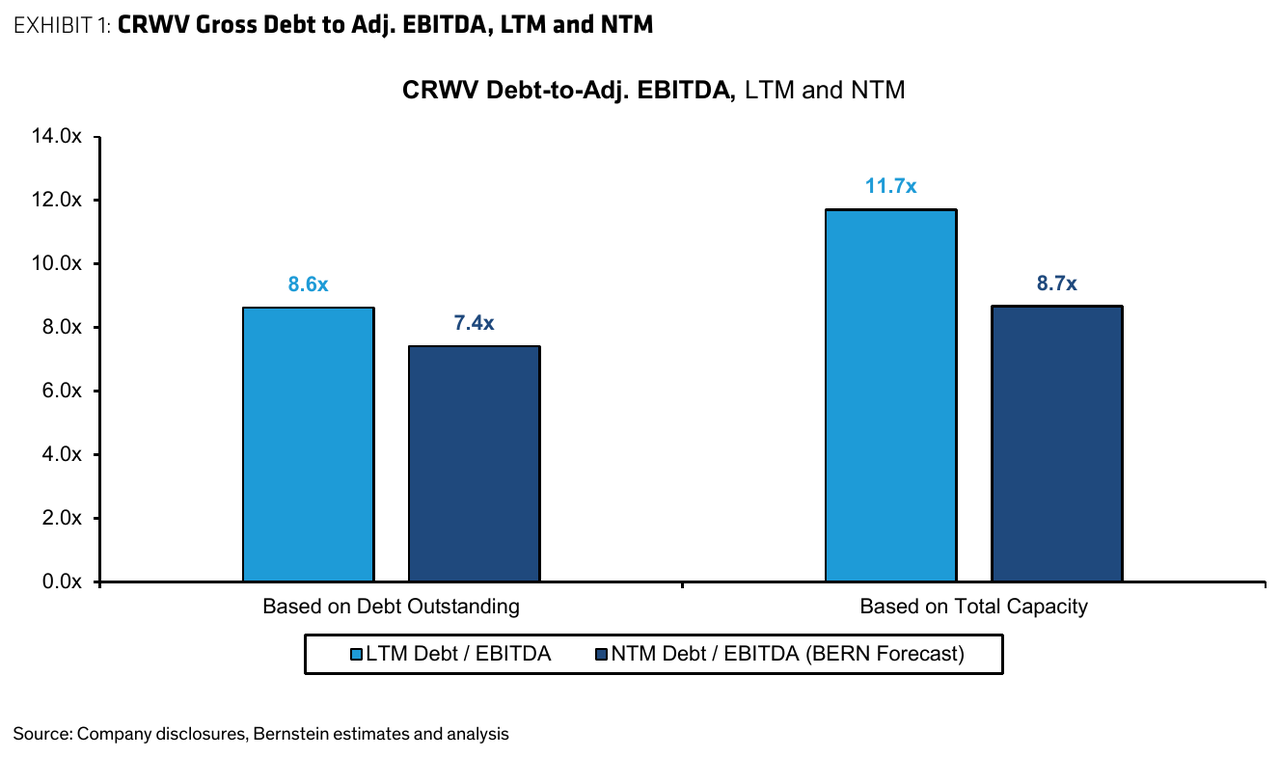
Look a little closer at that table, though, and the number gets small mostly because of what goes into it. In Scenario 1, CoreWeave needs about $60 billion of capex to serve its backlog. Goldman assumes 80% can be debt-financed through DDTLs, subtracts $10.6 billion of committed-but-undrawn DDTL capacity and $10.4 billion of “cash optionality”, and arrives at $36.7 billion of new debt. To get to the headline $22.9 billion, it then assumes customers hand over 20% of total contract value up front, or $15.7 billion. Stretch GPU useful life to six years, and the number shrinks further to $19.5 billion.
A few problems with that:
- The prepayments are going the wrong way. By Goldman’s own admission, “CoreWeave’s prepayment percentages have come down in the last 6 months.” Goldman’s spin is that this “suggest[s] these percentages can also go up in an environment where there is less visibility into debt financing.” Translation: when CoreWeave can’t borrow, its customers will happily lend it the money instead. Maybe. Or maybe customers who just watched CoreWeave’s bonds trade at 15% decide they’d rather not prepay a counterparty with distressed debt.
- The “cash optionality” is optimistic. The $10.4 billion includes $2.2 billion from selling 35 million ATM shares at $64, about 9% above where the stock trades this morning, and a $2 billion revolver. According to Bernstein’s debt table (as of Oct 20), $1.2 billion of the $2.5 billion revolver is already drawn, which would leave $1.3 billion.
- The 4.2GW number needs $52.7 billion of customer money. Scenario 3’s $38 billion assumes prepayments of $52.7 billion. Without them, the new debt needed is $84.5 billion, at a 94% debt-to-loan ratio, which is well above the 80% cap Goldman itself says the DDTL structure allows. Funny how that number didn’t make the title.
- There is no cost of capital anywhere in the note. Goldman calculates how much CoreWeave needs to borrow, but not at what rate, deferring to the “financing cost assumptions in our upgrade note” (the one with a 10% cost of new debt, about two-thirds of what CoreWeave’s unsecured bonds currently yield).
Here is the full range of answers to “how much does CoreWeave still need to borrow”, depending on whose spreadsheet you trust and what you assume customers will do:
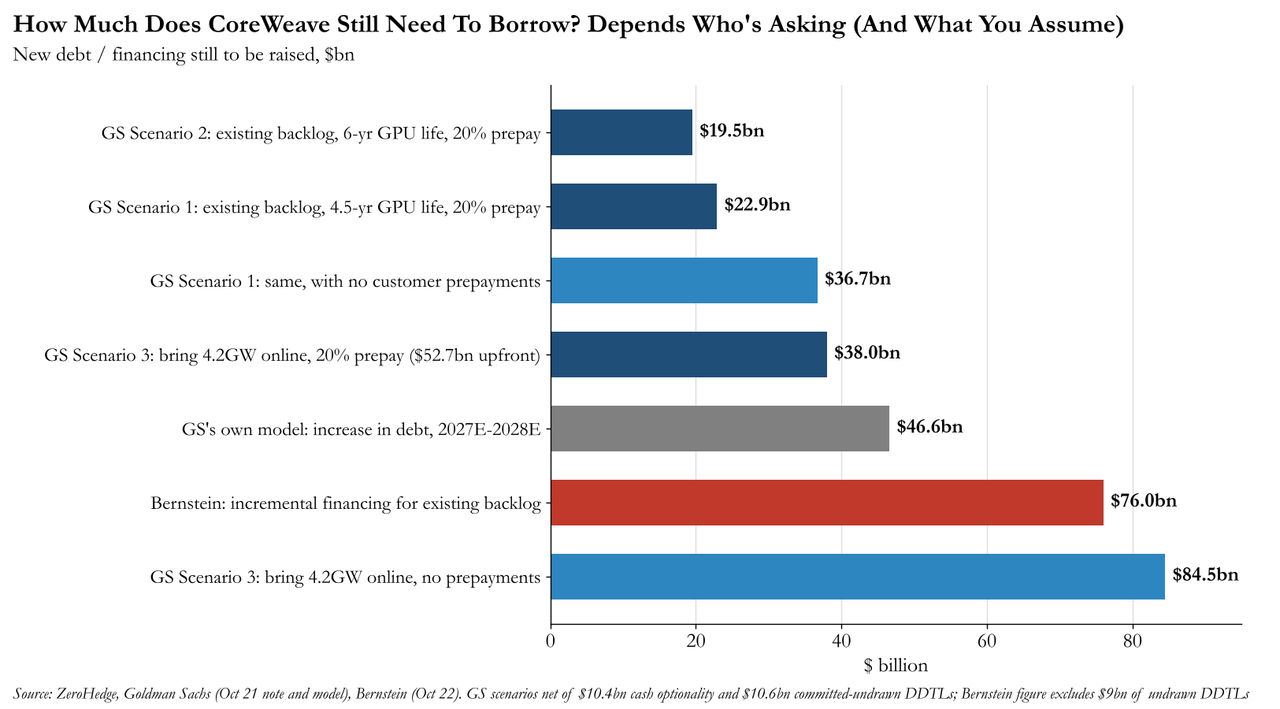
To Goldman’s credit, the note ends with “Our worksheet is available on request and we welcome feedback on our assumptions.” Consider this our feedback.
Goldman’s Model Disagrees With Goldman’s Note
The irony is that the best rebuttal to Goldman’s funding note can be found on page 2 of the very same note, in Goldman’s own financial model. Ignore the illustrative scenarios and look at the cash flow statement, and Goldman has CoreWeave burning $28.2 billion of free cash flow in 2026, another $28.2 billion in 2027 and $15.8 billion in 2028, on capex of $38.6 billion, $48.0 billion and $49.9 billion. To fund that, Goldman’s model has debt increasing by $26.7 billion this year, $26.6 billion in 2027 and $20.0 billion in 2028. That’s $46.6 billion of new debt in the next two years alone, double the headline “funding gap”, and that’s before $50 billion of lease liabilities which Goldman models by 2028 (and which are, of course, debt by another name).
Long-term debt goes from $14.9 billion at the end of 2025 to $90.8 billion by 2028. Goldman’s interest coverage ratio for CoreWeave is 0.3x this year and 0.7x in 2027, meaning operating profit doesn’t even cover the interest bill until 2028, when it reaches a still-miserable 1.3x. Net debt to equity peaks at 3,059% in 2027. And cash on the balance sheet drops to $1.2 billion at the end of 2027, which is a little thin for a company with $6 billion in annual interest expense (also per Goldman).
Which brings us to the obligatory disclosure appendix, where Goldman notes it “is acting as a manager or co-manager of a pending underwriting” for CoreWeave, owns 1% or more of the stock, and expects “to receive or intends to seek compensation for investment banking services in the next 3 months.” As we said on Tuesday, none of this makes the analysis right or wrong. But if CoreWeave really does need somewhere between $20 billion and $85 billion in new money, it’s nice to know who’ll be helping raise it (the same one, mind you, that just upgraded the stock).
15% Money And The DDTL Treadmill
Back to Bernstein, which does what Goldman doesn’t: it looks at what the debt costs, when it comes due and who it sits with. CoreWeave has $42.1 billion of debt outstanding and a $3.3 billion annual interest bill, a blended rate of 7.8% that is dragged down by $10.8 billion of 2-3% converts. Everything else is priced like junk, because it is.
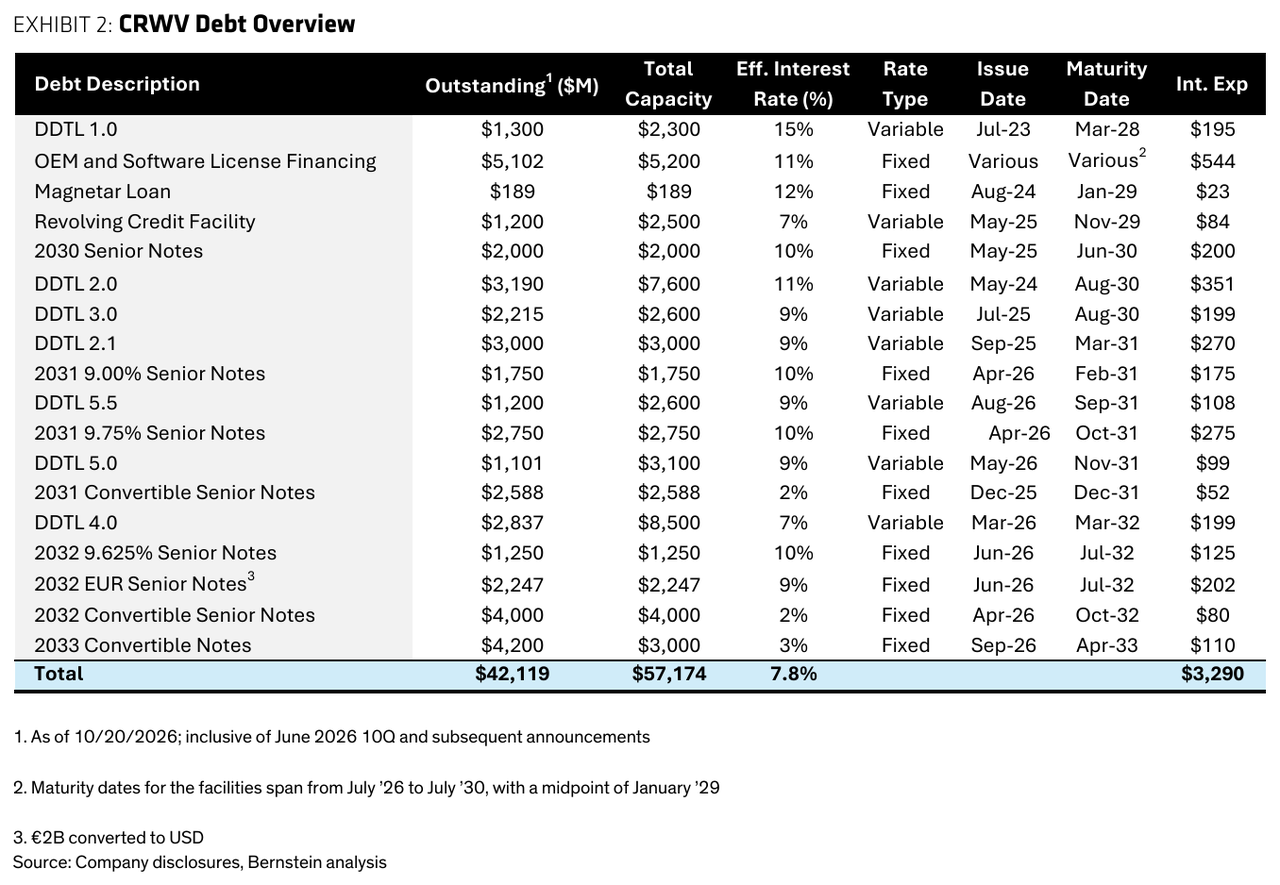
On Bernstein’s numbers, CoreWeave’s gross debt is 8.6x LTM adjusted EBITDA, or 11.7x on total committed capacity, and still 7.4x on next year’s EBITDA:
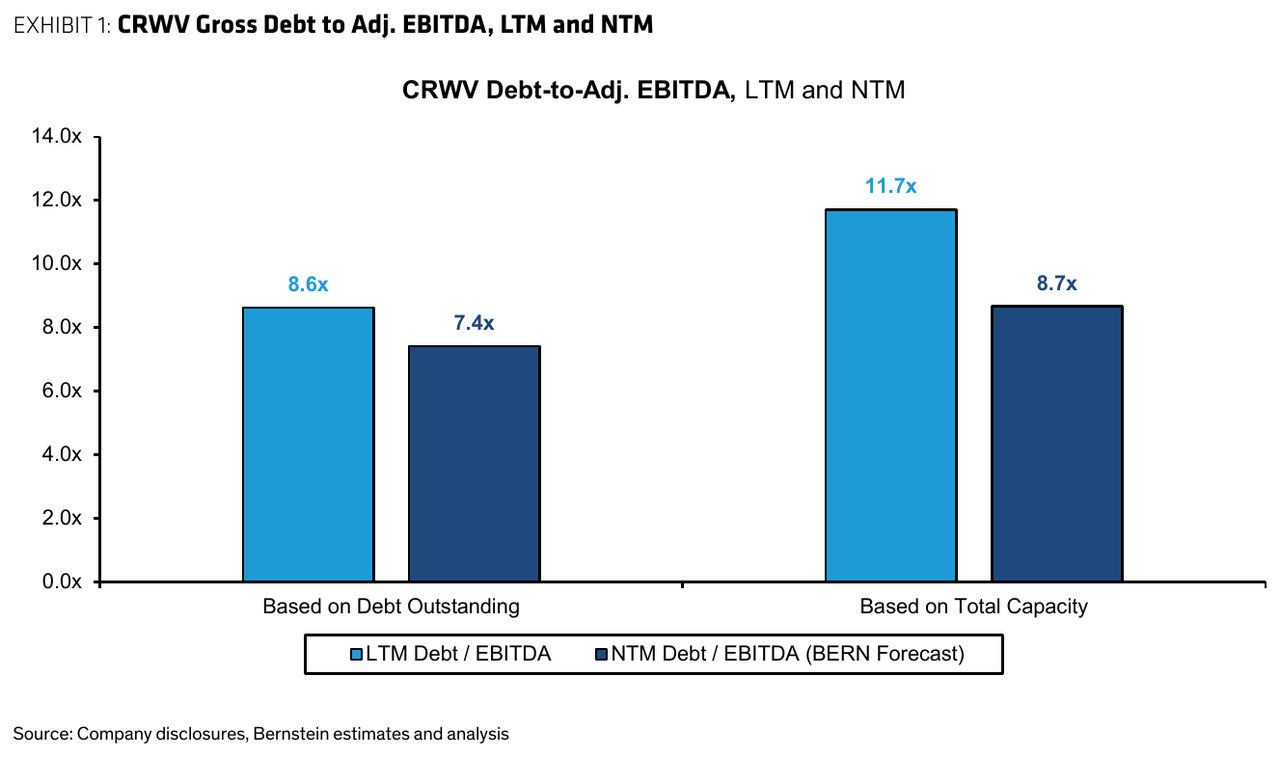
The good news is that most of the debt matures in 2030-2032 (about $31 billion in those three years), so Bernstein does not “expect the company to see real distress anytime soon.” The less good news is that the DDTLs are amortizing structures, and “principal repayments and covenant tests begin well before final maturity, making near-term debt service and covenant headroom important considerations.“
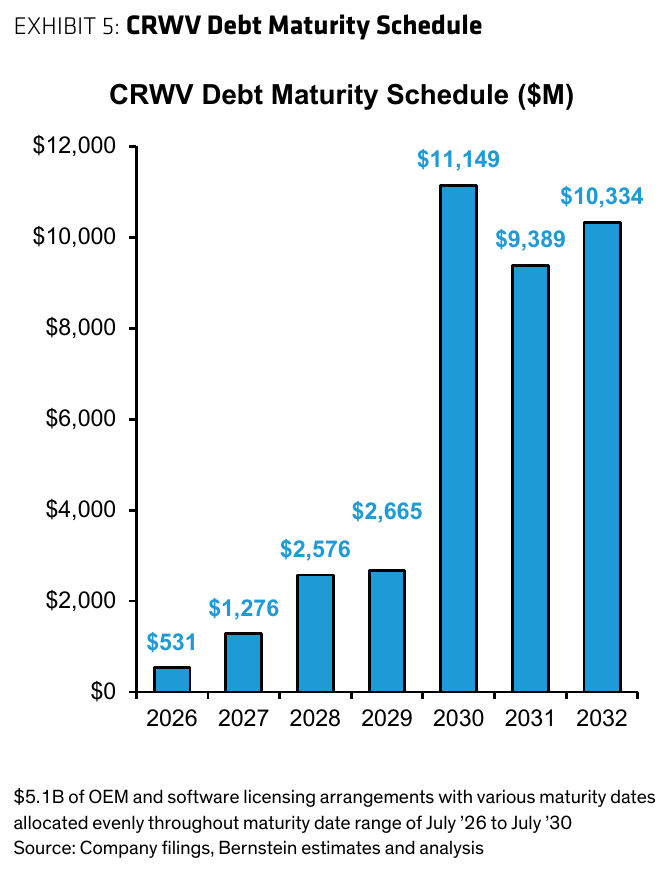
How near-term? According to Bernstein’s DDTL calendar, monthly repayments on DDTL 5.0 begin around October 22, 2026, i.e. today (CoreWeave says November), with the first 1.35x DSCR covenant test due around November 30. DDTL 5.5 starts amortizing in January, and the $8.5 billion DDTL 4.0 next July:
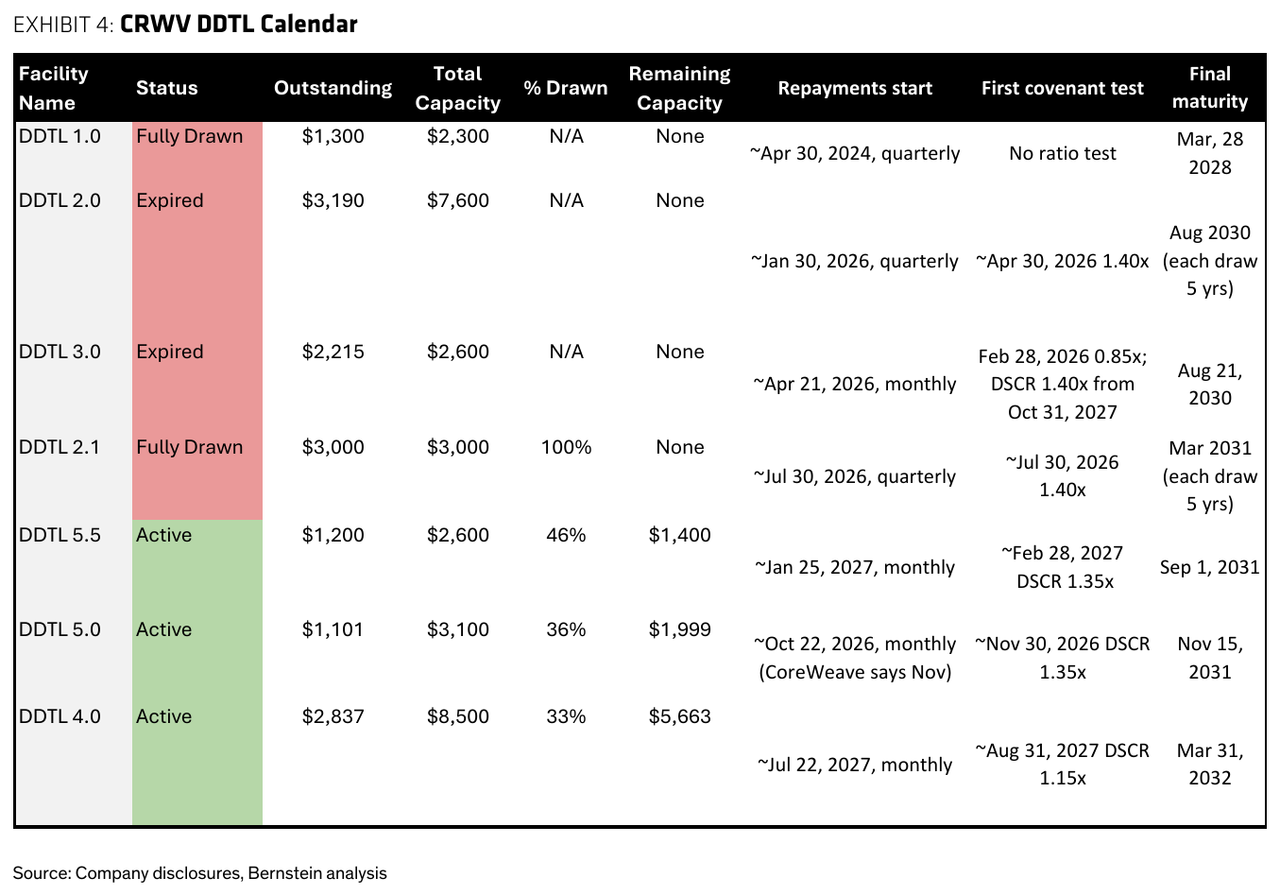
Then there’s the cost of new money. CoreWeave’s unsecured bonds yield around 15%, which Bernstein calls “an important signal of the market’s required compensation for risk,” and the most recent secured facility was hardly cheap either: DDTL 5.5, priced in August, came in at SOFR+5.50%, the widest spread since the very first DDTL in 2023. Bernstein thinks “subsequent deals could price even higher.“
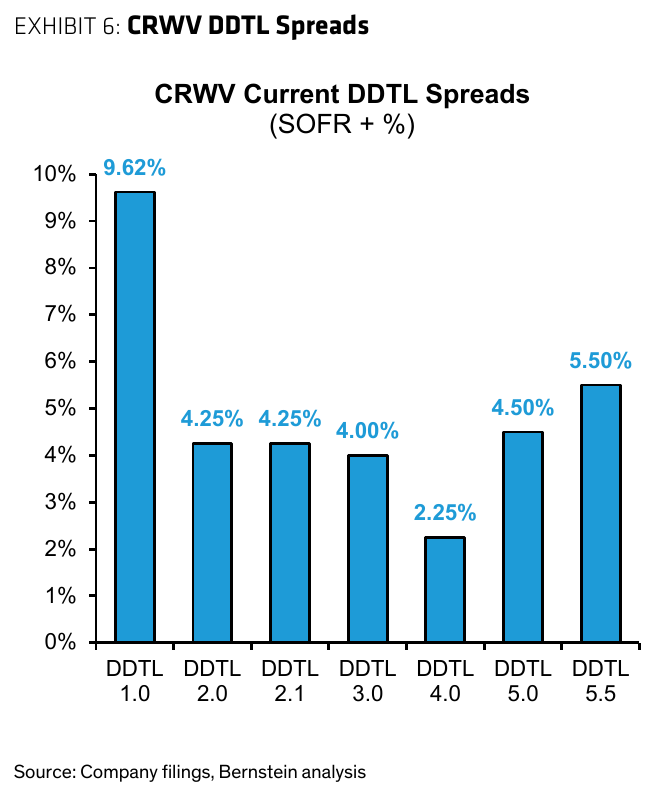
And here is the catch-22 at the heart of Bernstein’s thesis. CoreWeave needs to move toward shorter contracts with enterprise customers to remain competitive with hyperscalers (who are also its biggest customers and are building their own capacity). Shorter contracts capture higher pricing per MW. But…
“Unfortunately those contracts are riskier to creditors and do not help CRWV lower its cost of capital. DDTL 5.5 was at SOFR+5.5% – this is the best proxy; subsequent deals could price even higher.”
Put differently, the more CoreWeave does what it needs to do strategically, the more it costs to fund. Bernstein assigns “a low, nonzero probability” to CoreWeave building a sufficiently differentiated enterprise business, which is about as polite as sell-side prose gets.
A 9% Business With A 32% Story
Which brings us to returns. Bernstein runs the numbers on what it believes is CoreWeave’s best contract, the Meta deal (including the $21 billion expansion), and gets a best-case unlevered IRR of 9-12% (9% in its illustrative model). Levered, it jumps to 32%, which sounds great until you look at how it gets there:
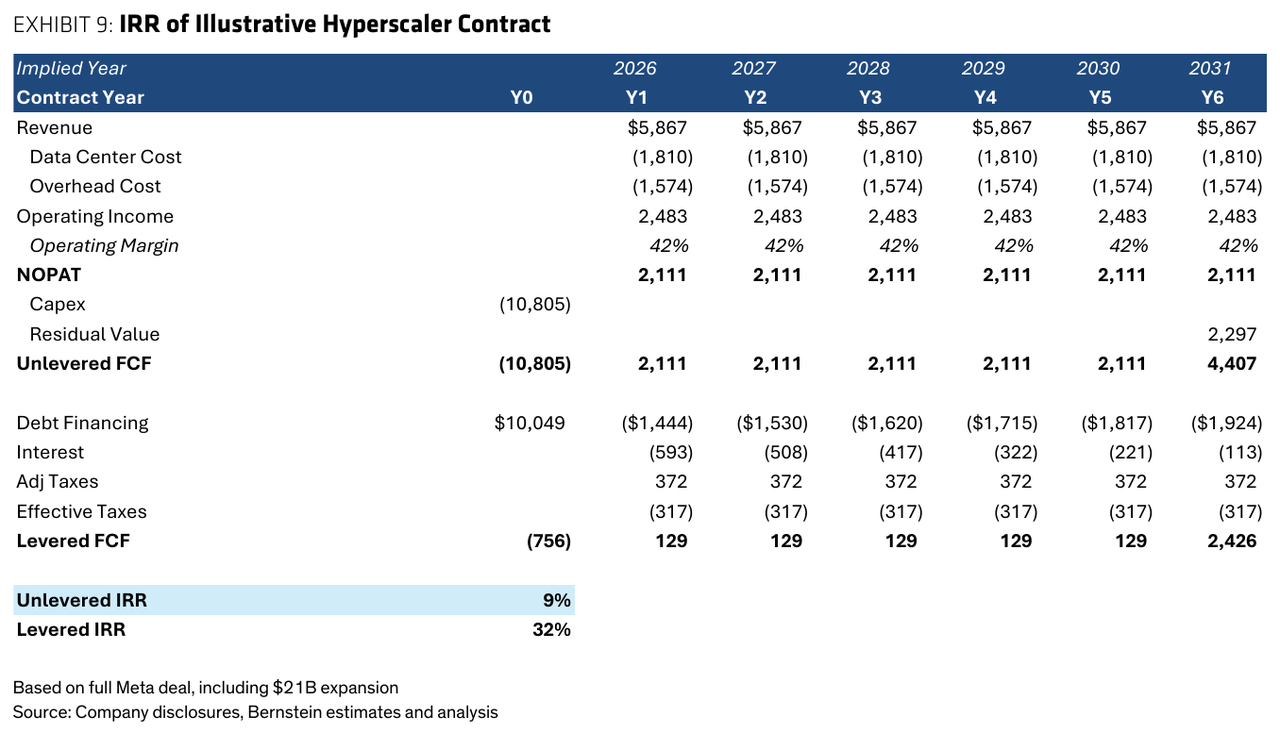
CoreWeave spends $10.8 billion of capex, borrows $10 billion of it, puts in $756 million of equity, and then collects… $129 million a year in levered free cash flow for five years, with the bulk of the return riding on a $2.3 billion residual value in year six. In other words, the 32% is almost entirely leverage plus a bet on what six-year-old GPUs will be worth in 2031. And that’s on 9% unlevered returns, against new money that costs 9% secured and 15% unsecured. HSBC made the same point on Tuesday with its 8.9% ROIC, and Bernstein’s math gets to the same place from a different direction.
Management says contracts signed since 2Q have “materially better economics.” Bernstein’s response is that the newer contracts “may be too small to change overall blended returns meaningfully,” and its “view leans toward medium-term economics resembling the older contracts more closely.“
Not A Zero… Just A Ward Of Jensen
To be fair to CoreWeave, Bernstein is not calling for a wipeout: “We do not believe CRWV is a 0 – they still have a large backlog, line of sight to powered shell delivery, and while we don’t think the contracts are super attractive, they’re not underwater.” Prediction markets seem to agree, at least after SpaceX’s blowout quarter:
The floor, in Bernstein’s view, is the same one that has been debated on these pages since the meltdown began last week: Nvidia. Asked whether Jensen would step in, Bernstein says “we think they would intervene in a true downside. Doesn’t necessarily re-energize the stock, but raises the floor.” Which is great news for CoreWeave shareholders, if a little awkward for Huang, who told everyone last week that CoreWeave’s cost of capital was “actually decreasing.” Well, no… it’s not of course, and as one of our contributors put it on Saturday, Jensen will blink first.
Bernstein’s other conclusion is that the damage is “semi-contained“: “If it ceased to exist tomorrow, colo contracts would be absorbed and the rest of the market would carry on.” We’d put more weight on the “semi” than the “contained.” CoreWeave is still the market’s beta barometer for AI credit, it’s the tenant on seven of the 20 project-finance data center bonds in the junk market, and the neocloud listings that tried to follow it to market keep faceplanting. Here is the latest casualty list:
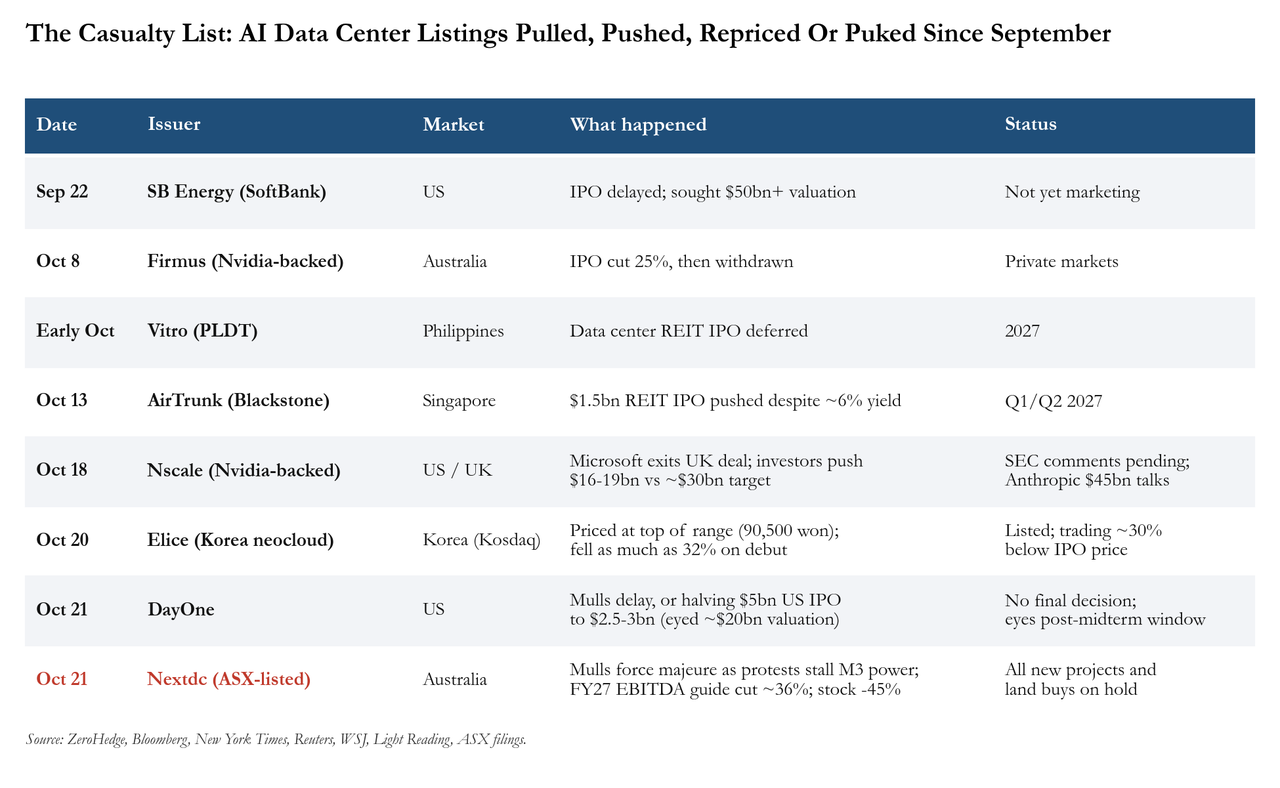
Rezaei closes with what might be the most honest paragraph written about CoreWeave all month:
“We caught a lot of hate when we initiated on CRWV with a $56 price target seven months ago. Today, it’s a lot harder to find bulls – certainly some of them just don’t call us anymore, but there seems to be more broad acceptance of the challenges of this business model. Could this turn around? Maybe: it’s a wildly volatile, momentum-driven stock, but barring major moves, the fundamentals are probably stuck.”
So there you have it: one bank says CoreWeave’s funding gap is $23 billion if customers prepay, GPUs last six years and the stock goes back to $64; the other says $76 billion, at 15%, for a business earning 9% (obviously, one is wrong).
Goldman’s own model, meanwhile, quietly sides with the latter. Having warned since last October that AI had quietly become a debt bubble too, we know which spreadsheet we’d trust, and it’s probably not the one attached to a pending underwriting. The bills, as Bernstein puts it, still have to be paid, and the first DDTL 5.0 installment comes due right about now.
Much more in the full Bernstein “Core-We’ve got bills to pay… lowering our PT” note and Goldman’s “How big is the funding gap?“, both available to pro subs.
KING NEWS
| The King Report October 22, 2026 Issue 7853 | Independent View of the News |
| Netanyahu: ‘Iran is again trying to develop the death bomb’ Prime Minister Benjamin Netanyahu said at the officers’ graduation ceremony at the National Defense College that “we are facing an existential threat. Mojtaba Khamenei liberated Nazareth, and Iran is trying again to develop death bombs. Therefore, there is only one way to remove this threat once and for all – to topple the regime in Iran. This is my directive to the IDF, the Mossad and the security forces. My friend President Trump also believes this is the only way. He said a few days ago, ‘We are ready to finish the job, but we will do it only with you, the State of Israel.'” https://www.ynetnews.com/article/7eo107dnh IDF decides not to livestream any part of Netanyahu-attended cadets graduation ceremony over electioneering concerns https://www.timesofisrael.com/liveblog_entry/idf-decides-not-to-livestream-any-part-of-netanyahu-attended-cadets-graduation-ceremony-over-electioneering-concerns/ Zelensky says he’d accept Russian peace deal that ‘freezes’ front lines: ‘Real way to end war’ https://trib.al/Ih3iwYH Putin agrees to resume trilateral talks on Ukraine war with Kyiv and Washington, Kremlin says The Russian leader has agreed “in principle” to resume the talks after Nov. 10, Putin’s foreign affairs adviser Yuri Ushakov told reporters following a meeting in St. Petersburg between Putin and U.S. President Donald Trump’s envoy Steve Witkoff… https://apnews.com/article/russia-ukraine-witkoff-putin-trump-zelenskyy-talks-3f00c0c6fd10bab948c2c3f8502e0a91 Witkoff faces backlash for calling Putin a “humanitarian”: “Embarrassing and outrageous”: CBS https://www.cbsnews.com/news/steve-witkoff-putin-humanitarian-backlash/ @visegrad24: Witkoff on Russian diesel exports to the US: “I want to thank you for your decision to remove export controls on diesel oil from Russia and to sell not just to the United States but also to the world at large. I know the President is deeply grateful for it, as are our farmers and other truckers who use diesel and have been adversely affected by this diesel crisis, and people all over the world. So it’s an example of us all working together, and I want to say thank you to you for that.” https://x.com/visegrad24/status/2112855327443980601 @realDonaldTrump: Stephen Hubbard, taken four years ago by Russia during the Biden Administration, was just released from prison, at the request of President Donald J. Trump… The United States, out of respect for President Trump, was not required to give anything in return (You waived sanctions!) – an unprecedented situation for Russia. There was no “swap” necessary for this release… “Welcome home Stephen, it’s great to have you back,”… Oct 21, 2026, 6:37 AM Numerous people, who requested that sanctions be immediately imposed on Russia, have called to apologize to President Trump… they didn’t know that he was negotiating the release of Hubbard… ABC: The 73-year-old American has spent roughly three years in Russian captivity. In early 2022, he was swept up by the Kremlin’s troops as they occupied parts of Ukraine following Russia’s full-scale invasion. He is believed to be the only American Russia has taken from Ukraine and put on trial. Russia convicted Hubbard as a mercenary fighting for Ukraine. But his family, the U.S. government and Ukrainian officials say the reality is that the elderly American was an innocent teacher… https://abcnews.com/US/american-teachers-sister-pleads-release-russian-captivity/story?id=120490830 UK government approves a natural gas project off Scotland despite environmental concerns https://apnews.com/article/uk-natural-gas-project-scotland-environment-b646f449474d0b00620b47f3794a4c2c The usual suspects bought trading sardines, notably AI and Fangs issues, early on Wednesday. Netflix was sold on its disappointing guidance. Google fell on this: Revolut Outage Hits Crypto Access as Google Cloud Failure Disrupts Banking Services The Revolut outage a few hours ago disrupted crypto services, card payments and bank transfers after a Google Cloud incident affected its London infrastructure. The British fintech said customers’ money and data remained safe, but the disruption raised questions about the reliability of a centralized platform experience… https://finance.yahoo.com/markets/crypto/articles/revolut-outage-hits-crypto-access-071419863.html SpaceX stock jumps 9% after Musk says the company is exploring a merger with Tesla https://www.msn.com/en-us/news/other/spacex-stock-jumps-10-after-musk-says-the-company-is-exploring-a-merger-with-tesla/ar-AA2fIS7k?ocid=BingNewsSerp The 5 most important numbers from SpaceX’s earnings SpaceX’s third-quarter revenue grew 161% to $14.6 billion, beating analysts’ expectations. 2. AI was more than half of the revenue… 3. 1.6 million new Starlink subscribers 4. Compute capacity: At the end of the second quarter, SpaceX reported 1.4 gigawatts of compute capacity. Just three months later, it has surpassed 1.7 gigawatts, putting the company on track to exceed 2 GW by the end of the year. 5. Capex is growing: It shouldn’t come as too much of a surprise, but building gigawatts of compute capacity is expensive. SpaceX spent $19.6 billion on capex in the third quarter, $16.4 billion of which was spent on AI computing. So far in 2026, SpaceX’s capital spending exceeded operating cash flow by about $35 billion… with about $90 billion in cash and securities on its balance sheet and less than $40 billion in debt, the company is in an excellent financial position… https://www.msn.com/en-us/news/other/the-5-most-important-numbers-from-spacex-s-earnings/ar-AA2fJyJU?ocid=BingNewsSerp WSJ: AI Just Found a Bug That Puts Up to 70% of the World’s Websites at Risk AI tools helped find one of the most severe online bugs ever. Cyber experts are racing to patch it before hackers use AI to exploit it… The creators of PHP, a technology that powers as much as 70% of the world’s websites, disclosed a critical security issue Wednesday that could be leveraged by hackers to take control of any system running its software. That would allow an attacker to steal information or launch a cyberattack on anyone visiting a hacked website… https://www.wsj.com/tech/cybersecurity/ai-just-found-a-bug-that-puts-up-to-70-of-the-worlds-websites-at-risk-fd0902ea The WH: Federal agencies are assessing the potential impact on government systems and critical infrastructure regarding the PHP issue. NSA Advisory: PHP Updates: Effective Immediately, all organizations using PHP for their systems are advised to be prepared for an update addressing two critical vulnerabilities. PHP is widely used for web applications… If an immediate update is not feasible, it is recommended that organizations take the system offline until it can be fully mitigated. NSA will follow up shortly with more specific guidance. https://www.nsa.gov/Press-Room/Press-Releases-Statements/Press-Release-View/Article/4630238/nsa-advisory-php-updates/ Near 10:05 ET on Wed: SPCX +11.0%, MU +0.77%, TSLA +3.22%, GOOGL -2.76%, META +1.66%, AMD +1.2%, NFLX -4.34%, AAPL +0.21%, INTC -0.45%; S&P 500 500 +0.28%, DJIA +0.01%, Nasdaq + 0.79%, Nas 100 +0.84%, SOX Index +1.51% The S&P 500 gapped higher (7736.43, +23.86 pts) on the opening and quickly double topped (7738.65 seconds after the opening and 7738.70 at 9:47 ET). A pro dump appeared; the index fell to a daily low of 7709.34 at 10:12 ET. The S&P 500 then intractably rallied to 7755.21 at 11:50 ET and rolled over. After retreating to 7746.37 at 12:28 ET, the S&P 500 rallied modestly but spiked from 7750.17 at 12:39 ET to a new high of 7764.84 at 12:40 ET. After a drop to 7755.16 at 12:45 ET, the S&P rallied to 7770.40 at 14:16 ET. The index then went inert. It tumbled on the following related reports: US embassy orders all American staff, families to leave Saudi Arabia: diplomatic source – AFP Saudi Arabia: 2 killed in drone attack targeting oil facilities (Aramco’s Shaybah oilfield in east SA) https://www.ynetnews.com/article/bnfvx6vdd And possibly on this: Latest proposals to end the war have little of value, Kremlin says The discussion in St. Petersburg lasted about three hours, the Kremlin said… The proposals from the Oslo meeting “contained little of real value in the context of resolving the Ukrainian crisis,” Ushakov said. However, he later told Russian state TV that while Moscow isn’t “fully satisfied” with the Oslo proposals, they are a step in the right direction. Witkoff’s meetings suggested leaders are keen to bring new momentum to U.S.-led peace efforts, more than 4½ years after the war began. Efforts by the Trump administration since early last year to end the war have made no significant progress. Zelenskyy said freezing the conflict in Ukraine was the “minimum” required from Russia to bring about an end to the war. “Right now, we have to freeze, and I think this is (the) real way to end this war,” Zelenskyy said in an interview broadcast Wednesday on Fox News. https://www.2news.com/news/national/trump-envoy-witkoff-meets-putin-in-st-petersburg-for-ukraine-war-talks/article_5ff0cc73-934b-54d1-8c24-197fd42a954f.html The S&P 500 Index sank to 7730.96 at 15:03 ET. However, Meta’s expected great results were only an hour or so from release. So, traders bought trading sardines (tech & AI); the S&P rose to 7764.17 at 15:51 ET. The S&P rolled over and closed at 7757.17, +0.58%. US 20-Year Bond Auction ($13B): High Yield 5.469%, 5.46 WI, 0.9bps tail; 60.05% of bids at high; Primary Dealers 10.3%. Direct Bids 31.6%, Indirect Bids 58.2% @MittRomney: Churchill could have shortened WW2 by years if he had just “done a deal” with Hitler. George Washington could have done a deal to end the American Revolution. Zelenskyy is in good company. (Hey Mitt, didn’t Stalin do a deal with Hitler? And didn’t Hitler invade Russia anyway?) The daffy and sappy Romney conveniently or stupidly ignores Chamberlain’s deal with Hitler, officially the Munich Agreement of 1938, in which Britain, France, Germany, and Italy allowed Hitler to annex the Sudetenland of Czechoslovakia in exchange for a promise of peace. You can look it up! Positive aspects of previous session S&P 500 +0.58%, DJIA +0.69%, DJTA +0.19%, Nasdaq +1.05%, Nas 100 +1.13%, SOX Index +1.97% SP Info Tech +1.61%, Industrials +0.91%, Financials +0.56%, Utes +0.37%, Energy +0.28%, Consumer Discretionary +0.23%, Materials +0.19%; USZs +6/32; Nov Diesel -13.27¢, Nov WTI -$0.11 Negative aspects of previous session SP Communication Servies -1.33%, Real Estate -0.79%, Consumer Staples -0.59%, Healthcare -0.45% USZs +6/32, down from +17/32. Notes down modestly. Nov Gasoline +0.0167¢; Dec Brent +$0.10 Ambiguous aspects of previous session How big will the opening rally be? First Hour/Last Hour NYSE Action [S&P 500 Index]: 1st Hour: Down; Last Hour: Up Pivot Point for S&P 500 Index [above/below indicates daily trend to day traders]: 7745.80 Previous session (S&P 500 Index) High/Low: 7770.40 (14:16 ET); 7709.34 (10:12 ET) WSJ: Autism-Therapy Workers Say Big Chains Pressured Them to Boost Treatment Hours Medicaid data show some private-equity-backed chains billed far more hours than rivals; companies say patient needs guide treatment https://www.wsj.com/health/healthcare/autism-therapy-treatment-hours-private-equity-5781f2ca WSJ: Airfield Attack Marked Opening Shot in Putin’s Stepped-Up Sabotage Campaign U.S. intelligence agencies say the failed operation in Germany this summer was part of a new wave of attacks ordered by the Russian leader A massive cargo plane, used to carry military assistance to Ukraine and parked at an airfield in eastern Germany, was attacked by explosive-packed drones in early August. German officials say they were piloted by Russian military-intelligence agents. One drone slammed into the Antonov freighter but failed to explode. Another collided with a different plane, and a third detonated near the airport perimeter, authorities say. Had the assault worked as planned, investigators say, the result would have been mayhem and casualties at one of Europe’s most important air-cargo airports… https://www.wsj.com/world/europe/airfield-attack-marked-opening-shot-in-putins-sabotage-campaign-against-europe-115dedd4?st=VLhjpb The WSJ article notes that Russia is frustrated that the land war in Ukraine is stalemated. So, last summer Putin had the GRU (Russian military intel) perform sabotage in European nations that supported Ukraine. Aides to German Chancellor Friedrich Merz say that if the Leipzig attack had resulted in large numbers of casualties, they would have considered invoking the collective-defense provision of the North Atlantic Treaty Organization, known as Article 5, which would oblige the rest of the alliance to rally to protect Germany… https://www.tovima.com/wsj/airfield-attack-marked-opening-shot-in-putins-sabotage-campaign-against-europe/ META Q3 EPS 3.83; 3.57 exp; Revenue $64.6B, $63.368B exp; Capex: $34.91B; Free cash flow -$2.12B; Operating margin 20%; Advertising revenue $63.06B; Costs& expenses include a $9.89B charge related to legal proceedings; Family daily active people 3.64B on average for September; Headcount 66,775 as of Sep 30, -15% y/y; Meta declared a one-time non-voting ‘Class C’ stock dividend. Meta projects Q4 revenue $73B-$76B, $73.73B exp; and FY capex at $135B-$145B, prior $130B-$145B META was +6.03% at 16:45 ET because the Meta CFO Susan Li claims new AI businesses can begin contributing incremental revenue in 2027. META lost 2/3 of its rally after Li said, “Muse’s compute intensity means that expanding its user base will require significant investment, and we expect total serving costs to rise. At the same time, we expect to improve compute cost efficiency by more than 10-fold over the next year.” Tesla Q3 Adj EPS .48, .33 exp: Rev $28.05B, $28.13B exp; Auto Revenue: $20.56B, $19.83B exp; Services & Other Revenue: $4.61B, $4.30B exp. TSLA was +1.65% at 16:06 but -2.38% at 18:27 ET. FT: Elon Musk sets lower sales target for Tesla as it explores SpaceX merger Carmaker reports flat revenue and falling profits as it pivots from electric vehicles to AI https://www.ft.com/content/16bdf332-2a75-4e57-81ea-a37caf50ec0f?syn-25a6b1a6=1 IBM Q3 EPS 2.95, 2.86 exp; Rev $17.1B, $16.83B exp; Software Revenue $7.80B, 7.64B exp; Consulting Revenue $5.34B, $5.39B; Sees FY Rev Growth (Constant Currency) +4% To +5%, +4.12% expected. IBM was +7.06% at 16:49 ET, but +0.11% at 18:28 ET. Today – We originally thought that stocks should start higher on the after-hour rallies in Meta, IBM, and Tesla. Plus, it’s the heart of trading sardine (tech) reporting season. But the after-hour rallies mostly disappeared. So, ESZs and NQZ are down smartly. Here’s a reason for the Wednesday night angst: Channel 12 (ISR) reports US airstrikes might have destroyed 2 IRGC Navy anti-ship missile launchers near Sirik in southern Iran. Earlier, there were explosions and smoke in that area. https://www.newsquawk.com/headlines/explosions-were-reportedly-heard-in-irans-port-city-of-sirik-with-claims-that-us-forces-struck-an-anti-ship-missile-launcher-targeting-vessels-in-the-strait-of-hormuz-israels-channel-12-reports Pentagon deploys USS Theodore Roosevelt to Middle East as Trump weighs Iran strikes https://www.jpost.com/middle-east/article-912321 Netanyahu vows to eliminate Iran regime, sources tell ‘Post’ Trump ‘very close’ to renewing strikes https://www.jpost.com/middle-east/iran-news/article-912315 Google AI: Reports from Haaretz indicate that the U.S. position has shifted toward favoring a preemptive strike on Iran. The reported change follows intelligence briefings given to President Trump by Defense Secretary Pete Hegseth after a meeting with Israeli Prime Minister Benjamin Netanyahu. Iran is purposely tanking peace talks to hurt Trump at the polls, regime officials admit https://trib.al/UxHGR4Q The US and Israel have drawn up plans for a new bombing campaign against Iran after the midterm elections: US officials – NYT No trading sardines are scheduled to report results today. So, the stock prop is absent. ESZs -34.50; NQZs -210.50, USZs +18/32, Nov WTI +$0.92, Nov Gas +2.50¢, ¥/$ 158.17 at 20:02 ET Expected earnings per Nasdaq: PG 1.89, UNP 3.47, LMT 7.49, CMCSA 0.98, NSC 3.48, DOW 0.63, PHM 2.62, R 4.16, AAL -0.28 Expected Economic Data: Initial Jobless Claims 200k, Continuing Claims 1.72m; Sept LEI -0.1% m/m; 20-year Auction ($13B, reopening, 19 years, 10 months); noncompetitive bids 12 ET, competitive 13 ET S&P 500 50-day MA: 7705; 100-day MA: 7603; 200-day MA: 7282 (Close 7757.17, +0.58%) Nasdaq 100 50-day MA: 29,867; 100-day MA: 29,604; 200-day MA: 27,803 (Close 29,822.52, +1.13%) DJIA 50-day MA: 52,371; 100-day MA: 52,274; 200-day MA: 50,499 (Close 52,856.09, +0.69%) (Green is positive slope; Red is negative slope) Fake polling firm duped media in ‘social experiment’ A polling firm whose surveys were reproduced by prominent media outlets, including Newsweek, has said that its results were fabricated and that the deception was a social experiment to expose weaknesses in the industry. Wedgewood Polls made the statement on October 20 after researchers at election analysis website FiftyPlusOne confronted it with evidence that its underlying data was fake… Wedgewood Polls said that the operation was intended to establish how easily a fictitious polling company could obtain recognition from polling aggregators & media outlets… (Cuz it favored Dems?) The results were also included in prominent polling databases, including those maintained by The New York Times, Nate Silver, VoteHub, and FiftyPlusOne, before the firm was exposed by FiftyPlusOne… One early survey covered Louisiana’s Republican Senate primary and showed John Fleming leading Julia Letlow by 4 percentage points. Letlow defeated Fleming by almost 14 points on June 27… https://www.msn.com/en-us/news/other/fake-polling-firm-duped-media-in-social-experiment/ar-AA2fKdj1?ocid=BingNewsSerp Newsweek: Retracted: Democrat threatens historic Senate upset in deep-red Mississippi Newsweek has retracted this article, which cited a poll from Wedgewood Polls… https://www.msn.com/en-us/news/other/retracted-democrat-threatens-historic-senate-upset-in-deep-red-mississippi/ar-AA2ehFWe?ocid=BingNewsSerp @EricLDaugh: A pollster now admitted to be FRAUDULENT caused Chuck Schumer to pour over $1.2 MILLION DOLLARS into the Mississippi Senate race after “Wedgewood Polls” found the race “competitive…” > Oct. 14: “Poll” drops showing only R+4; > Dems think MS can go blue > Oct. 20: Schumer PAC confirms “first major investment” of $1.2M into red Mississippi after previously making zero investment; > Wedgewood admits to being fraudulent Poll pushed by Colom claiming Senate race with Hyde-Smith is “tied” was fake, fabricated https://magnoliatribune.com/2026/10/20/poll-pushed-by-colom-claiming-senate-race-with-hyde-smith-is-tied-was-fake-fabricated/ @WedgewoodPolls: NEW POLL: DEMOCRATS LEAD SENATE RACE IN THE DEEP RED STATE OF KANSAS U.S. Senate Dem Adan Hamilton: 50%, GOP Roger Marshall: 48% Governor GOP Ty Masterson: 52%, Dem Cindy Holscher: 48% Sep 24, 2026 @EricLDaugh: “Wedgewood Polls” just announced it was a FAKE POLLSTER and was listed in outlets like the NYT and MSNOW – Their “polls”: Texas: Talarico+2, Ohio: Brown+4. Michigan: El Sayed+6, Kansas: Hamilton+2, Maine: Jackson+4 (All Dem candidates) FiftyPlusOne just caught a pollster faking data — and they copped to it In response to a request for comment on a FiftyPlusOne investigation, Wedgewood Polls admitted their data was bogus Their statement alleges that FiftyPlusOne, the New York Times, and other poll aggregators did not conduct appropriate vetting of their firm prior to aggregating their polls; this is false… https://blog.fiftyplusone.news/p/fiftyplusone-just-caught-a-pollster What polls say about Kansas Senate race before Marshall vs. Hamilton debate: KSN-TV But 270toWin does include a survey from Wedgewood Polls, a group that appeared suddenly this year, that shows Hamilton up by 2 points. Besides Wedgewood fraud in polling, polls this week show GOP candidates with significant gains. This, of course, barring news, occurs virtually every election cycle. Polls typically show Dems with big leads in the summer, because Republicans tend to be out or on vacation. The polls then usually show small GOP gains. And then two weeks before the election, polls show significant GOP movement. This is because many polls are constructed and paid for to influence opinion and voting. And there is little chance in ‘real’ attitudes during the final few weeks before an election. So, the ‘push’ and bias is no longer needed. So, pollsters can then report honestly and salvage their reputations – and their paychecks. @politico: Capitol agenda: Dem gavels are coming for Elon Musk https://www.politico.com/live-updates/2026/10/20/congress/dem-gavels-elon-musk-01127662 @ElonMusk: “Live by the sword, die by the sword. Those who pick fights with me should understand that I will find out who is really pulling the strings and come for them, not just their puppets. Ex-W Bush Press Sec @AriFleischer: I asked Grok if the NYT or WP have shown any pictures of the rioters in France holding Palestinian flags. The answer is no. Why are these papers hiding the truth? Why are they sanitizing the news to protect Islamists? It’s not Islamophobic to show… It’s the truth. Macron accuses foreign leaders of exploiting French riots Macron said the unnamed leaders had been influenced by fake videos generated by AI about the riots… Video of running battles between masked rioters and police, as well as property being destroyed and stores being looted, spread across social media. The government admitted the police had “lost control” during the violence… (Two World Wars to save France for a leader like Macron?) https://www.msn.com/en-us/news/world/macron-accuses-foreign-leaders-of-exploiting-french-riots/ar-AA2fKliC NYT: @tylerpager: SCOOP: Julio Herrera Velutini, a Venezuelan billionaire, really wanted a pardon. He got it not long after his daughter hired Alina Habba, a lawyer close to Trump, in a deal worth more than $50 million. Habba was also working at DOJ at the time. A Billionaire Wanted a Trump Pardon. His Family Gave Alina Habba a $50 Million Deal. Julio Herrera Velutini, a prominent Venezuelan, was seeking clemency. He got it not long after his daughter gave Ms. Habba, a lawyer close to President Trump, an extraordinarily lucrative job. https://www.nytimes.com/2026/10/20/us/politics/julio-herrera-pardon-alina-habba.html | |
SWAMP STORIES FOR YOU TONIGHT
Oz Says HHS Is Deferring $1.2 Billion More From California Medicaid Funding
Wednesday, Oct 21, 2026 – 09:20 PM
Authored by Troy Myers via The Epoch Times,
Medicare and Medicaid Administrator Dr. Mehmet Oz announced in the Oval Office on Tuesday that the Department of Health and Human Services (HHS) is deferring an additional $1.2 billion in Medicaid funding from California over concerns of widespread fraud in its state healthcare programs.
The federal government’s withholding of Medicaid payments to California now totals more than $3.3 billion.
“They just got the note, and we’re doing that because of the growth of personal care services in California,” Oz said.
“California has been growing that program 24 percent in the last three years. That is twice the rate of every other state average in the country. Impossible for us to understand how that could be so.”
President Donald Trump, Vice President JD Vance, and independent journalist Nick Shirley joined Oz at the Oval Office event on Tuesday.
Trump administration officials credited Shirley for his work in exposing healthcare fraud in Minnesota last December, which launched him into the national spotlight as an independent government watchdog.
“I just was concerned about the well-being of our tax dollars,” Shirley said during the White House event. “There’s never been an incentive for anyone to ever expose fraud. In fact, when I expose fraud, instead of the mainstream media investigating the fraud, they investigated me, and people actually, in fact, wanted to kill me after I exposed the fraud.”
After his video highlighted alleged fraud in Minnesota’s daycare programs, Shirley made additional videos in New York and California.
In Oz’s announcement Tuesday, he clarified that the deferment affects California’s Medicaid payments directed to personal care services.
“Just that one little area where you’re paying someone to carry groceries upstairs for your mom, which many of you would carry groceries upstairs for your mom for free, I would think, but in California, they’ll pay you a lot of money for it, and it’s actually run by the counties,” Oz said.
Trump signed an executive order on March 16 to officially create an anti-fraud task force to be headed by Vance.
As part of Tuesday’s White House event, Trump and Vance announced a $25 million Fraud Whistleblower Incentive Program (WHIP), designed to reward Americans who help report misuses of U.S. tax dollars.
Under the program, citizens who provide tips that lead to a successful fraud conviction or a significant federal enforcement action are eligible to receive 1 percent of the amount of fraud discovered, Trump said.
The Justice Department will oversee WHIP, and Americans can submit tips online at fraud.gov.
“For the first time ever, there’ll be an incentive for people to actually go out and make that change inside their own community,” Shirley said about WHIP. “I hope by today, millions of people are empowered inside of the United States to go out and actually make a change inside your own community, and you’ll actually be rewarded for saving America money.”
Oz announced that the latest action against California’s Medicaid program was on behalf of HHS Secretary Robert F. Kennedy Jr., who said on July 21 that CMS was withholding more than $867 million in Medicaid payments to California.
“Every dollar the federal government allows to be lost to fraud, waste, and abuse is a dollar stolen from American patients and the American taxpayer,” Kennedy said at the time. “That’s money that should be going to legitimate healthcare.”
In May, Vice President JD Vance announced $1.3 billion would be withheld from California’s Medicaid payments over potentially fraudulent billing patterns.
“We want to protect these programs for the kids and the families who need them,” Vance previously said. “We want to ensure that the American taxpayer isn’t getting fleeced.”
California Gov. Gavin Newsom has called the withholding of funds politically motivated. His office did not respond to a request for comment about the latest deferment.
END
N.Y.
Hochul Weighs Ending $500 Million Medicaid Adult Day Care Program After Fraud Raids
Wednesday, Oct 21, 2026 – 08:30 PM
Authored by Chase Smith via The Epoch Times,
New York Gov. Kathy Hochul has directed the state Department of Health to consider ending the state’s Medicaid social adult day care benefit.
The directive came on the same day that state and federal investigators carried out a crackdown on providers suspected of fraud, and on the same day that Hochul announced 16 arrests in a separate auto insurance fraud investigation.
Hochul, a Democrat, stated at an Oct. 20 press conference that she had told the department to look at “all options to eliminate continued fraud, waste and abuse.” Those options include phasing out the benefit and moving participants to other services for older New Yorkers. The department’s recommendations are due by Dec. 31.
Social adult day care is a non-medical benefit offered through New York’s Medicaid managed long-term care program.
It provides daytime supervision, meals, social activities, and personal care in a community setting. More than 400 programs serve about 45,000 Medicaid members at an estimated cost of more than $500 million a year, according to the governor’s office. The federal Centers for Medicare & Medicaid Services (CMS) approves the benefit and helps fund it.
The announcement followed what the governor’s office called a months-long investigation targeting more than 100 providers. The state Department of Health, the state Office of the Medicaid Inspector General, and the state attorney general’s Medicaid Fraud Control Unit worked with the FBI and the federal Health and Human Services inspector general.
FBI agents and state officials raided programs across New York City on Oct. 20. CMS Administrator Dr. Mehmet Oz called the operation the largest enforcement action of its kind.
Hochul said she had gone to Washington to meet with Oz to discuss working together against Medicaid fraud, and that the investigation is targeting providers suspected of money laundering, kickbacks, and improper billing.
“We will find you, we will prosecute you, and we will hold you accountable,” Hochul said.
At the same press conference, Hochul announced that a joint investigation by the State Police and the Department of Financial Services had led to 16 arrests in auto insurance fraud cases.
The cases involved nearly $500,000 in attempted fraudulent claims in New York City and Suffolk, Onondaga, Monroe, and Erie counties. Hochul said New Yorkers pay about $4,000 a year for auto insurance, almost $1,500 more than the national average, and that she expects the arrests and insurance reforms in this year’s state budget to start lowering rates.
Reviewing Adult Day Care Claims
Regarding the crackdown on adult day care fraud, Hochul ordered the department and the state Medicaid inspector general to require health plans to review social adult day care claims before paying them and to pursue payment suspensions. A moratorium on new providers that the department imposed in July remains in effect until January 2027 and may be extended.
State Health Commissioner Dr. James McDonald said the department will advise Hochul on whether further reforms can deliver accountability or whether participants would do better under other services.
“Medicaid is a lifeline for millions of New Yorkers,” Hochul said in a statement. “Protecting that lifeline means defending access to care and defending the integrity of the programs that provide it.”
The program has drawn scrutiny before. A February audit by state Comptroller Thomas DiNapoli found that managed care plans paid $2.4 billion for adult day care services from January 2019 through October 2024. Payments rose more than 141 percent from 2021 to 2023.
Auditors identified $285 million in questionable payments to centers for dates after at least one plan had dropped them from its network. That included more than $28.6 million to centers terminated for cause, such as fraud.
In one case, a center that one plan cut for fraud, waste, and abuse in 2021 stayed in the networks of 18 other plans and was paid more than $12.9 million afterward.
Auditors also found that a Flushing center with a legal capacity of 323 billed for 530 people on a single day in September 2022.
In its response to the audit, the Health Department said the comptroller’s sampling method could overstate how widespread the problems were. The comptroller’s office called that statement misleading.
Earlier this year, two people in Brooklyn pleaded guilty to a $68 million adult day care fraud scheme, according to the governor’s office.
Asked whether ending the benefit would require federal approval and what services the participants would move to, the state Health Department referred The Epoch Times to the governor’s announcement.
Hochul faces Republican Bruce Blakeman in the Nov. 3 governor’s race.
Blakeman’s campaign and CMS did not respond to a request for comment from The Epoch Times before publication.
END
“Gotten Too Old Not To Be Greedy”: Virginia State Sen. Arrested, Accused Of Masterminding $4.5 Million Criminal Drug Enterprise
Thursday, Oct 22, 2026 – 01:00 PM
Virginia’s Democratic Senate President Pro Tempore L. Louise Lucas, 82, has been indicted by a federal grand jury and taken into federal custody on charges of racketeering conspiracy, conspiracy to distribute marijuana, money laundering, honest-services fraud/bribery, and maintaining a drug-involved premises. Six co-defendants, including her daughters and grandson, were also charged. FBI Director Kash Patel put the alleged scheme at roughly $4.5 million.
The 45-page indictment unsealed Thursday in the Eastern District of Virginia alleges that Lucas led a multi-year “Lucas Enterprise” that, since at least 2019, acquired and distributed at least 100 kilograms of illegal marijuana, laundered the proceeds through various business entities, and used her official power to protect the operation while shaping cannabis legislation for personal gain. Lucas self-surrendered Thursday morning and faces an initial appearance before a federal magistrate judge. All defendants are reported to be in custody.
Who She Is and How the Probe Unfolded
Lucas has represented Portsmouth since 1991 and has served as Senate President Pro Tempore and Chair of the Finance and Appropriations Committee – the most powerful budget post in the chamber. She is a longtime, outspoken advocate for marijuana legalization who sponsored key bills and co-owns The Cannabis Outlet, a Portsmouth shop that sells hemp and cannabis products. She is a close ally of Governor Abigail Spanberger and played a central role in Democrats’ 2026 redistricting effort that sought to add Democratic-leaning congressional seats before it was blocked by the Virginia Supreme Court.https://www.youtube.com/embed/IrnxPgTUyq8?si=9_SoU2OFktuEShb1&start=37
The case became public on May 6, 2026, when the FBI executed court-authorized search warrants at Lucas’s Portsmouth district office (which also houses her disabilities-services business, Lucas Lodge LLC) and at The Cannabis Outlet next door. Agents recovered marijuana and firearms from both locations. At the time, Lucas publicly described the raids as political intimidation. Federal sources told Fox News the searches were part of a major corruption probe. The underlying investigation itself predates the current administration and was opened under President Biden. Wiretaps were active for months; at least one Democratic congressman and a local reporter later received notices that their communications with Lucas had been intercepted.
Via Wavy.com:
The response was described as “court-authorized law enforcement activity,” according to FBI Public Affairs Specialist Cassandra Temple. She could not offer additional information.
A spokesperson for the FBI later elaborated in the following statement to WAVY: “The FBI is executing a court-authorized federal search warrant in Portsmouth, VA. There is no threat to public safety. This is an ongoing investigation, and no further information is publicly available at this time.”
The Allegations
Prosecutors say Lucas directed the purchase and sale of large quantities of illegal marijuana under the cover of her licensed medical-cannabis business and used her legislative position to “insulate the enterprise from criminal scrutiny and influenc[e] legislation to financially benefit themselves.”
A central allegation involves an August 2022 payment of $750,000 by Lucas for a 100% stake in a shell holding company created so a co-conspirator could obtain a Virginia recreational marijuana license. She allegedly failed to disclose this interest on required Statements of Economic Interests. She is also accused of receiving a bribery payment from the co-conspirator and of meeting with him at her Capitol office to discuss partial repayment while lobbying other legislators on the license.
Intercepted calls are explicit. In February 2026 Lucas told an unindicted co-conspirator this was their “last chance at generational wealth” and added, “I’ve gotten too old to not be greedy.” In another call she reportedly said she needed the recreational market to open because “when I did it, it was obviously illegal.” She had earlier told a co-conspirator she wanted a recreational license specifically “to create generational wealth for her and her family” and that “this is my last chance.”
The Cannabis Outlet itself received violation notices from the Virginia Department of Agriculture and Consumer Services in 2023 and 2024 for selling non-compliant products.
END
GREG HUNTER…..INTERVIEWING DR JEROME CORSI
Trump Will Stop the Steal in Midterm Elections – Dr. Jerome Corsi
By Greg Hunter On October 21, 2026 In Political Analysis3 Comments
By Greg Hunter’s USAWatchdog.com
With less than two weeks away from the midterm elections, President Trump is making plans to stop Democrat voter fraud. Dr. Jerome Corsi, who has a Harvard PhD in political science, has been on the cutting edge of enforcing election integrity for at least two years. It all comes down to presidential power to stop the cheating. Dr. Corsi says, “President Trump certainly has the power to do it, and he’s well aware of it. So, I think the Department of Homeland Security, the Department of Justice and President Trump are monitoring the situation very carefully. They will have plans to handle various contingencies, I am sure. I cannot imagine President Trump is going to allow the election to be stolen. What is at stake is extremely important. It looks to me like the Democrats are not gaining favor with the American people. This is the whole purpose of my new book called ‘Dumb-O-Crats.’ It’s free this and free that and free everything else . . .. There is no way for a society to have everything to be free. The lies seduce people into thinking this is going to be a utopia, and it’s just the cloak behind the totalitarianism that comes.”
Dr. Corsi says to expect some violence coming from the left before and after the midterms. This recent headline says it all, and reads: “Minnesota Attorney General Keith Ellison Suggests Trump Will Try to Steal Midterms, Tells Leftists to be Ready to ‘Take the Streets.’” Dr. Corsi says, “In regards to what Ellison said, there is a lot of signaling coming out that the Democrat Socialists of America, the Marxist leftists and jihadists that have taken over the Democrat Party are planning a ‘colour revolution’ after the election. In other words, they want to get out in the streets, and they want to cause chaos. They think they can have the insurrection we are seeing in France. This is being signaled pretty strongly right now.”
Dr Corsi says, “We now have a data base that can track every registered voter in the United States and every mail-in ballot in the United States. . .. We can run this by 25 different indices such as tax records, post office moving records to really know who these people are. The data base even permits you to click through to Google maps to see property from which the person registered. We know the cheating has been going on. . .. There are. . . millions of illegal votes being cast.”
Another wild card is traditional Democrats who are not going along with the Marxists and Muslims who have taken over the Democrat Party. There are indications they may not show up on election day or vote Republican as one story recently reported in Michigan. No matter what, expect a wild ride unlike any other midterm election ever. Dr. Corsi warns, “This is not going to end on election day. The steal is going to be attempted. The consequences remain, and the data is available. So, we are just getting into this, and this is just the beginning to a great awakening to the threat to our election integrity. We do need to take exceptional measures to make sure the problem does not continue.”
There is much more in the 29-minute interview.
Join Greg Hunter of USAWatchdog as he goes one-on-one with Dr. Jerome Corsi of GodsFiveStones.com and author of the new book called “Dumb-O-Crats,” as a behind the scenes war is being fought for honest elections in the November midterms for 10.21.26.
After the Interview:
To buy a copy of Dr. Corsi’s new book called “Dumb-O-Crats,” click here.
To donate to fund election integrity by Dr. Corsi and his group, you can make a tax-deductible donation by clicking here. GodsFiveStones.com is a 501(c)(3).
If you go to GodsFiveStones.com, you can see all the election fraud data for free.
You can also donate by snail mail at the address below:
Capstone Legacy Foundation


